- •A yacht policy is a marine contract under admiralty law. Wilburn Boat means state law fills gaps, so the same policy reads differently in FL and SC.
- •The named-storm haul-out warranty is a strict promise; breaching it can void the loss. Know your exact trigger and deadline before the season.
- •Agreed value pays the fixed insured amount on a total loss; actual cash value pays depreciated value, a huge gap on the same hull.
- •Hull covers the boat; protection & indemnity (P&I) covers liability, including wreck removal when your vessel obstructs or damages others.
- •Marina dockage agreements usually disclaim storm liability and push the duty to insure onto you, but not for the marina’s own negligence.
Marine insurance is its own body of law
The first thing to understand about a yacht claim is that you are not in property-insurance land. A vessel policy is a marine insurance contract, and marine insurance sits inside federal admiralty jurisdiction (U.S. Const. art. III; 28 U.S.C. § 1333) with centuries of its own doctrine. The Supreme Court’s decision in Wilburn Boat Co. v. Fireman’s Fund (1955) set the framing courts still use: where there is an established federal admiralty rule, it controls; where there is not, the forum state’s law fills the gap. That single holding is why the identical policy can be interpreted one way in Florida and another in South Carolina.
Two doctrines follow that a homeowner never encounters. Uberrimae fidei, the duty of utmost good faith, obliges the insured to disclose every material fact when the policy is placed; a material misstatement or omission can let the insurer avoid the policy. And express warranties, promises written into the policy about how the vessel will be used, laid up, or protected, traditionally must be strictly complied with. These are not fine-print technicalities. They are the levers a marine insurer reaches for first when a large storm claim lands.
Hull vs. protection & indemnity
A yacht policy usually contains two very different coverages. Hull insures the vessel itself, the boat, machinery, and equipment, against physical loss or damage, and it is the coverage a storm claim runs through when your boat sinks, swamps, or is battered. Protection & indemnity (P&I) is the liability side: injury to others, damage to other vessels or property, and commonly wreck-removal and pollution liability.
After a hurricane both can fire at once. Hull responds to your damaged or sunk vessel. P&I responds when your boat breaks its lines and holes a neighbor’s hull, when it sinks in a fairway and the Coast Guard or state orders it removed, or when fuel escapes. Treating the policy as a single "boat coverage" is how owners miss the liability exposure entirely. The wreck-removal order that arrives days after the storm is a P&I problem, not a hull one, and its cost can exceed the boat’s value.
Agreed value vs. actual cash value
The most consequential term in a yacht policy is how it values the boat. An agreed-value (or "valued") policy fixes the insured value when the policy is written; on a total loss it pays that agreed amount, full stop, with no depreciation argument. An actual-cash-value (ACV) policy pays the depreciated market value at the time of loss, which hands the carrier a subtraction exercise over the boat’s age, engine hours, and condition.
On a partial loss the two can converge; on a total or constructive-total loss they diverge sharply, and that is exactly the loss a hurricane produces. The premium for agreed value buys away the depreciation fight at the moment it matters most. The obligation on your side is to insure to a realistic agreed value: set it too low and you have underinsured the vessel; set it honestly and you have converted the total-loss settlement from an argument into a number.
What agreed value is worth in a total loss
Take one hypothetical $200,000 yacht declared a total loss and pay it two ways. The bars below show what each policy form pays out as a share of the same illustrative $200,000 insured hull value; the depreciation subtracted by the ACV form is the owner’s out-of-pocket gap. The point is the difference between the two forms, not the exact dollars.
Same hull, two settlements
A illustrative example: a $200,000 vessel lost in a storm, paid under an agreed-value policy versus an actual-cash-value policy. Each bar is what the form pays as a share of the same hypothetical $200,000 hull value; the remainder is what the owner absorbs. The point is how the two forms differ, not any specific figure.
Same boat, same storm. The agreed-value form closes the claim at the number you set; in this example the ACV form opens a $72,000 depreciation argument at the worst possible moment. A named-storm deductible, a percentage of hull value, then applies on top of either. Your vessel’s depreciation gap will differ.
About these figures: the $200,000 hull value and the $72,000 ACV depreciation gap (an ACV payout of $128,000) are hypothetical figures chosen to show how agreed-value and actual-cash-value forms settle a total loss differently. They are not a quote, an average, or any real vessel’s claim. Actual depreciation turns on the boat’s age, condition, make, and market at the time of loss, and named-storm deductibles vary by policy. Get a real valuation and read your marine policy’s valuation clause. Do not rely on these figures.
ILLUSTRATIVE EXAMPLE · HYPOTHETICAL $200,000 HULL / $72,000 ACV GAP, NOT A QUOTE OR AVERAGE
The named-storm haul-out warranty
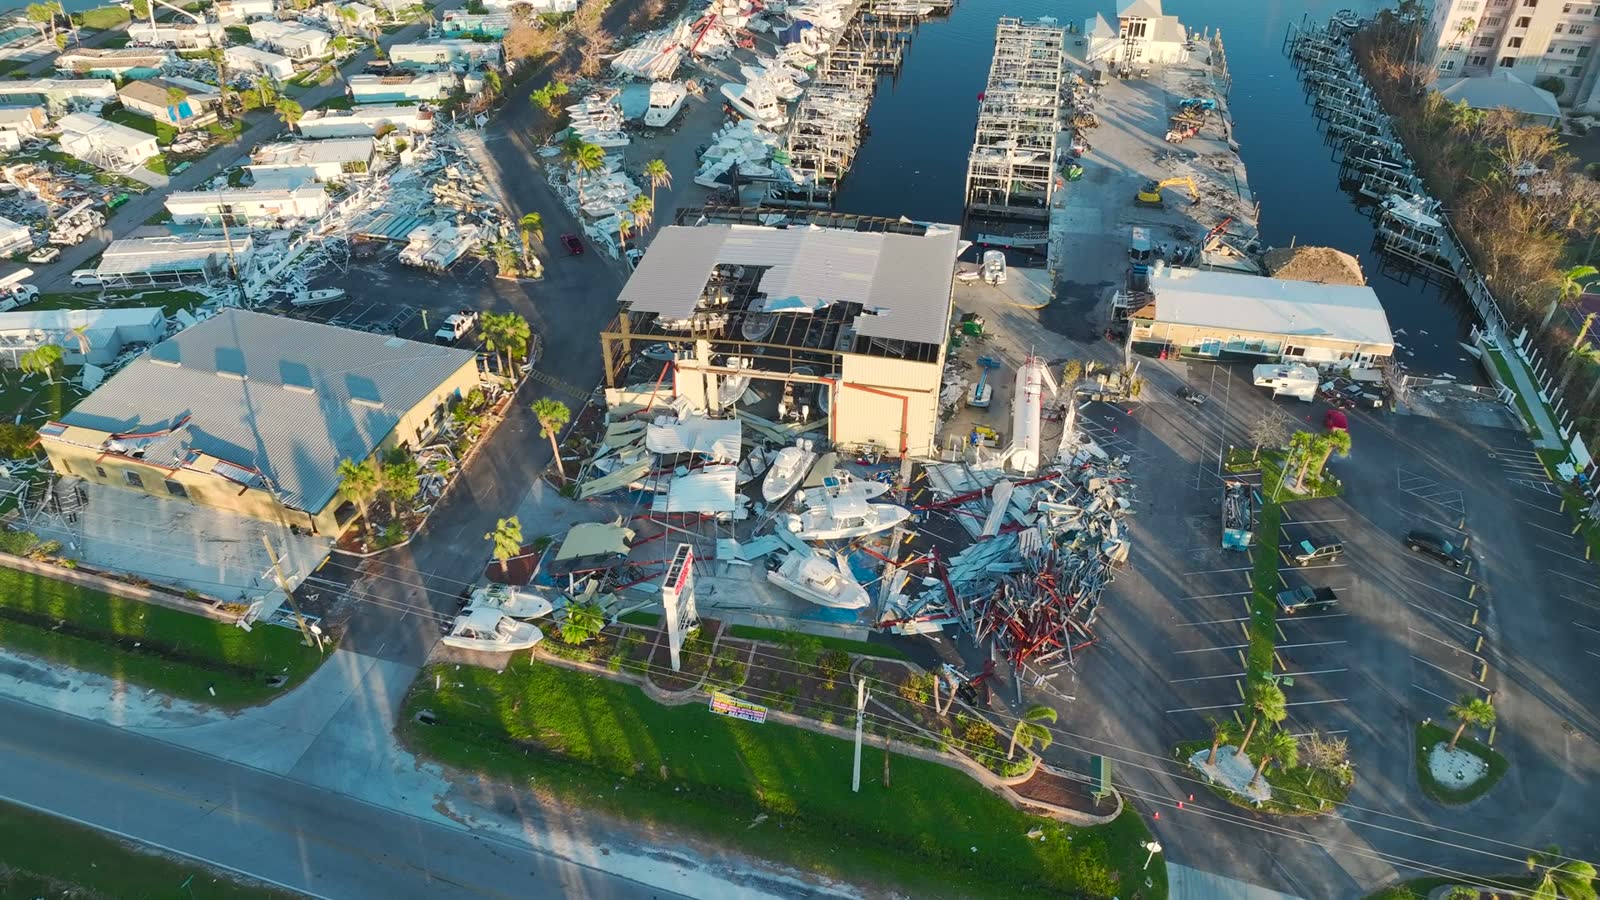
The clause that voids more hurricane yacht claims than any other is the named-storm haul-out warranty (also written as a hurricane-plan or lay-up warranty). It is an express promise that when a named storm threatens, you will take defined protective action (haul the vessel, move it to an approved location, or execute a filed hurricane plan) within a set window, commonly 48 to 72 hours of a hurricane watch or warning for your area.
Because it is a warranty, classic marine law requires strict compliance: breach can bar the claim even if the breach did not cause the loss. Under Wilburn Boat, many states soften that with increase-of-hazard or causation requirements (a warranty breach may only matter if it heightened the risk or contributed to the damage), but the softening varies by state and is never something to bank on. The discipline is simple and unforgiving: read the exact trigger and deadline before the season, file any required hurricane plan, execute it on time, and document that you did, with the haul-out invoice, the timestamped photos, and the tie-down record. Separately, boats laid up under a seasonal navigation or lay-up warranty must watch the geographic and calendar limits, which a storm claim will test.
Salvage, total loss, and wreck removal
Three distinct concepts collide after a boat goes down, and keeping them separate protects the claim. Salvage is the recovery of the vessel from peril; general maritime law can entitle a salvor to an award for saving property, and your hull coverage may pay salvage costs, sometimes subject to a sublimit. Total loss is the valuation question: actual total loss when the boat is destroyed or unrecoverable, or constructive total loss when recovery-plus-repair cost meets or exceeds the insured value (or a policy percentage of it), letting the insurer pay out and take the wreck.
Wreck removal is the third and most dangerous to overlook: a legal duty to remove a sunk or grounded vessel that obstructs navigation or threatens the environment. Authorities (the Coast Guard, or the state under derelict-vessel laws such as Florida’s Fla. Stat. § 823.11 and the derelict/abandoned-vessel statutes) can order the owner to remove it, and that obligation stands independent of the hull payout. Wreck removal is generally a P&I / liability exposure, and after a mass-casualty storm the cost can exceed the boat’s value. Confirm both your salvage sublimit and your wreck-removal coverage; a total-loss check that does not also fund removal can leave you personally on the hook for the wreck.
Marina liability and the storage agreement
Where the boat rode out the storm brings in a second contract: the marina’s dockage or dry-storage agreement. These are usually bailment or license contracts that disclaim liability for weather and storm damage and place the duty to insure squarely on the boat owner. Courts frequently enforce those disclaimers, so the default recovery path for storm damage runs through your own hull policy, not the marina’s.
The disclaimer is not absolute. A marina can still be liable for its own negligence: failing to follow its published hurricane plan, improperly securing or relocating vessels, assigning a berth it knew was unsafe, or breaching a specific duty it assumed by contract. Those exposures run against the marina’s liability coverage, and a well-documented negligence claim can shift a loss the dockage agreement tried to disclaim. The controlling question is the agreement’s risk-of-loss and indemnity language read against what the marina actually did. Review it before hurricane season, not after the boats are already stacked.
The policy language that controls a vessel claim
NAMED-STORM / HURRICANE HAUL-OUT WARRANTY · TYPICAL WORDING"It is warranted that upon the issuance of a Hurricane Watch or Warning by the National Hurricane Center for the waters in which the insured vessel is located, the Assured will remove the vessel from the water or otherwise secure it in accordance with the Hurricane Plan on file within the time specified. Breach of this warranty voids coverage for any loss arising from the named storm."
AGREED-VALUE / TOTAL-LOSS CLAUSE · TYPICAL WORDING"In the event of a total or constructive total loss of the insured vessel, the Insurer will pay the Agreed Value stated in the Declarations, less any applicable named-windstorm deductible, and shall be entitled to the salvage and all rights in the wreck."
The first clause is the trap and the second is the reward. Together they define the two moments that decide a storm claim on the water: whether you kept the warranty, and what number the policy owes when the boat is gone.
Documenting a vessel claim
- Prove you kept the warranty. The haul-out invoice, the executed hurricane plan, timestamped photos of the secured vessel, and the watch/warning timeline: the evidence that defeats a warranty-breach denial before it starts.
- Fix the value in advance. A realistic agreed value with a recent survey and valuation supporting it; on a total loss this is the settlement number, and the survey is what defends it.
- Separate hull from liability. Document the vessel damage for the hull claim and any third-party damage or removal order for the P&I claim; they are different coverages with different limits.
- Capture the wreck and the salvage. Photograph the sunk or grounded vessel in place, keep every salvage and removal invoice, and preserve any authority order to remove it.
- Pull the dockage agreement. Read the risk-of-loss and indemnity language and document what the marina did or failed to do: the record that supports a negligence claim if the disclaimer is contested.
Florida vs. South Carolina
Warranty enforcement
Under Wilburn Boat, FL law can apply an increase-of-hazard / anti-technical lens to warranty breach, but strict-compliance risk remains real; never rely on the softening.
Derelict-vessel duty
FWC enforces derelict/abandoned-vessel law (Fla. Stat. § 823.11 and related); owners can be ordered to remove a storm-wrecked vessel regardless of hull payout.
Bad-faith backstop
Statutory bad-faith framework applies to the insurer’s conduct on the surplus-lines / marine claim where state law governs.
Warranty enforcement
SC gap-filling law governs warranty and disclosure disputes where no federal admiralty rule controls; outcomes can differ from FL on the same policy.
Derelict-vessel duty
DNR administers abandoned/derelict-vessel removal along the coast; owner removal obligations survive the insurance settlement.
Bad-faith backstop
§ 38-59-20 improper-claim-practices statute and common-law bad faith apply where state law reaches the marine claim.
MARINE-LAW SUMMARY JUL 2026
Marine-insurance doctrine, statutes, and deadlines summarized as of July 2026, and the interaction of federal admiralty law and state law is fact-specific. Read your policy and consult maritime counsel before relying on any of this.
Boat and yacht storm claims: the questions owners ask
Why is my yacht claim treated differently from a house claim?
Because it is a marine insurance contract, governed by federal admiralty law and long-settled maritime doctrine rather than ordinary property rules. Under the Supreme Court’s decision in Wilburn Boat Co. v. Fireman’s Fund (1955), where there is an established federal admiralty rule it controls; where there is not, state law fills the gap, so the same policy can be read differently in Florida than in South Carolina. Marine policies also carry doctrines a homeowner never encounters: the duty of utmost good faith (uberrimae fidei) in disclosure, and express warranties that must be strictly complied with. The result is a claim decided on principles most boat owners have never heard of.
What is the difference between hull coverage and protection & indemnity?
They are two different coverages, usually in one yacht policy but sometimes separate. Hull coverage insures the vessel itself (the boat, machinery, and equipment) against physical loss or damage, and this is the part a storm claim runs through. Protection & indemnity (P&I) is the liability side: injury to others, damage to other property or vessels, and often wreck-removal and pollution liability. After a hurricane both can be in play at once: hull for your sunk or battered boat, P&I when your vessel breaks loose and damages a neighbor’s boat or the marina, or when authorities order the wreck removed. Reading them as one coverage is a common and costly mistake.
What does a named-storm or hurricane haul-out warranty require, and what happens if I miss it?
It is an express promise in the policy (a warranty) that you will take specific protective action when a named storm threatens: commonly hauling the vessel out of the water, moving it to an approved storage location, or executing a filed hurricane plan within a set time (often 48 to 72 hours) of a hurricane watch or warning for your area. In classic marine law, a warranty must be strictly complied with, and breach can void coverage for the loss regardless of whether the breach caused the damage. Many states, applying state law under Wilburn Boat, soften that with increase-of-hazard or causation rules, but you should never rely on that softening. Know your warranty’s exact trigger and deadline before the season, and document that you met it.
My policy pays "agreed value." Is that better than actual cash value?
On a total loss, almost always yes. An agreed-value (or "valued") policy fixes the vessel’s insured value when the policy is written, and on a total loss it pays that agreed amount without a depreciation fight. An actual-cash-value (ACV) policy pays the depreciated market value at the time of loss, which invites the carrier to subtract age, hours, and condition, often tens of thousands of dollars on the same boat. The trade-off is premium and the requirement to insure to a realistic agreed value. For a total or constructive-total-loss storm claim, agreed value is the single most valuable term in the contract.
The insurer says my boat is a "constructive total loss." What does that mean?
A constructive total loss (CTL) means the vessel is not literally destroyed but the cost to recover and repair it equals or exceeds its insured value (or a policy-defined percentage of it). Declaring a CTL lets the insurer pay the total-loss amount and take the wreck rather than fund an uneconomic repair. The disputes are the repair estimate (which drives whether the CTL threshold is met), the salvage and recovery cost included in that math, and, on an agreed-value policy, whether you are paid the full agreed value. On an ACV policy the CTL number is the depreciated value, which is exactly why agreed value matters most at the total-loss margin.
Who pays to raise or remove my sunken boat after a hurricane?
Salvage and wreck removal are governed by maritime law and by your policy’s specific provisions. Salvage, recovering the vessel, may be covered under the hull section, sometimes with a sublimit, and general maritime law can entitle a salvor to an award for saving property in peril. Wreck removal (the legally compelled removal of a sunk or grounded vessel that obstructs navigation or threatens the environment) is typically a P&I / liability exposure, and authorities can order the owner to remove it regardless of the hull payout. After a mass-casualty storm these obligations arrive fast and can exceed the boat’s value; confirm both your salvage sublimit and your wreck-removal coverage before you need them.
My boat was in a marina that said it wasn’t responsible for storm damage. Is that enforceable?
Often, yes. Marina dockage and storage agreements are typically bailment or license contracts that disclaim liability for weather and storm damage and shift the duty to insure onto the boat owner. Those disclaimers are frequently enforced, though not always: a marina can still be liable for its own negligence, such as failing to follow its own hurricane plan, improperly securing vessels, or breaching a specific duty it assumed. The marina carries its own liability coverage for those exposures. Read the dockage agreement’s risk-of-loss and indemnity language before the storm; it determines whether your recovery runs through your own hull policy, the marina’s liability, or both.
- U.S. SUPREME COURT Wilburn Boat Co. v. Fireman’s Fund Ins. Co., 348 U.S. 310 (1955): state law governs marine insurance absent an established admiralty rule ↗
- CORNELL LII U.S. Const. art. III & 28 U.S.C. § 1333: federal admiralty jurisdiction ↗
- BOATUS BoatUS: hurricane preparation, haul-out plans, and named-storm coverage ↗
- FL LEGISLATURE Fla. Stat. § 705.101 et seq. / § 823.11: derelict and abandoned vessels; owner removal duty ↗
- SC STATEHOUSE S.C. Code § 38-59-20: improper claim practices ↗
- NOAA / NHC NHC Tropical Cyclone Report, Hurricane Ian (PDF) ↗
Not legal advice; consult an attorney about your specific claim.
Marine policies run on their own rules, and named-storm clauses can bar the claim.
Boat and yacht coverage sits under marine policies, not standard property forms. Agreed-value hull coverage pays a figure set when the policy binds; actual-cash-value coverage pays market value at the time of loss less depreciation, which on an older vessel can be a fraction of replacement cost. Many policies also carry a named-windstorm haul-out clause that reduces or voids coverage if the vessel was not pulled from the water or secured to a named-storm plan before the storm.
The haul-out and captain-warranty clauses are where marine carriers deny: if the policy required the boat out of the water and it was not, the carrier points to breach of warranty and declines the whole loss. Photograph the vessel, dock lines, and storage location and keep the marina agreement, because the photo protocol and a clean paper trail answer the warranty argument. Surge and wind both damage vessels and docks, and the policy splits them: see how wind and hurricane and storm surge coverage divide a waterfront loss, the same trigger question running through stadium and event property. Delay can support a bad-faith claim, and a public adjuster or marine surveyor can dispute the valuation. The free review below reads your hull basis and the named-storm clause.
Vessel claim denied on a warranty or undervalued?
Send the policy, the survey, and your haul-out documentation. You’ll get a straight answer on whether the warranty breach, the depreciation, or the wreck-removal call actually holds up under marine law.

 HURRICANELAW.PRO
A comprehensive property-insurance claim resource for policyholders: denied and underpaid claims, coverage and bad-faith law, storm dossiers, carrier profiles, city guides, and the complete claims playbook. Florida and South Carolina.
▸ SEE THE FULL SITE MAP →Coverage summaries, policy-language quotations, dollar figures, deadlines, and chart examples throughout this site are general information based on typical or standard policy forms and are illustrative only: they are not a quote, a guarantee of coverage, or a promise of any outcome. Every insurance policy is different: your own policy, endorsements, and state law control, so read your policy and confirm current statutes. Weather imagery courtesy of NOAA, the National Hurricane Center, and the National Weather Service. Legal services are provided by Halversen Law. Nothing on this site is legal advice; consult an attorney about your specific claim.
Legal matters are handled by Halversen Law, a law firm licensed in Florida and South Carolina.