Does homeowners insurance cover hurricane damage?
Wind damage yes, water from surge or flooding no. A hurricane or named-storm deductible applies, and it is a percentage of your dwelling limit rather than of the loss: 5 percent on a $400,000 dwelling limit is $20,000 out of pocket before the carrier pays anything at all.
| Covered | Wind damage to roof, windows, walls, and interior water that entered through a storm-created opening. |
|---|---|
| Not covered | Storm surge and rising water. Those need NFIP or private flood coverage. |
| Deductible | 2 to 10 percent of the dwelling limit, applied per named storm or per season depending on the policy. |
| Trigger | Policy language defines when the hurricane deductible attaches, usually tied to NHC watch and warning times. |
- •Yes, hurricane wind is covered on standard homeowners policies, roof to contents, plus rain through a wind-created opening.
- •But it runs behind a hurricane deductible of 2-10% of your dwelling limit, for example, $8K-$40K on a $400K home, not a flat $1,000.
- •Florida applies one hurricane deductible per calendar year (Fla. Stat. § 627.701), a second storm in the same season doesn't reset it.
- •Coastal zones: carriers may exclude wind entirely, Citizens (FL) and the SC wind pool exist to write what they won't.
- •The main coverage threat isn't the exclusion. It's reclassification: covered wind damage denied as wear and tear.
What wind coverage actually pays for
Windstorm is a named peril on every standard homeowners form, and on the HO-3, the most common policy, the dwelling is covered on an "open perils" basis: every cause of loss is covered unless an exclusion removes it, and wind is not on the exclusion list. When hurricane wind is the cause, the policy responds across all four coverage parts:
- Coverage A: Dwelling. The roof system, walls, windows, doors, attached structures. This is also the number your hurricane deductible is computed from.
- Coverage B: Other structures. Detached garages, fences, sheds, pool enclosures, typically limited to 10% of Coverage A.
- Coverage C: Contents. What the wind and the rain that followed it destroyed inside. Often paid at actual cash value unless you bought replacement cost on contents.
- Coverage D: Loss of use / ALE. Hotel, rent, and increased living costs while the house is uninhabitable from a covered wind loss.
The coverage extends past the direct hit. Rain that enters through an opening the wind created, the stripped shingle field, the window taken out by debris, is part of the wind loss. A tree the wind dropped through your roof is a wind loss, including tree removal up to the policy's limit. What wind coverage does not reach: rising water. Storm surge and flood are excluded from every homeowners policy no matter how hard the wind pushed the water. That split is its own guide.
The policy language that controls a wind claim
Three clauses decide most hurricane wind claims before an adjuster ever climbs your roof. Find all three in your own policy, the wording varies by carrier and form year, and the variations matter.
HURRICANE DEDUCTIBLE PROVISION (FLORIDA FORM, TYPICAL WORDING PER FLA. STAT. § 627.701 / § 627.4025)"The hurricane deductible applies to loss caused by windstorm during a hurricane. It applies for the duration of the hurricane, beginning when a hurricane watch or warning is issued for any part of Florida, and ending 72 hours following the termination of the last hurricane watch or warning… THIS POLICY CONTAINS A SEPARATE DEDUCTIBLE FOR HURRICANE LOSSES, WHICH MAY RESULT IN HIGH OUT-OF-POCKET EXPENSES TO YOU."
WINDSTORM EXCLUSION ENDORSEMENT (COASTAL-ZONE POLICIES: IF YOU HAVE THIS, WIND IS NOT COVERED HERE)"We do not insure for loss to property described in Coverages A and B caused directly or indirectly by Windstorm or Hail… This exclusion applies regardless of any other cause or event contributing concurrently or in any sequence to the loss."
THE RAIN LIMITATION: WHERE WIND CLAIMS TURN INTO WIND-DRIVEN-RAIN DENIALS"We do not insure for loss to the property… caused by rain, snow, sleet, sand or dust unless the direct force of wind or hail damages the building causing an opening in a roof or wall and the rain… enters through this opening."
The first clause sets how much of the loss you absorb. The second, if present, removes the peril entirely and sends you to a separate wind policy. The third is the hinge of the most common interior-damage fight: the carrier concedes the wind but denies the water, arguing no "opening" was created, the wind-driven-rain denial in its natural habitat.
The hurricane deductible: a percentage of the house, not the loss
The single most misunderstood number in hurricane insurance. A hurricane deductible is not a percentage of your damage. It is a percentage of your Coverage A dwelling limit, the full insured value of the house. Florida law requires carriers to offer deductible options of $500, 2 percent, 5 percent, and 10 percent of the dwelling limit (Fla. Stat. § 627.701), with the percentage disclosed in bold type on the policy face. South Carolina coastal policies carry comparable named-storm or wind/hail percentage deductibles by contract.
Same roof, same storm, three deductibles
Your hurricane deductible is a percentage of what the house is insured for, not a percentage of the damage. The $400,000 home value and the $30,000 roof loss below are example figures, not a quote or an appraisal, chosen only to show how the identical loss pays out under each deductible option. Your own dwelling limit and repair cost will differ.
Every bar is the same example $30,000 loss. Only the deductible changes, and at 10% it swallows the claim whole. Run your own dwelling limit and loss in the deductible calculator.
What's assumed here: the $400,000 dwelling limit and the $30,000 roof loss are hypothetical figures chosen to illustrate how a percentage deductible works. They are not a quote, an appraisal, or survey data, and real dwelling limits and repair costs vary widely. The $500 / 2% / 5% / 10% choices are the deductible options Florida law (Fla. Stat. § 627.701) requires carriers to offer; your declarations page shows which one you selected. Read your policy and get a real written estimate, do not rely on these numbers.
ILLUSTRATIVE EXAMPLE · DEDUCTIBLE OPTIONS PER FLA. STAT. § 627.701 · HYPOTHETICAL $400K DWELLING LIMIT / $30K LOSS
The chart is why so many hurricane claims are "closed without payment, below deductible." After Ian, carriers cited below-deductible damage as a leading closure reason. Some of those closures were honest math. Others were first-visit estimates that missed decking, underlayment, and interior damage that would have cleared the deductible easily, which is why a below-deductible closure letter deserves the same scrutiny as a denial.
One season, one deductible: Florida's statute
Florida answered the two-storms problem by statute. Under Fla. Stat. § 627.701(5)(a), the hurricane deductible applies on an annual, calendar-year, basis. If a second hurricane damages your home in the same calendar year, the deductible you already absorbed counts: the policyholder generally owes only the remainder of the hurricane deductible, and once it is fully met, subsequent hurricane losses that year are subject to the ordinary "all other perils" deductible instead.
The rule earned its keep in 2024. Helene struck the Gulf coast on September 26; Milton crossed many of the same counties on October 9, thirteen days later. For a household with a $20,000 hurricane deductible and damage from both storms, per-storm application would have meant $40,000 absorbed before the first dollar of coverage. The calendar-year statute halved that, if the policyholder could document which storm did what, since each claim is still a separate file. The practical consequence: after a first storm, photograph everything, even losses below the deductible. Those records are both your deductible credit and your storm-allocation evidence when the second storm hits.
South Carolina has no equivalent statute. Whether a named-storm deductible applies per occurrence or per season is purely a policy-wording question, and worth answering before June, not after landfall.
Where wind is excluded: Citizens and the wind pool
The deepest version of the coverage question isn't the deductible. It's whether your policy covers wind at all. In high-risk coastal zones, private carriers have long refused to write the wind peril, excluding it by endorsement. Both states answered with state-created machinery:
Florida, Citizens Property Insurance Corporation. Created by the legislature in 2002 (Fla. Stat. § 627.351(6)) from the merger of the wind-pool and residual-market associations that followed Hurricane Andrew, Citizens is the state's insurer of last resort. It writes full multiperil policies where the private market won't, and wind-only policies in designated coastal areas where a private carrier covers everything except wind. After the post-Ian market contraction, Citizens' policy count swelled past a million, making the state-run insurer the single largest hurricane wind insurer in Florida.
South Carolina, the Wind and Hail Underwriting Association. The SC "wind pool" writes wind and hail coverage for properties in the designated coastal Beach Area, barrier islands and seaward territory from the Grand Strand to Hilton Head, where private policies exclude windstorm. A coastal SC homeowner commonly carries two or three policies on one house: a homeowners policy excluding wind, a wind-pool policy covering wind and hail, and a flood policy for rising water. Hugo's 1989 landfall at Sullivan's Island, the first U.S. catastrophe to top $4 billion in insured claims, is the storm that pushed the pool into its modern role.
The claims consequence of the split: after a hurricane, a coastal household may face two or three adjusters, each with an incentive to attribute damage to another policy's peril. The wind-vs-water allocation fight works exactly the same way between a wind pool and a flood carrier as between a homeowners carrier and the NFIP.
Opening-protection credits: the discounts the law makes them give you
Florida is one of the few states where wind-mitigation discounts are mandatory. Fla. Stat. § 627.0629 requires residential insurers to credit construction features that demonstrably reduce wind loss. The features that move the premium, roughly in order of impact:
- Opening protection, impact-rated windows and doors or code-rated shutters on every opening. The "all openings" credit is the one most homes miss by one unprotected window.
- Roof-to-wall attachment, hurricane clips or wraps versus toe-nails, read in the attic.
- Roof deck attachment, nail size and spacing holding the decking to the trusses.
- Roof shape, a hip roof (slopes on all sides) outperforms gable ends and earns its own credit.
- Secondary water resistance, a sealed roof deck that keeps rain out after shingles fail.
The features are documented on a uniform mitigation verification inspection form completed by a licensed inspector, typically $75-150, often repaid several times over in the first year's premium. The claims-side bonus is underrated: a wind-mitigation inspection is dated, third-party proof of your roof's pre-storm condition and attachment, exactly the evidence that defeats a wear-and-tear reclassification later. South Carolina has no mandate, but the SC Safe Home grant program and voluntary FORTIFIED-standard credits from coastal carriers and the wind pool serve the same function.
How to document a wind loss
Wind claims are won on the file, and the file has a before and an after. Before the season: photograph the roof from the ground on all four sides, keep the last roofing invoice, keep the wind-mitigation report. After the storm, in order:
- Shoot everything before anyone touches it, wide shots establishing the whole elevation, then mid, then close-ups of each damage point. Interior ceilings and walls the same day. Our photo protocol is the full method.
- Capture the wind evidence itself, creased shingle tabs, lifted field edges, debris impact points, the direction damage faces. Wind leaves directional signatures; photograph them before tarps hide them.
- Mitigate, then keep the receipts, tarping and dry-out are your duty under the policy and every invoice is recoverable. Do not make permanent repairs before inspection.
- Pull the storm data for your address, peak gusts from nearby stations and the storm's wind field put a number behind "the wind did this." Start with our storm history lookup.
- Notice the claim inside the deadline, Florida allows 1 year from date of loss to give notice, 18 months for supplemental claims (Fla. Stat. § 627.70132). The carrier then owes a pay-or-deny decision within 60 days (§ 627.70131). South Carolina runs on "prompt notice" wording and a 3-year suit period.
The denial patterns on wind claims
Wind is covered, so wind denials almost never say "not covered." They reclassify. The four recurring moves, each with a dedicated counter-guide:
"Wear and tear, not wind"
The signature Michael-era denial: storm-creased shingles attributed to age and "deferred maintenance." Beaten with pre-storm photos, wind data, and pattern evidence.
The counter-guide →"Wind-driven rain, no breach"
Interior water damage denied because the rain allegedly entered an intact envelope. The fight is proving the wind-created opening existed first.
The counter-guide →"Repair the slope, not the roof"
Patch estimates for partial damage. Florida's matching rule (Fla. Admin. Code / § 626.9744 line) and discontinued-material evidence answer it.
The counter-guide →"That was surge, not wind"
On the coast, the wind carrier attributes the loss to excluded rising water. Sequence evidence, wind records, high-water marks, engineering, decides it.
The counter-guide →Michael and Ian: what wind claims look like at scale
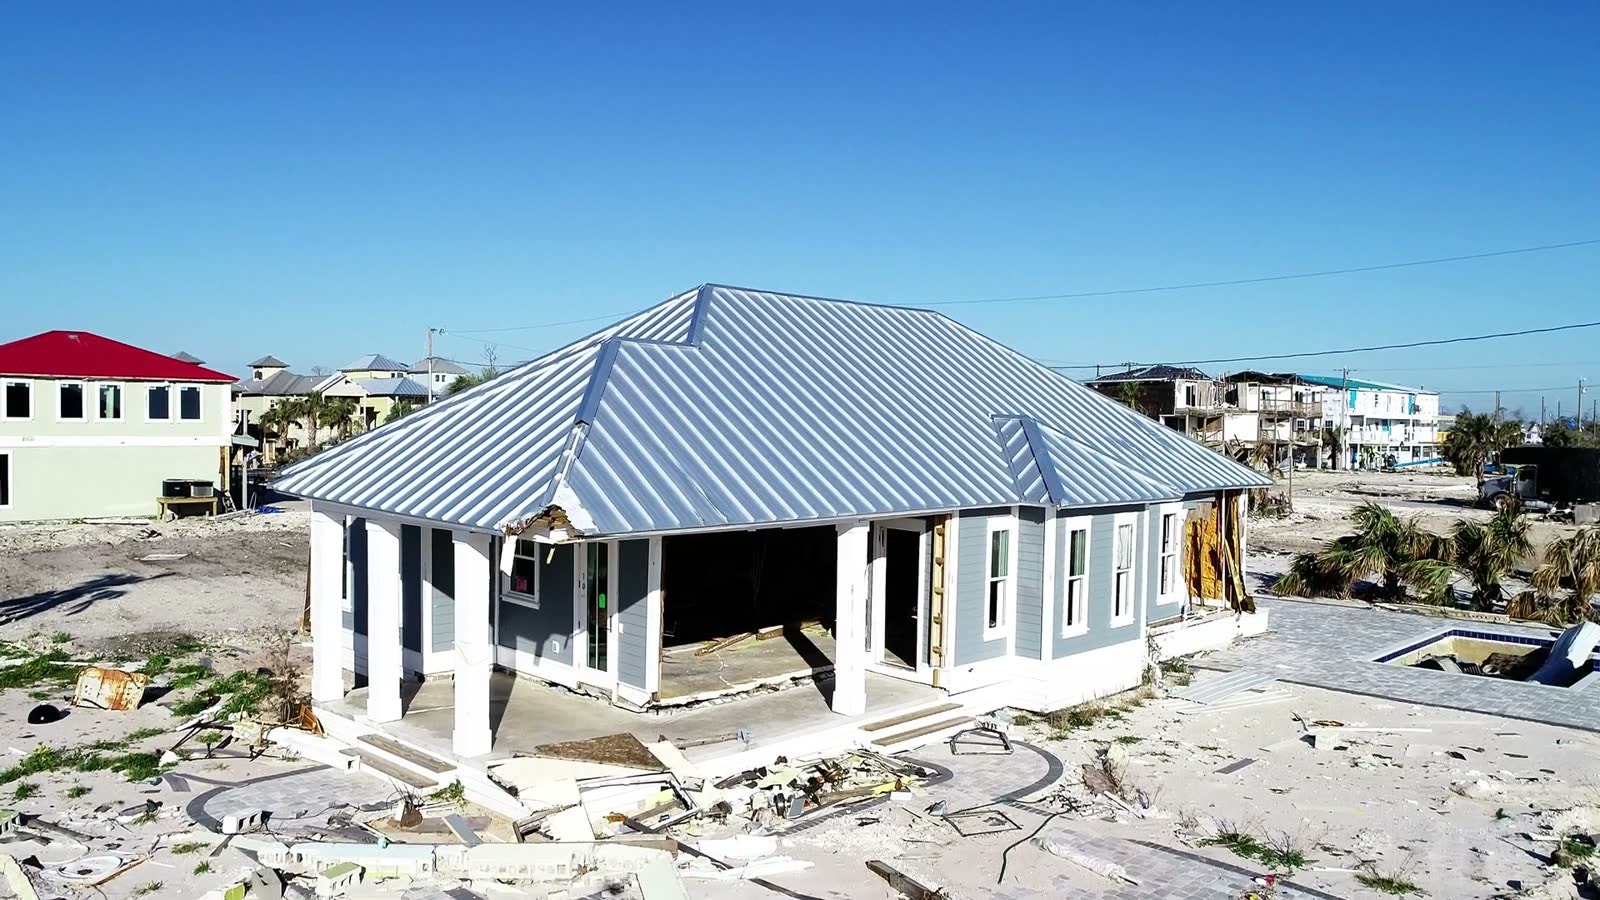
Michael, 2018, the pure wind case study. A Category 5 at Mexico Beach, 160 mph, 919 mb, Michael stripped roofs by the tens of thousands miles inland from the surge zone. Panama City and Lynn Haven, far from the water, became the epicenter of the claims fight: 149,773 claims, $7.4 billion in insured losses, and Bay County alone accounting for 95,184 claims. The aftermath defined the modern wind-denial playbook, initial roof estimates far below replacement cost, matching disputes over partial repairs, interior water attributed to "wear and tear" rather than wind-created openings. Two years after landfall, FLOIR data showed 14 percent of residential claims still unpaid; the litigation wave that followed helped push seven Florida insurers into insolvency between Michael and Ian.
Ian, 2022, wind and water on the same street. Ian came ashore at Cayo Costa as a high-end Category 4-150 mph sustained, gusts near 140 mph recorded at Cape Coral, and produced one of the worst combined wind-and-surge demolition events in Florida history: $112.9 billion in damage, over 770,000 claims, Lee County alone generating 229,000+. On the barrier islands the wind claim and the flood claim fought over the same slab; inland across Lee and Charlotte counties, straight wind shredded roofs with no surge in sight. Roughly 28 percent of residential claims closed without payment, and Lee County juries later ordered wind carriers to pay six-figure verdicts on losses the carriers had attributed entirely to surge, proof that the wind story, properly documented, wins.
The two storms bracket the coverage lesson of this page: inland, the fight is cause, wind versus wear. On the coast, the fight is allocation, wind versus water. Same policy, same peril, different war.
Florida vs. South Carolina
- Hurricane deductible: statutory options of $500 / 2% / 5% / 10% of Coverage A (§ 627.701); applies from hurricane watch/warning to 72 hours after (§ 627.4025); one deductible per calendar year (§ 627.701(5)(a)).
- Wind-exclusion zones: Citizens Property Insurance Corp. writes wind-only and full policies where the private market won't (§ 627.351(6)).
- Mitigation credits: mandatory discounts for opening protection, roof shape, and attachments (§ 627.0629).
- Claim deadlines: 1 year to notice, 18 months supplemental (§ 627.70132); pay-or-deny in 60 days (§ 627.70131); replacement-cost and matching rules (§ 627.7011, § 626.9744).
- Named-storm deductibles: contractual, not statutory, percentage triggers and per-storm vs. per-season application depend on policy wording.
- Wind-exclusion zones: the SC Wind and Hail Underwriting Association (wind pool) writes wind/hail in the designated coastal Beach Area; Hugo (1989) built its modern role.
- Mitigation: no statutory mandate; SC Safe Home grants and voluntary FORTIFIED credits from coastal carriers.
- Claim deadlines: "prompt" notice per policy; no fixed pay-or-deny statute (reasonableness standard); 3-year contract suit period; improper-claims-practices law (S.C. Code § 38-59-20) as the conduct backstop.
Statutes and deadlines summarized as of July 2026; policy-specific provisions can differ. Read your policy and verify current statute text before relying on it.
Hurricane wind coverage, the questions everyone asks
Does homeowners insurance cover hurricane wind damage?
Yes. Windstorm, including hurricane wind, is a covered peril on standard homeowners forms, and on HO-3 dwelling coverage it is covered as part of the open-perils promise. Wind damage to the roof, walls, windows, and structures, plus rain that enters through a wind-created opening, is covered. The qualifiers: a separate hurricane or wind deductible applies, and in some coastal zones the wind peril is excluded from the base policy and insured separately.
What is a hurricane deductible and how is it calculated?
A hurricane deductible is a separate, higher deductible that applies only to hurricane losses, calculated as a percentage of your Coverage A dwelling limit, not as a percentage of the loss. Florida law (Fla. Stat. § 627.701) requires insurers to offer options of $500, 2%, 5%, and 10% of the dwelling limit. On a $400,000 dwelling limit, used here only as an example. Those percentages work out to $8,000, $20,000, and $40,000; your own limit and selected percentage will differ. In Florida the deductible window is defined by statute: it applies to windstorm losses during a hurricane, from the issuance of a hurricane watch or warning until 72 hours after the last watch or warning ends.
Two hurricanes hit me in one season. Do I pay the deductible twice?
In Florida, generally no. Fla. Stat. § 627.701(5)(a) applies the hurricane deductible on an annual (calendar-year) basis: if a second hurricane strikes in the same season, you get credit for what you already absorbed, and the remaining losses are typically subject to the policy’s "all other perils" deductible once the full hurricane deductible has been met. This was a live issue for Helene, Milton households in 2024. South Carolina has no equivalent statute, whether a named-storm deductible applies per storm or per season depends on your policy wording.
My policy excludes windstorm. How is that legal, and who covers me?
In designated coastal areas, private carriers may exclude the wind peril from the homeowners policy, and the risk is written separately. In Florida, wind-only coverage for eligible coastal properties is available through Citizens Property Insurance Corporation, the state-created insurer of last resort. In South Carolina, the South Carolina Wind and Hail Underwriting Association, the "wind pool", writes wind and hail coverage in the designated coastal Beach Area when the private market won’t. If your policy has a wind exclusion and you have no separate wind policy, hurricane wind damage is uninsured.
The carrier says my roof damage is wear and tear, not wind. Now what?
This is the single most common hurricane wind denial. Wind damage has signatures, creased and folded shingles along uplift lines, tabs torn at the nail line, directional patterns matching the storm’s wind field. That age does not produce. Counter it with date-stamped pre-storm photos, wind data for your address, and an independent inspection. Our guide on wear-and-tear denials takes the argument apart step by step.
Do shutters and impact windows actually lower my premium?
In Florida, yes, by law. Fla. Stat. § 627.0629 requires insurers to give premium discounts or credits for construction features that reduce wind loss: opening protection (shutters, impact-rated glass), roof shape, roof-deck attachment, and roof-to-wall connections. The discounts are documented through a uniform mitigation verification inspection. South Carolina offers no statewide mandate, but the SC Safe Home program has provided grants for mitigation, and many carriers offer fortified-home credits voluntarily.
Is rain damage inside my house covered as wind damage?
It depends on how the rain got in. Rain that enters through an opening the wind created, a lifted shingle field, a breached window, a hole from wind-borne debris, is generally covered as part of the wind loss. Rain that the carrier attributes to a pre-existing gap, worn flashing, or "wind-driven rain" penetrating an intact envelope is where denials concentrate. The wind-driven-rain fight is its own guide.
- FL LEGISLATURE Fla. Stat. § 627.701, deductibles; hurricane deductible options and calendar-year application ↗
- FL LEGISLATURE Fla. Stat. § 627.4025, definition of hurricane coverage and the 72-hour window ↗
- FL LEGISLATURE Fla. Stat. § 627.0629, windstorm mitigation discounts and credits ↗
- FL LEGISLATURE Fla. Stat. § 627.70132, notice of property insurance claim (1-year / 18-month windows) ↗
- CITIZENS Citizens Property Insurance Corporation, coastal / wind-only accounts ↗
- SCWHUA South Carolina Wind and Hail Underwriting Association (SC wind pool) ↗
- SC DOI SC Dept. of Insurance, coastal property and wind coverage resources ↗
- NOAA / NHC NHC Tropical Cyclone Report, Hurricane Michael (PDF) ↗
- NOAA / NHC NHC Tropical Cyclone Report, Hurricane Ian (PDF) ↗
- FLOIR FLOIR Hurricane Michael claims data ↗
- FLOIR FLOIR Hurricane Ian catastrophe claims data ↗
Not legal advice; consult an attorney about your specific claim. FLOIR claim statistics as reported in the agency's catastrophe data releases.
A wind claim is won on the wind story, not the roof.
A hurricane claim is decided by whether the file proves wind, not age, moved the damage. The carrier's first move on a roof is wear and tear: old shingles, failing seals, a storm that only exposed what time had done. Beat it with dated proof, creased shingles and directional debris. Florida roof age also drives what you collect: newer statutes let insurers pay actual cash value on roofs past a set age, so read your roof coverage terms first. The hurricane deductible is a percentage of the dwelling limit, often 2% to 5%, so a large loss can carry a five-figure deductible.
The record is the claim. Photograph the roof, interior stains, and debris before any tarp, date every frame, and keep receipts from dry-in to final repair. Work the claims process in order and mind the deadlines: Florida allows one year to notice and 18 months for a supplemental, then 60 days for the carrier's decision. Twenty-eight percent of residential Ian claims closed without payment. A public adjuster can rebuild the estimate; a documented wind story makes it stick. The free review below reads your denial and scope and tells you what to file next.
Wind claim shorted, stalled, or reclassified?
Upload the estimate or denial letter and your photos. You'll get a straight answer on whether the deductible math, the "wear and tear" call, or the scope of the estimate actually holds up.

 HURRICANELAW.PRO
A comprehensive property-insurance claim resource for policyholders: denied and underpaid claims, coverage and bad-faith law, storm dossiers, carrier profiles, city guides, and the complete claims playbook. Florida and South Carolina.
▸ SEE THE FULL SITE MAP →Coverage summaries, policy-language quotations, dollar figures, deadlines, and chart examples throughout this site are general information based on typical or standard policy forms and are illustrative only: they are not a quote, a guarantee of coverage, or a promise of any outcome. Every insurance policy is different: your own policy, endorsements, and state law control, so read your policy and confirm current statutes. Weather imagery courtesy of NOAA, the National Hurricane Center, and the National Weather Service. Legal services are provided by Halversen Law. Nothing on this site is legal advice; consult an attorney about your specific claim.
Legal matters are handled by Halversen Law, a law firm licensed in Florida and South Carolina.