IN SHORT: FOR THE CREW
- • Photograph and document damage plane-by-plane with a scale reference, the record that survives a carrier’s aerial-photo challenge.
- • A contractor scopes and builds. Adjusting the claim, negotiating the payout, or advising on coverage is a different licensed activity. Do not cross into it.
- • Florida now prohibits post-loss assignment-of-benefits (AOB) agreements under property policies issued on or after January 1, 2023 (Fla. Stat. § 627.7152(13)). Read any AOB carefully and get legal review before using one.
- • Never offer to "waive the deductible" or "handle the whole claim." Both create real liability and can be fraud.
- • When a covered scope is denied or the carrier alleges the damage isn’t storm-related, that’s a coverage dispute between the homeowner and the carrier.
Four steps that make a scope payable
Shoot before you touch
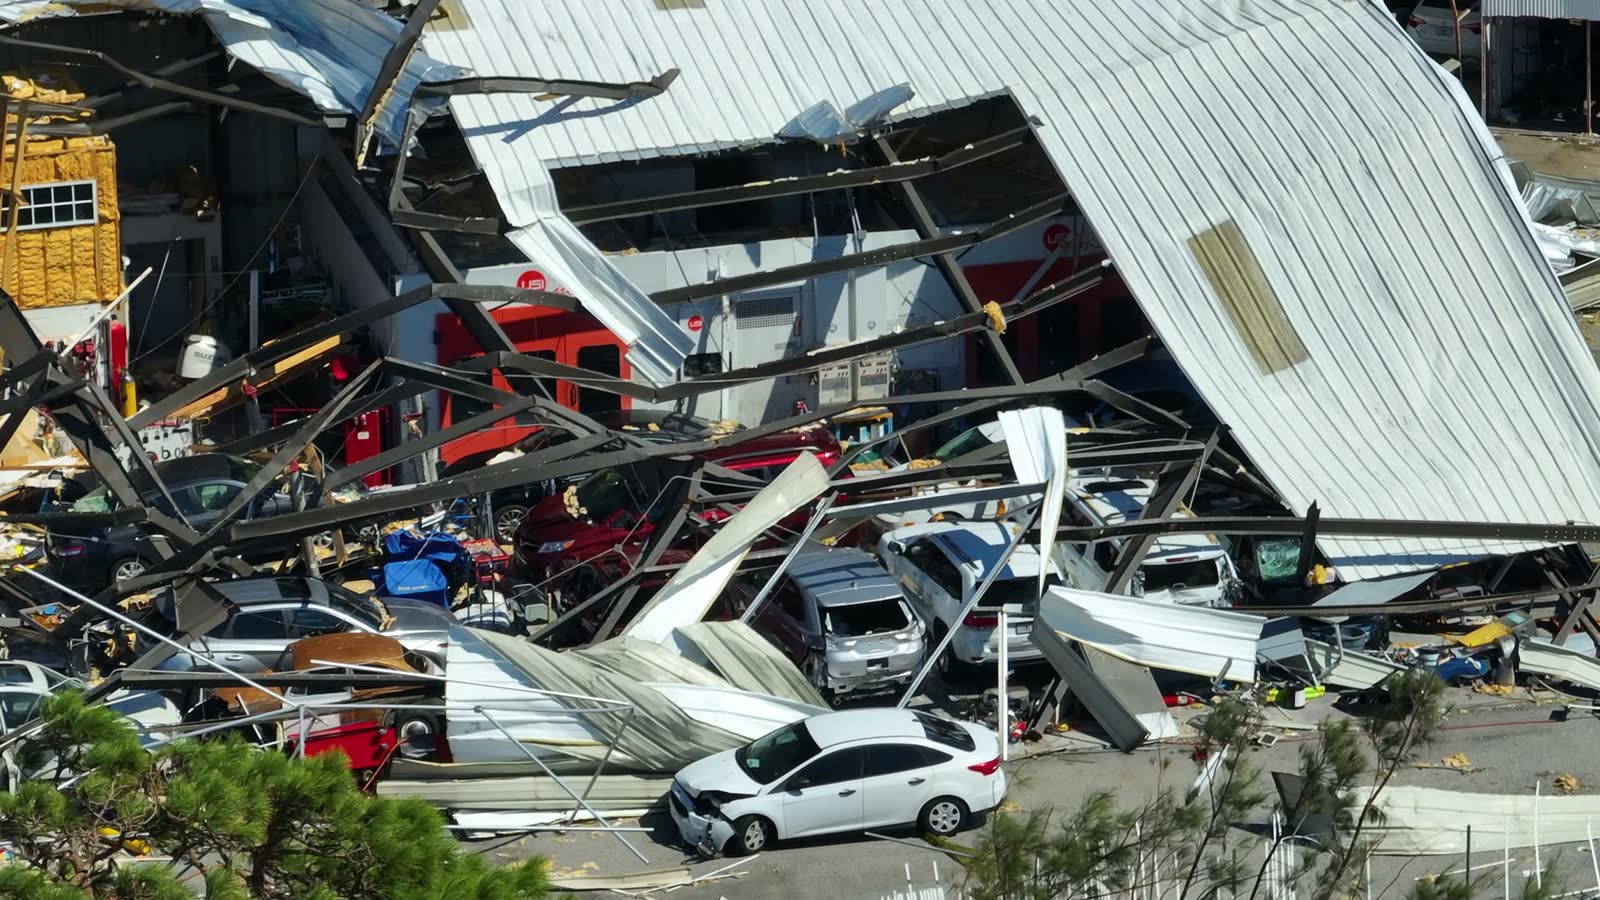
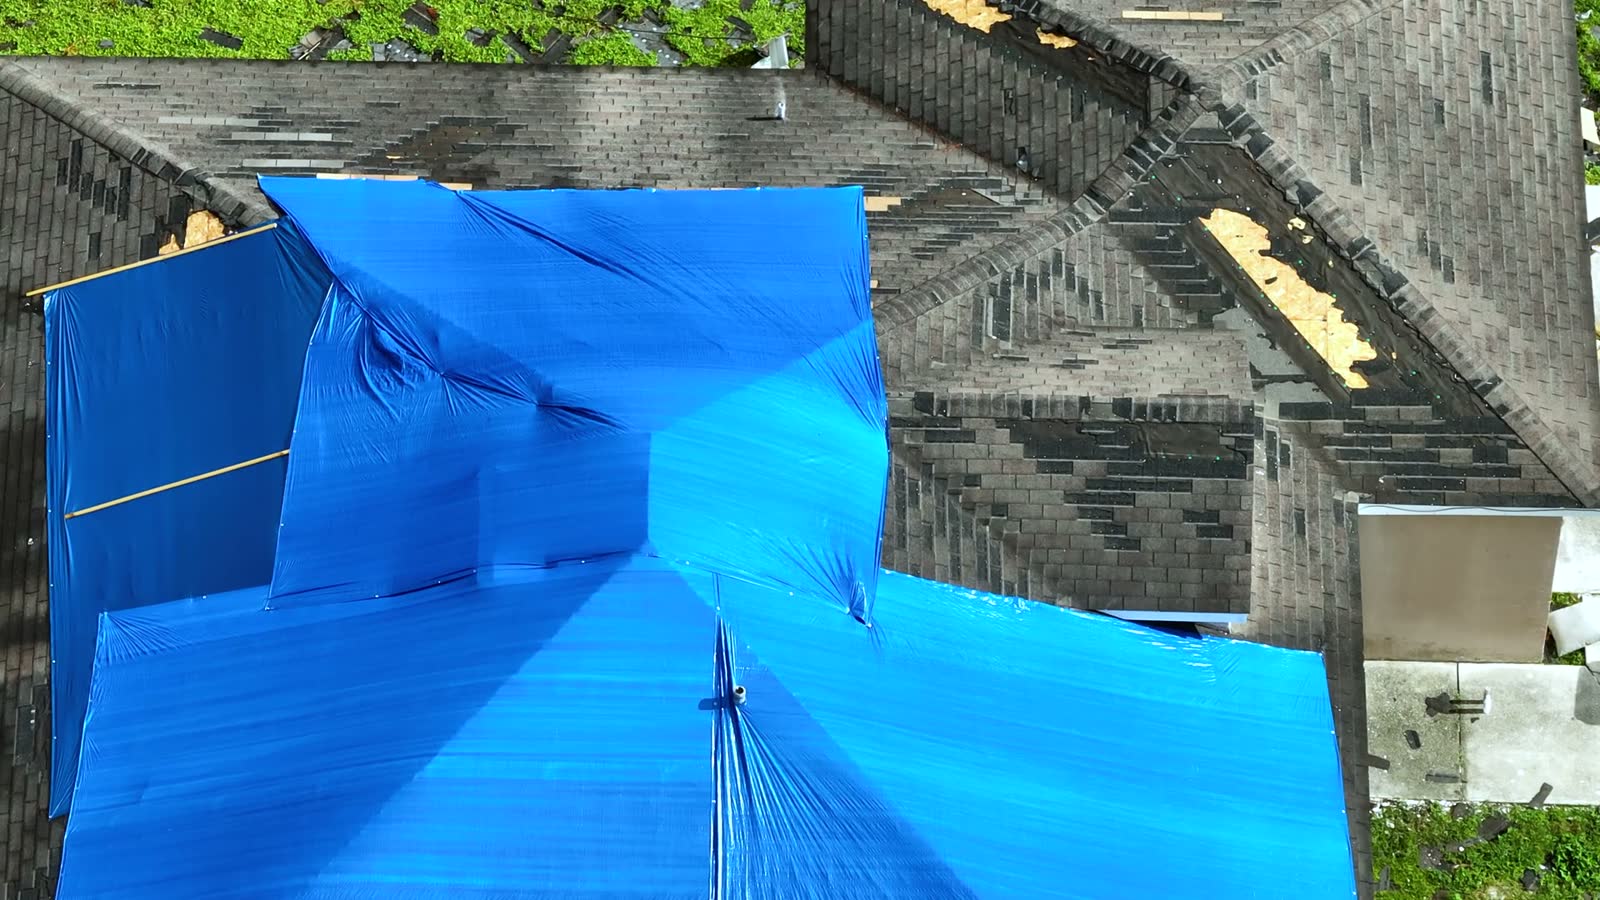
Photograph and video every damaged plane wide and close, with a tape or shingle in frame for scale, before any tear-off or temporary repair. Date-stamped originals beat a carrier’s months-old aerial capture.
Tie damage to the wind event
Directional creasing at the nail line, fresh tear edges, collateral damage on fences and soffits. That is the pattern that reads as one storm, not gradual age. Document the whole roof, not just the worst slope.
Write a specific scope
Exact work, materials, and price. No blank or vague scopes. A clear scope is both a better contract and better claim evidence for the homeowner.
Keep the paper trail
Contract, permits, manufacturer specs, and code-upgrade requirements (ordinance-or-law can add covered cost). Hand the homeowner a clean file they can give their adjuster.
The full method is in documenting roof damage, and the damage signatures by material are in the roofs library. When a carrier’s reason for denial is on the letter, the denials library breaks down each argument.
Stay on your side of the line
The fastest way to turn a good job into a legal problem is to drift from building the repair into handling the claim. Adjusting the claim is a separately licensed activity, and Florida’s assignment-of-benefits rules mean the paperwork you hand a customer carries real legal weight. Four things to avoid:
For how homeowners are told to vet contractors, the same checklist their adjuster will apply, see the contractor license-check guide.
A denied scope is a coverage dispute
When a carrier denies a covered scope, calls storm damage "wear and tear," or pays far below what the damage clearly costs, that is a coverage dispute between the homeowner and the carrier, not something a contractor can or should negotiate.
Your clean documentation is what makes that review productive: the dated photos, the specific scope, and the code-upgrade requirements are what the policyholder needs to contest the denial.
For contractors, FAQ
Can a contractor negotiate the insurance claim for the homeowner?
No. Adjusting a claim (negotiating the payout, advising on coverage, representing the policyholder to the carrier) is a licensed activity separate from contracting in both Florida and South Carolina. A contractor scopes and performs the repair. Crossing into claim handling creates liability and, in Florida, runs into the restrictions on assignment-of-benefits agreements. When the claim itself is disputed, the homeowner needs a public adjuster or an attorney.
What changed with assignment of benefits (AOB) in Florida?
Florida first regulated AOBs under Fla. Stat. § 627.7152 (notice, itemized estimate, and other requirements) and later reforms prohibited post-loss AOBs under property policies issued on or after January 1, 2023 (§ 627.7152(13)). An AOB transfers the policyholder’s rights under the policy to the contractor, which carries significant legal consequences for both sides. Do not use one without legal review of the current law and the specific form. Not legal advice.
How do I document damage so the claim actually gets paid?
Photograph and video every damaged plane wide and close, with a scale reference, before any tear-off or temporary repair. Capture the directional wind pattern and any collateral damage on fences, screens, and soffits. Keep the contract, permits, and manufacturer and code-upgrade documentation. Our roof-documentation guide covers the plane-by-plane method that survives a carrier’s aerial-photo challenge.
When should I point a homeowner to an attorney?
When the carrier denies a covered scope, attributes the damage to wear and tear rather than the storm, pays far below the documented scope, or delays past the deadlines. Those are coverage and bad-faith disputes, not scope negotiations. The homeowner can request a free case review.
- Fla. Stat. § 627.7152, assignment agreements ↗, Florida’s AOB requirements and restrictions for property-insurance claims.
- Florida DBPR, construction license search ↗, Verify a contractor license class and status (Certified vs. Registered).
- South Carolina LLR ↗, Residential Builders Commission and contractor license lookup.
- Fla. Stat. § 624.155, civil remedy (bad faith) ↗, The statutory path when a carrier’s handling crosses into bad faith.
Not legal advice; consult an attorney about your specific claim. Confirm the current law before using an assignment of benefits or advising a customer on a claim.
 HURRICANELAW.PRO
A comprehensive property-insurance claim resource for policyholders: denied and underpaid claims, coverage and bad-faith law, storm dossiers, carrier profiles, city guides, and the complete claims playbook. Florida and South Carolina.
▸ SEE THE FULL SITE MAP → ▸ KNOWLEDGE MAP: EVERY ENTITY AND SOURCE →Mount Pleasant, SC 29464
Coverage summaries, policy-language quotations, dollar figures, deadlines, and chart examples throughout this site are general information based on typical or standard policy forms and are illustrative only: they are not a quote, a guarantee of coverage, or a promise of any outcome. Every insurance policy is different: your own policy, endorsements, and state law control, so read your policy and confirm current statutes. Weather imagery courtesy of NOAA, the National Hurricane Center, and the National Weather Service. Nothing on this site is legal advice; consult an attorney about your specific claim.
HurricaneLaw.Pro is attorney advertising paid for by Halversen Law, LLC. Responsible attorney: Brent Halversen, 496 Bramson Court, Suite 100, Mount Pleasant, SC 29464. Operated by LARGE LLC, which is not a law firm. Nothing on this site is legal advice.
Halversen Law pays for this advertisement. It is a property-insurance law firm licensed in South Carolina and Florida and reviews every case-review submission.