Every roof fails differently, and gets denied differently
The denial argument you'll face is largely determined by what's on your roof. Find yours.
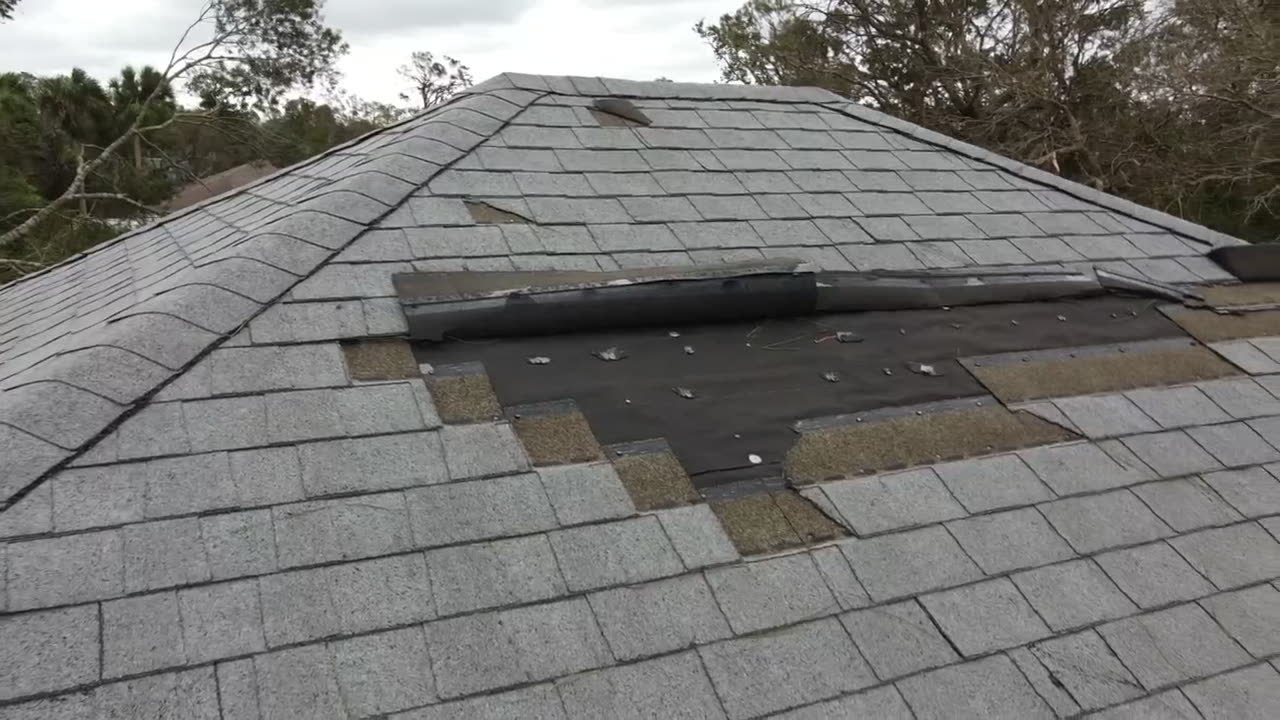
Why was my roof insurance claim denied?
Four reasons carry most roof denials: the carrier calls the damage wear and tear, calls it cosmetic, says the repair falls under your deductible, or says notice was late. Each is an opinion written by an adjuster or engineer, and each is rebuttable with dated photos, storm data, and an independent inspection.
| Wear and tear | The most common denial: age blamed for storm damage. Rebutted with storm data and failure-mode evidence. |
|---|---|
| Cosmetic only | Dents or granule loss called appearance-only. Function, not looks, is the coverage test. |
| Under deductible | A low scope keeps the estimate below the deductible. Contest the scope, not the price. |
| Late notice | Florida sets a 1-year notice window for a new or reopened claim under Fla. Stat. 627.70132. |
The 7 denial reasons, ranked by strength
Every roof denial letter cites a policy provision, but the provisions cluster into seven recurring arguments. Knowing which one you're facing tells you how hard to push. Some are legitimate coverage positions, others are negotiating postures dressed up as coverage positions.
Wear and tear / age
OFTEN FAILSThe most common denial and the most beatable. Age doesn't cause shingle creasing, uplifted tabs, or fastener pull-through in a wind pattern. Storm-consistent damage patterns rebut it.
Pre-existing damage
OFTEN FAILSRequires the insurer to prove your roof's condition before the storm. Historical aerial imagery and prior inspection reports usually settle this in the policyholder's favor.
Cosmetic damage only
OFTEN FAILSSome policies carry cosmetic-exclusion endorsements for metal roofs. If yours doesn't, 'cosmetic' is an opinion, not a policy term, and dents that break coating aren't cosmetic.
Below the deductible
FACT-SPECIFICA scoping dispute wearing a denial's clothes. The question is whether the adjuster measured the full scope (decking, underlayment, flashing, code upgrades), not just visible shingles.
Late notice
FACT-SPECIFICBoth FL and SC require prompt notice, but late notice only bars the claim if the insurer proves prejudice from the delay. Damage discovered months later is common and often still viable.
Excluded peril (flood/surge)
OFTEN HOLDSIf water rose into the home, wind policies genuinely exclude it. The fight is causation: wind-driven rain through a breached roof is covered even when surge is not.
Neglect / failure to mitigate
OFTEN HOLDSYou must make reasonable temporary repairs after a loss. Keep tarp receipts and dated photos. Mitigation done and documented defeats this outright.
Decoding your denial letter
A denial letter must do three things: identify the specific policy language relied on, state the factual basis for applying it, and tell you your rights. Read it with a highlighter and mark exactly three items: the cited exclusion, the inspection it relies on, and the date. Everything in your response flows from those three. The anatomy of a denial letter breaks down each clause.
If the letter cites "wear and tear" without an inspection report attached or referenced, that's your first demand: the complete adjuster file, including photos and any engineering opinions. In Florida you're entitled to the adjuster's report on request; in South Carolina the request itself creates a paper trail that matters later.
Rebuilding the evidence
Denials get reversed with evidence, not arguments. Your job is to establish two facts independently of the insurer: the roof's condition before the storm, and the wind speeds at your address during it.
The engineer-report trap
When a carrier sends an engineer, understand what you're getting: an expert retained and paid by the party that benefits from a denial. Their reports are often boilerplate: the same "uplift not observed, damage consistent with age" language appears across thousands of claims. Here is how to rebut an engineer report.
You are entitled to your own expert. A licensed engineer's rebuttal report commonly runs on the order of $600-$1,500 (fees vary by market and scope), typically a fraction of a full roof replacement, and it is often the single most effective document in an appraisal or suit. Get it before signing anything.
The roof is only half the evidence. What the water did on its way down (the attic deck, the insulation, the ceilings) is what turns a "cosmetic" denial into a covered structural claim. Photos 07-09 of the protocol below live in these rooms.
The 10-photo protocol
CHECKLIST · SAVES ON THIS DEVICETen frames, shot in this order, cover every argument in a roof denial. Check them off as you shoot; progress saves on this device. Your phone is the best claim tool you own.
Your 4 escalation paths
Internal appeal
A written demand for reconsideration with your new evidence attached. Free, fast, and creates the record every later step relies on.
State DOI complaint
Florida DFS and SC DOI complaints force a written carrier response and get claims re-examined by someone new. Surprisingly effective on process failures.
Appraisal
A policy-built process where each side's appraiser and a neutral umpire set the loss amount. Binds the number, not coverage. The right tool for lowball disputes.
Litigation
For denials of coverage itself, or bad-faith conduct. Contingency representation means no upfront cost; FL and SC both allow fee recovery in the right cases.
Deadlines in FL & SC
Deadlines shown are general rules as of July 2026 and have exceptions: supplemental claims, reopened claims, and policy-specific notice provisions can shorten them. Verify against your policy and current statute.
A roof denial is an argument, and arguments answer to evidence.
A denial letter is the carrier's opening position, not the last word. Most roof denials run on a short list of arguments: wear and tear, matching, cosmetic damage, and depreciation. Read it for the exact exclusion and inspection it cites, then rebuild the record: dated photos, a roofer's or engineer's condition report, and the wind data for your address. Photograph before you tarp and keep every receipt.
Deadlines run from the dates on that letter. Florida allows 1 year to notice a hurricane claim and 18 months for a supplemental; South Carolina runs on prompt notice. Meet the window and a denial becomes an appeal, an appraisal, or a suit you can win. A public adjuster can price the loss on your side. Check the filing deadlines, then use the free review below.
Think the roof denial is wrong? Find out.
Upload the denial letter, the adjuster estimate, and your photos. You'll get a straight answer on whether the denial argument holds, and what the escalation path looks like if it doesn't.
Roofer database
Licensed roofing contractors, mapped by city.
Open →Public adjusters
Policyholder-side adjusters, listed by state and city.
Open →Documenting roof damage
The full guide: what adjusters look for, plane by plane.
Open →Photo protocol for the whole claim
The property-wide version: contents, water lines, ALE receipts.
Open →Deadline countdown
Enter your storm and state; get every filing deadline on a timer.
Open →FORTIFIED Home standard ↗
IBHS construction standard for wind-rated roofs. FL and SC insurers offer premium credits for certification.
My Safe Florida Home ↗
State program: free wind-mitigation inspections and matching grants for roof hardening.
SC Safe Home ↗
South Carolina grant program for wind-resistant roof retrofits.
Florida Office of Insurance Regulation ↗
Carrier complaint data, market conduct reports, and insurer financials.
Wind safety ↗
How straight-line and tropical winds damage structures.
Disaster & failure studies ↗
Post-storm engineering investigations of how buildings actually fail.

 HURRICANELAW.PRO
A comprehensive property-insurance claim resource for policyholders: denied and underpaid claims, coverage and bad-faith law, storm dossiers, carrier profiles, city guides, and the complete claims playbook. Florida and South Carolina.
▸ SEE THE FULL SITE MAP →Coverage summaries, policy-language quotations, dollar figures, deadlines, and chart examples throughout this site are general information based on typical or standard policy forms and are illustrative only: they are not a quote, a guarantee of coverage, or a promise of any outcome. Every insurance policy is different: your own policy, endorsements, and state law control, so read your policy and confirm current statutes. Weather imagery courtesy of NOAA, the National Hurricane Center, and the National Weather Service. Legal services are provided by Halversen Law. Nothing on this site is legal advice; consult an attorney about your specific claim.
Legal matters are handled by Halversen Law, a law firm licensed in Florida and South Carolina.