
ACTIVE STORM TRACK →
PROPERTY-INSURANCE CLAIM HELP FL CITIESSC CITIESGUIDESTATESNEWSSITE MAPABOUT
HurricaneLaw.Pro, Florida and South Carolina property insurance claim resource HURRICANELAW.PRO
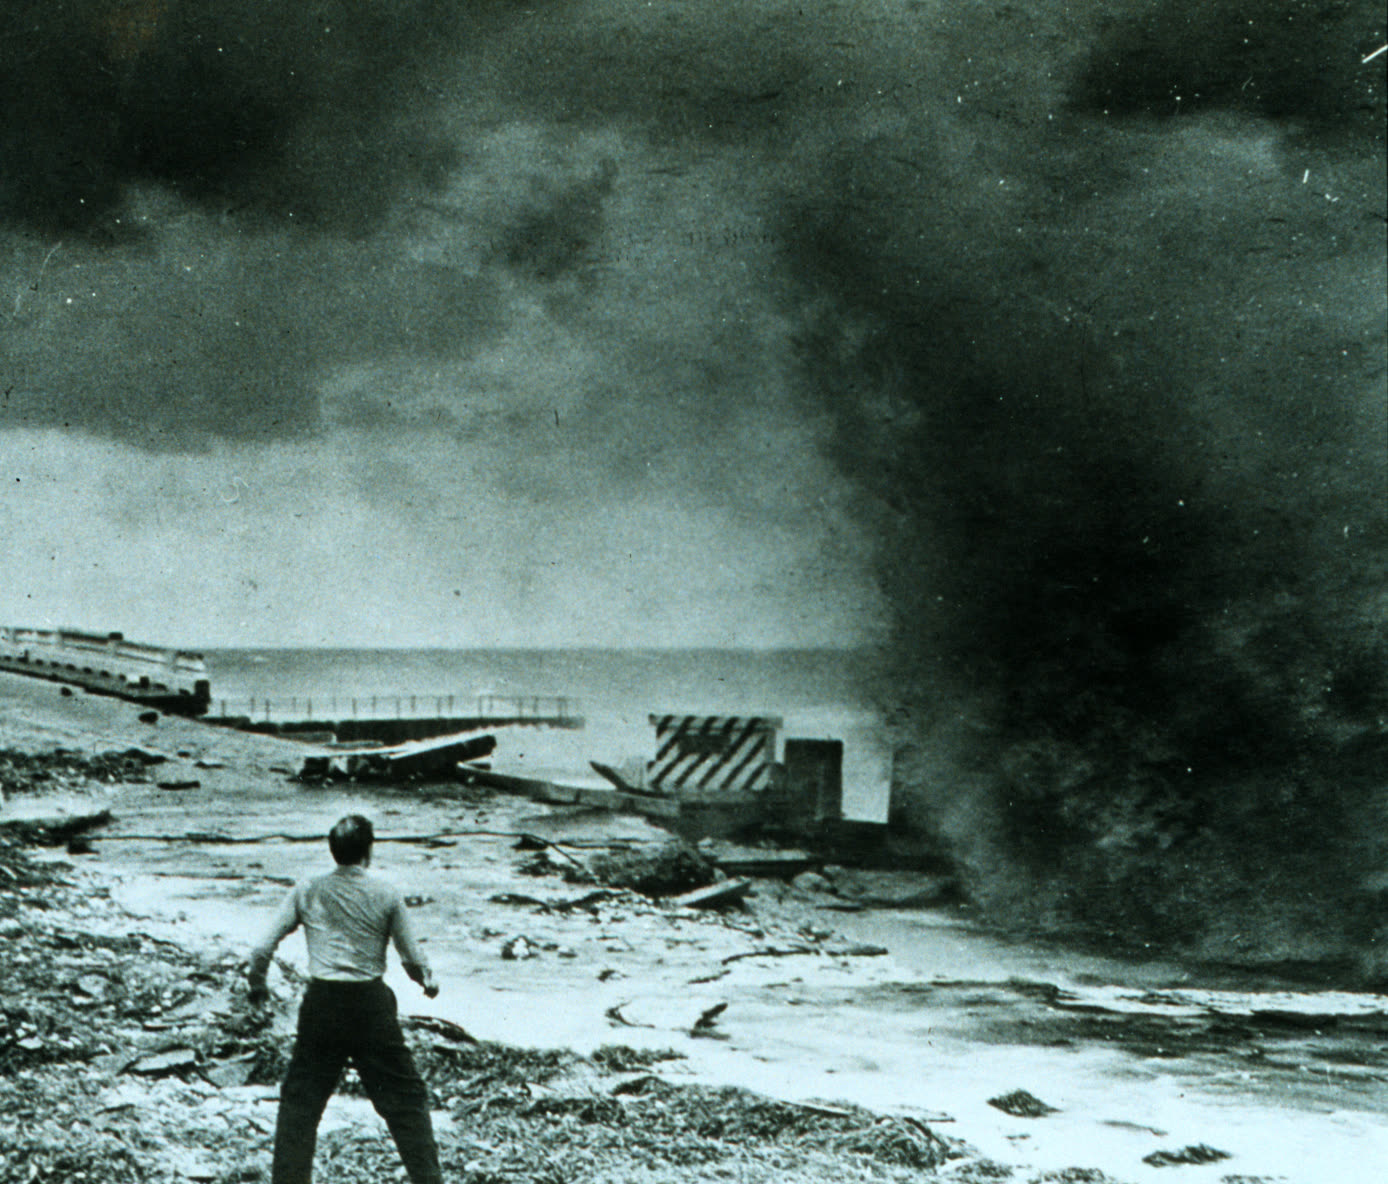
A wave driven by the September 1947 hurricane smashes a seawall north of Miami Beach
STORM ARCHIVE / 1947 LANDFALL 26.3°N 80.1°W
CAT 4 FL · 1947 · ~155 mph

Fort Lauderdale Hurricane

Landfall: Fort Lauderdale / Pompano Beach, FL · 1947-09-17. Its floods drowned 2,000+ square miles of South Florida for months and pushed Congress to build the Central & Southern Florida Flood Control Project, engineering in place of the flood insurance that didn't exist

NOAA Photo Library
AT LANDFALL
CAT 4
PEAK WIND
~155 mph
PRESSURE
943 mb
STORM SURGE
21.6 ft lake tide
DAMAGE
~$110M (1947)
DEATHS
51
01 THE PATH

Where it hit, start to finish

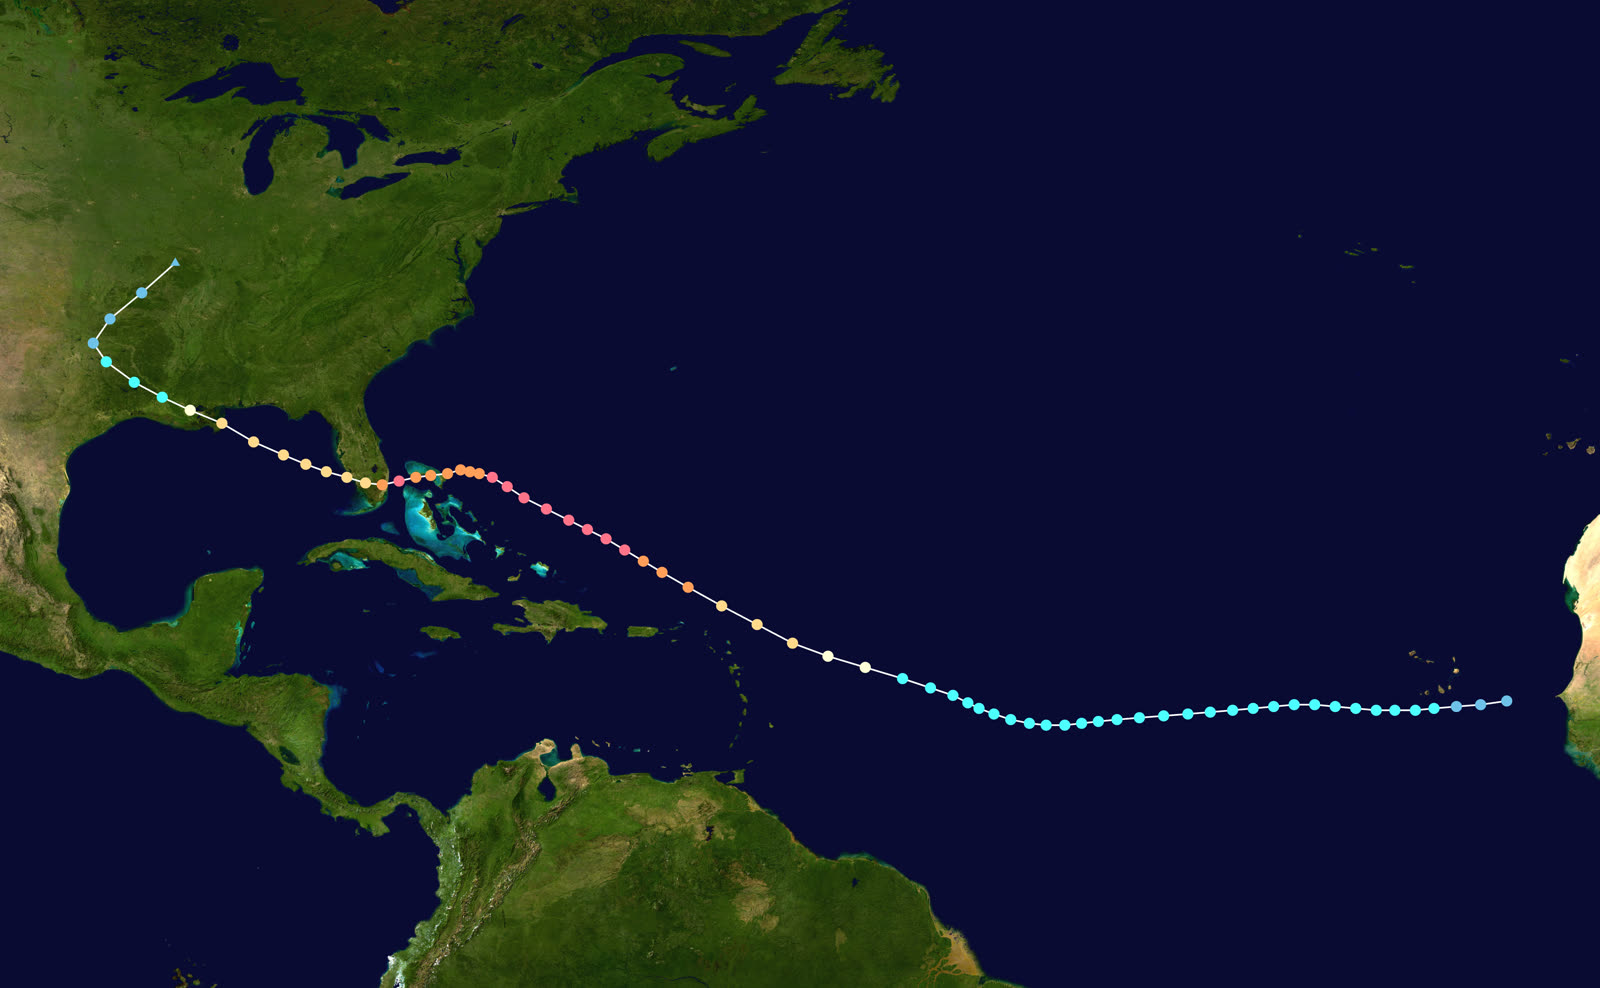
TRACK · FORT LAUDERDALE HURRICANENOAA / NHC (best-track data)
Best track of the 1947 Fort Lauderdale hurricane, September 4-21, 1947
Central Atlantic
CAPE VERDE GIANT

Formed September 4, 1947, in the eastern Atlantic and peaked near 155 mph, a massive circulation with hurricane-force winds reaching 120 miles from the center.

Fort Lauderdale / Pompano Beach
CAT 4 LANDFALL

Landfall September 17 with ~130-mph sustained winds and a 943-mb pressure. The Hillsboro Lighthouse area took the core; wind damage ran from Miami to Palm Beach.

Lake Okeechobee / Everglades
THE FLOOD THAT WOULDN'T DRAIN

Rain up to 10+ inches fell on ground already soaked by a wet summer; lake tides hit 21.6 ft at Clewiston. More than 2,000 square miles south of the lake went under 6-7 ft of water, and stayed under for months.

Gulf of Mexico
SECOND LANDFALL, LOUISIANA

The hurricane crossed into the Gulf near Everglades City, then struck St. Bernard Parish, Louisiana on September 19 as a Category 2, flooding metro New Orleans; 12 died in Louisiana and 22 in Mississippi.

Texas
DISSIPATION

The system weakened inland and dissipated over north Texas on September 21. A second hurricane in October re-flooded South Florida and sealed the case for federal flood control.

02 THE RECORD IN IMAGES
ALL IMAGERY U.S. GOV / PUBLIC DOMAIN
SURGE Public domain (1947 archival photo)
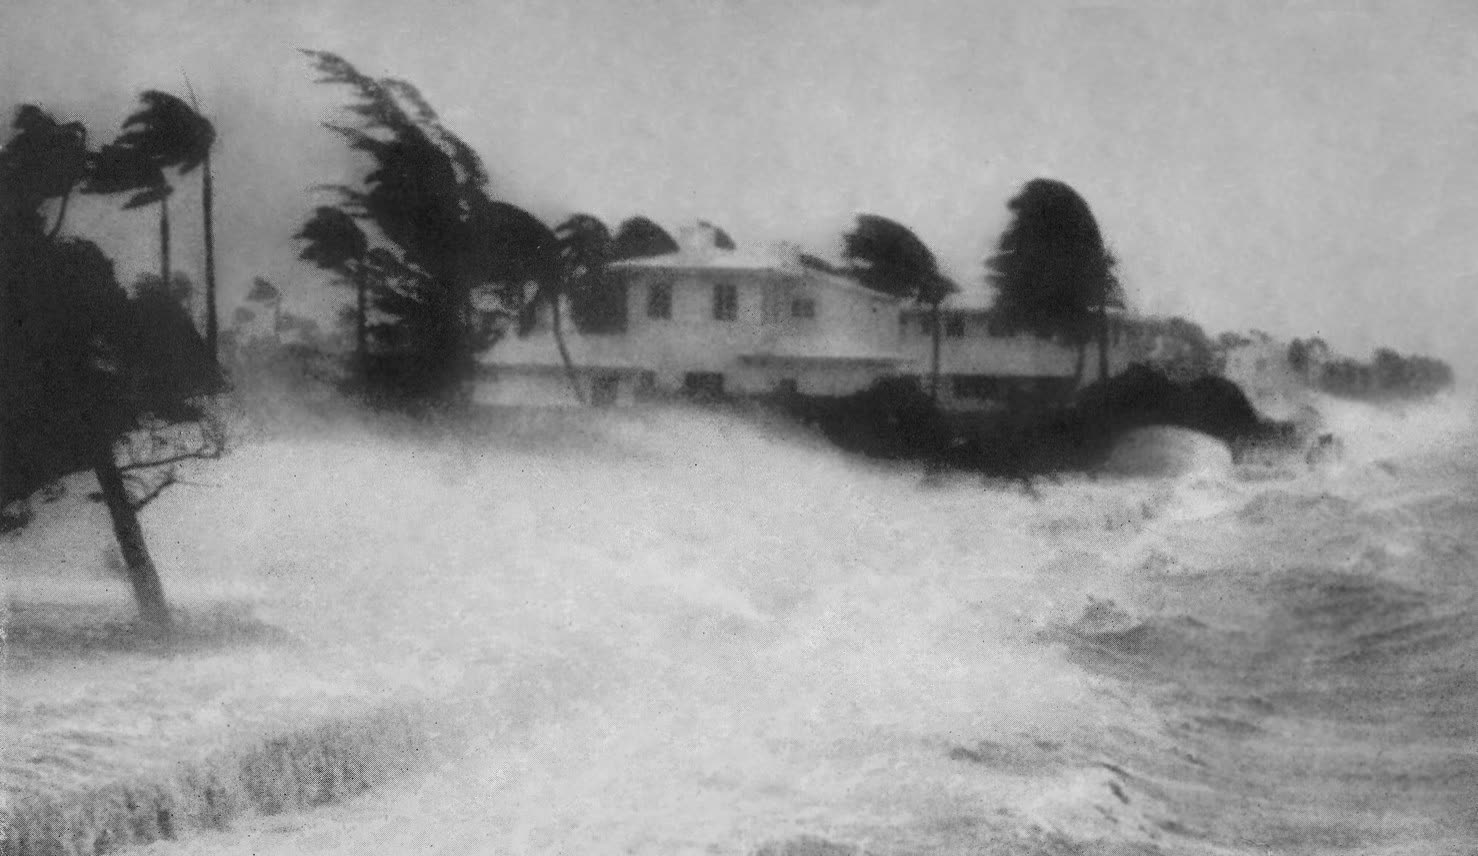
Storm surge over North Bay Village, Miami, September 17, 1947
FLOOD U.S. Army Corps of Engineers
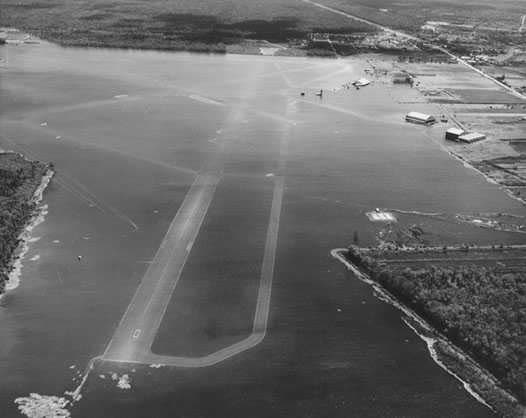
Moisant Airport, New Orleans, under floodwater after the storm's second landfall, September 19, 1947

The storm

The 1947 Fort Lauderdale hurricane formed in the eastern Atlantic on September 4 and grew into one of the largest hurricanes of its era, hurricane-force winds extended 120 miles from the center, peaking near 155 mph over open water.

It came ashore on September 17 between Fort Lauderdale and Pompano Beach as a Category 4, with sustained winds around 130 mph and a minimum pressure of 943 mb. Because of the storm's size, damaging winds covered the entire lower east coast from Miami to Palm Beach. The hurricane crossed the peninsula and the Everglades, entered the Gulf, and made a second landfall in St. Bernard Parish, Louisiana on September 19 as a Category 2, pushing a 15-foot surge into the Gulf Coast and flooding parts of metro New Orleans before dissipating over Texas on September 21.
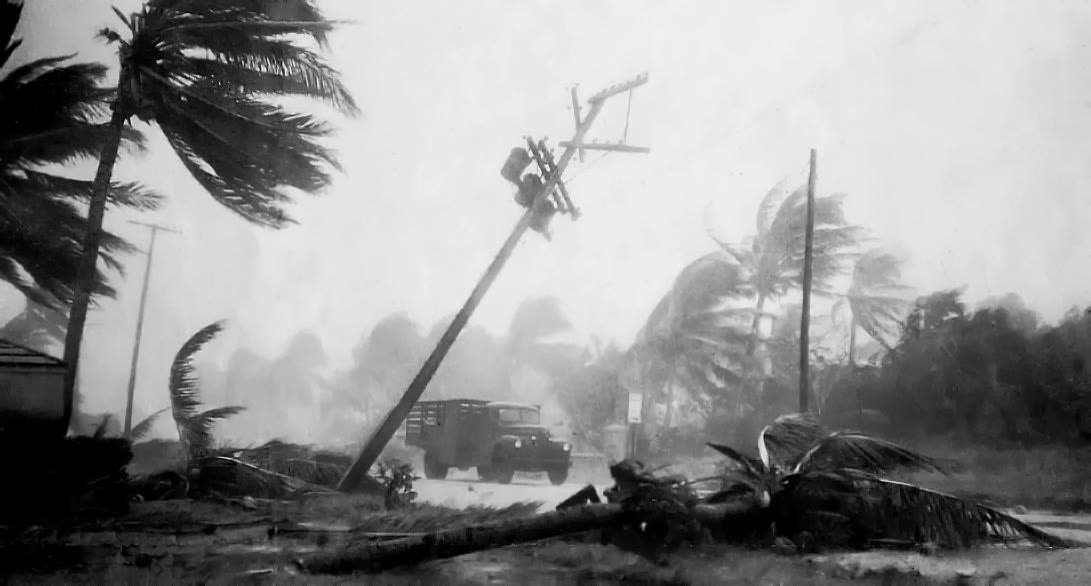
Downed trees and power poles in the Fort Lauderdale area after landfall
Downed trees and power poles in the Fort Lauderdale area after landfall Public domain (1947 archival photo)

The damage

Deaths were comparatively low, 51 total, 17 of them in Florida, a credit to Weather Bureau warnings that had improved beyond the 1926/1928 era. Property was another matter: roughly $110 million in 1947 dollars across the storm's path.

Wind wrecked roofs, power lines, and crops along the Gold Coast, but water wrote the storm's history. September 1947 rain fell on a South Florida already saturated by one of the wettest summers on record; the St. Lucie Lock gauged 10.12 inches from the storm, and Lake Okeechobee's wind tide reached 21.6 feet at Clewiston. More than 2,000 square miles south of the lake flooded six to seven feet deep. Suburban Broward and Dade neighborhoods, built on drained Everglades muck during the postwar boom, held standing water for months. When a second hurricane crossed the region in October 1947, the floodwater simply had nowhere to go. Agricultural losses alone ran about $59 million.
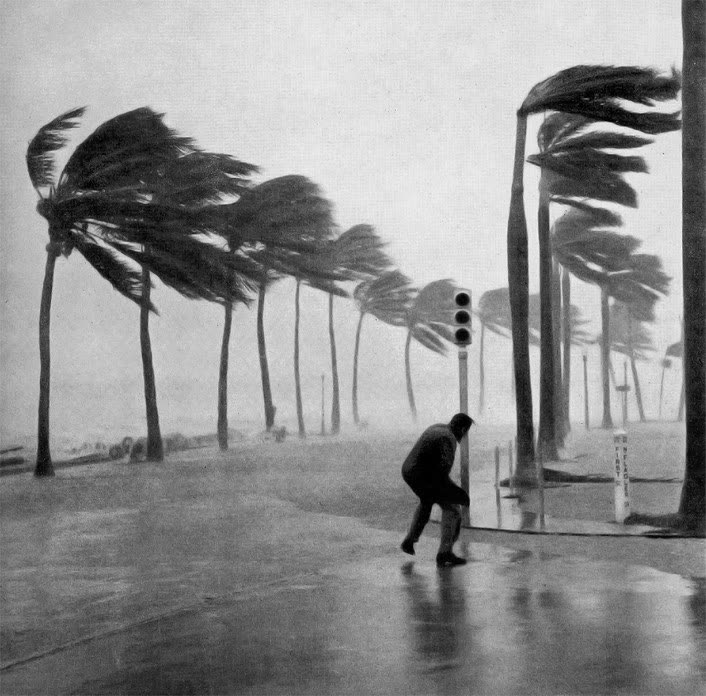
A man leans into the hurricane's winds in South Florida, a system with hurricane-force winds extending 120 miles out
A man leans into the hurricane's winds in South Florida, a system with hurricane-force winds extending 120 miles out Public domain (1947 archival photo)

The insurance aftermath

In 1947 a Florida homeowner's protection was a fire policy plus, at best, an "extended coverage" windstorm endorsement, the package homeowners policy did not yet exist, and no flood insurance market existed at all. Wind losses on the coast were insurable and paid; the months-long inland flood was almost entirely uninsured, falling on owners, farm operators, and federal relief.

The policy response was the largest of its kind in American history. With flooded suburbs on the front pages, Florida's congressional delegation moved fast: in 1948 Congress authorized the Central & Southern Florida Project for Flood Control and Other Purposes, levees, canals, pump stations, and water storage areas across 16,000 square miles, the biggest civil-works program in the country. Florida created the Central and Southern Florida Flood Control District in 1949 to run it; that agency is today's South Florida Water Management District. In Louisiana, the same storm produced congressional approval of the Lake Pontchartrain and Vicinity levee project, the system whose successors failed in Katrina.

For insurers, 1947 reinforced the line the industry had drawn after 1926 and 1928: wind yes, rising water no. The federal government accepted the flood peril as a public-works problem, and that division, carrier pays wind, government manages water, held until the NFIP arrived in 1968 and still defines every surge-versus-flood claim fight in Florida.
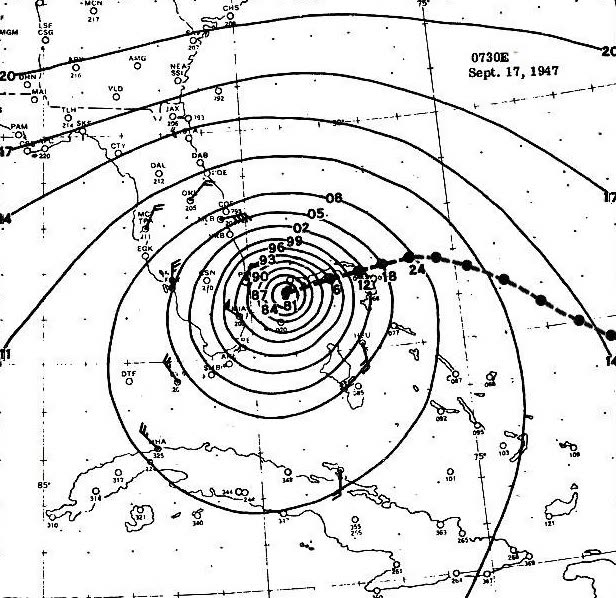
U.S. Weather Bureau analysis of the hurricane at Florida landfall, September 17, 1947
U.S. Weather Bureau analysis of the hurricane at Florida landfall, September 17, 1947 NOAA / U.S. Weather Bureau

What policyholders learned

  • The wind/water line was drawn in this era. Wind endorsements paid; floodwater didn't. Eighty years later the same boundary decides Florida claims, flood requires its own policy.
  • Inland flooding is a hurricane peril. The worst 1947 losses were 40+ miles from the beach, in drained wetlands. Elevation and drainage history matter more than distance to the coast.
  • Back-to-back storms compound losses and disputes. The October 1947 storm re-flooded ground the September storm had saturated, allocation between events has been a claims argument ever since.
  • Flood-control projects create insurance blind spots. The C&SF Project made the floodplain developable; residents behind its canals came to treat flood cover as optional. The protection is real, but so is the residual risk.
  • Document rainfall damage separately from surge. Wind-driven rain through a damaged roof is a covered loss under most wind policies; rising water is not. The 1947 flood is the archetype of why the distinction pays.

Not legal advice; consult an attorney about your specific claim. Damage figures are nominal (not inflation-adjusted) unless noted.

AT LANDFALL · FORT LAUDERDALE HURRICANE · 1947
21.6 ft lake tide
OF STORM SURGE · CLEWISTON, LAKE OKEECHOBEE
REPRESENTATIVE FOOTAGE
03 THE FULL RECORD

Every official record of Fort Lauderdale Hurricane

Reports, imagery archives, flood data, and claims records, straight from the agencies.

FREE CASE REVIEW · NO FEE UNLESS YOU RECOVER
Fort Lauderdale Hurricane claim denied?
CALL SC · 843-542-0454CALL FL · 813-588-0164FREE CLAIM REVIEW
RELATED GUIDES
HurricaneLaw.Pro, Florida and South Carolina property insurance claim resource HURRICANELAW.PRO

A comprehensive property-insurance claim resource for policyholders: denied and underpaid claims, coverage and bad-faith law, storm dossiers, carrier profiles, city guides, and the complete claims playbook. Florida and South Carolina.

▸ SEE THE FULL SITE MAP →
STORM ALERTS SOURCED FROM NOAA / NHC
SOUTH CAROLINA
496 Bramson Court, Suite 100
Mount Pleasant, SC 29464
CALL OR TEXT
FLORIDA
CALL OR TEXT
CLAIMS 9
BAD FAITH 7
DENIAL FILINGS
HOW CLAIMS GET DENIED
DENIAL DOCUMENTS
DENIALS, ANSWERED 9
COVERAGE 13
COMMERCIAL 8
ROOFS 8
TREES 5
DIRECTORIES
STORMS 51
WEATHER
NEWS & SITE 22
STORM ARCHIVE, CITIES & NEWS
Most recent below. Every storm dossier, city resource, and article is on its hub (linked at each heading) or the grouped site map →. All 73 carriers and 95 public-adjuster firms are in the Directories column above.
STORM ARCHIVE · 51 →
Hurricane Debby 2024Hurricane Helene 2024Hurricane Milton 2024Hurricane Idalia 2023Hurricane Ian 2022Hurricane Nicole 2022Hurricane Ida 2021Hurricane Laura 2020 View all 51 →
FLORIDA CITY RESOURCES · 37 →
Boca RatonBradentonCape CoralClearwaterCrestviewDaytona BeachDestinDunedin View all 37 →
SOUTH CAROLINA CITY RESOURCES · 8 →
BeaufortCharlestonColumbiaFlorenceGreenvilleHilton Head IslandMount PleasantMyrtle Beach
NEWS & UPDATES · 22 →

Coverage summaries, policy-language quotations, dollar figures, deadlines, and chart examples throughout this site are general information based on typical or standard policy forms and are illustrative only: they are not a quote, a guarantee of coverage, or a promise of any outcome. Every insurance policy is different: your own policy, endorsements, and state law control, so read your policy and confirm current statutes. Weather imagery courtesy of NOAA, the National Hurricane Center, and the National Weather Service. Legal services are provided by Halversen Law. Nothing on this site is legal advice; consult an attorney about your specific claim.

PrivacyTermsDisclaimerAboutContact
This site is not legal advice, and it is not a substitute for an attorney. Anything legal needs a licensed lawyer reading your policy and your facts. We recommend Halversen Law: the free claim review is the fastest way to get real eyes on your claim.
© 2026 HURRICANELAW.PRO · ALL RIGHTS RESERVED 27.9°N 82.5°W · ATLANTIC BASIN MONITOR
LAW FIRM
Halversen Law LICENSED · FLORIDA & SOUTH CAROLINA

Legal matters are handled by Halversen Law, a law firm licensed in Florida and South Carolina.

FREE CASE REVIEW