
ACTIVE STORM TRACK →
PROPERTY-INSURANCE CLAIM HELP FL CITIESSC CITIESGUIDESTATESNEWSSITE MAPABOUT
HurricaneLaw.Pro, Florida and South Carolina property insurance claim resource HURRICANELAW.PRO
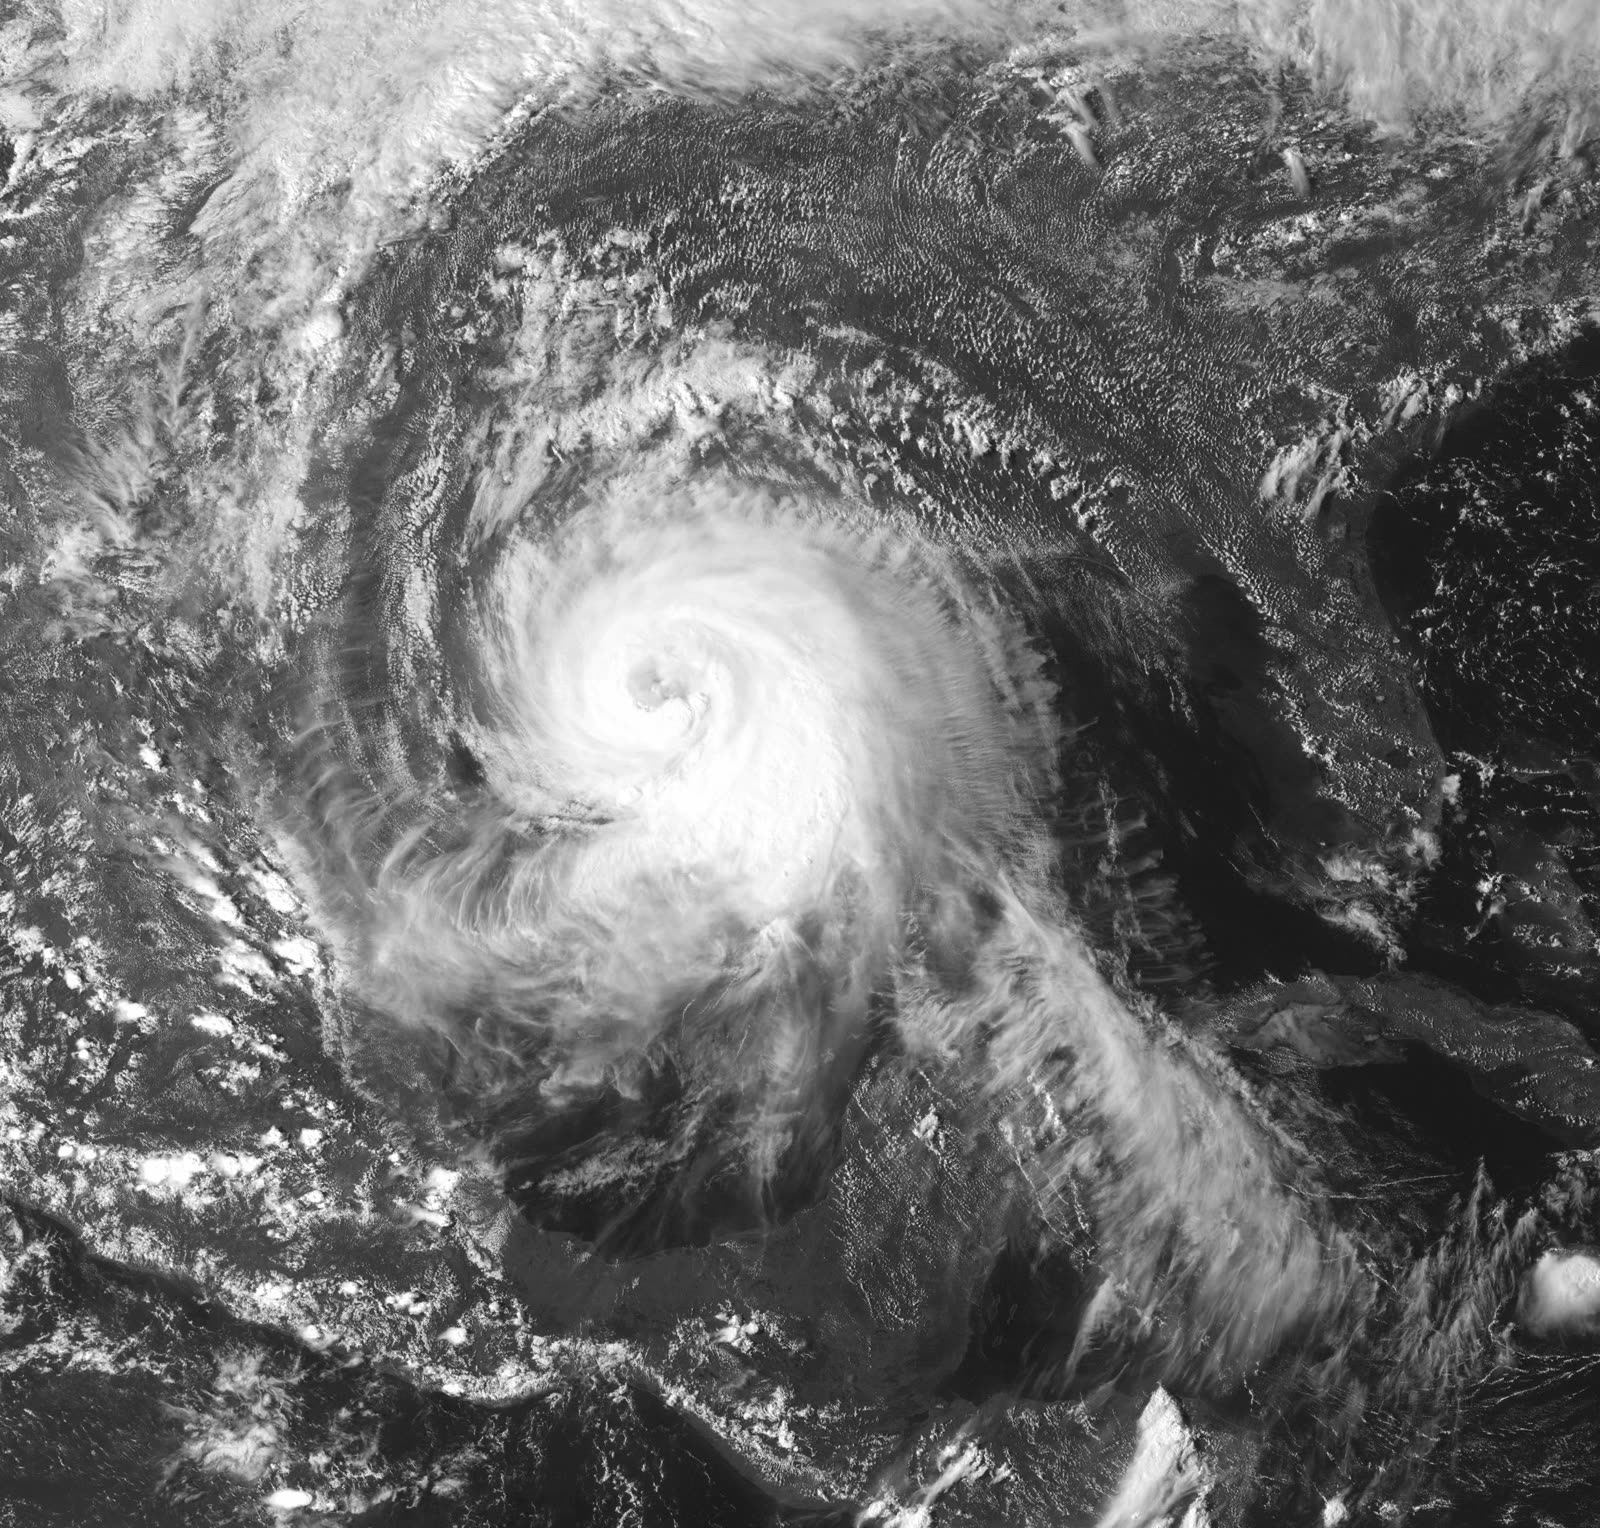
Ike filling the Gulf of Mexico on final approach to Galveston, September 12, 2008, a Category 2 with a wind field the size of a Category 5's
STORM ARCHIVE / 2008 LANDFALL 29.3°N 94.7°W
CAT 2 AT LANDFALL PEAK CAT 4 US · 2008 · 145 mph

Hurricane Ike

Landfall: Galveston, TX · 2008-09-13. TWIA paid $2.3B on ~93,000 Ike claims, then thousands of lawsuits nearly sank it, Texas rewrote windstorm-claim law in 2011

NOAA / NASA
AT LANDFALL
CAT 2
PEAK INTENSITY
CAT 4 · 145 mph
PRESSURE
950 mb (landfall)
STORM SURGE
15-20 ft
DAMAGE
$30B
DEATHS
112
01 THE PATH

Where it hit, start to finish

TRACK · HURRICANE IKENOAA / NHC (best-track data)
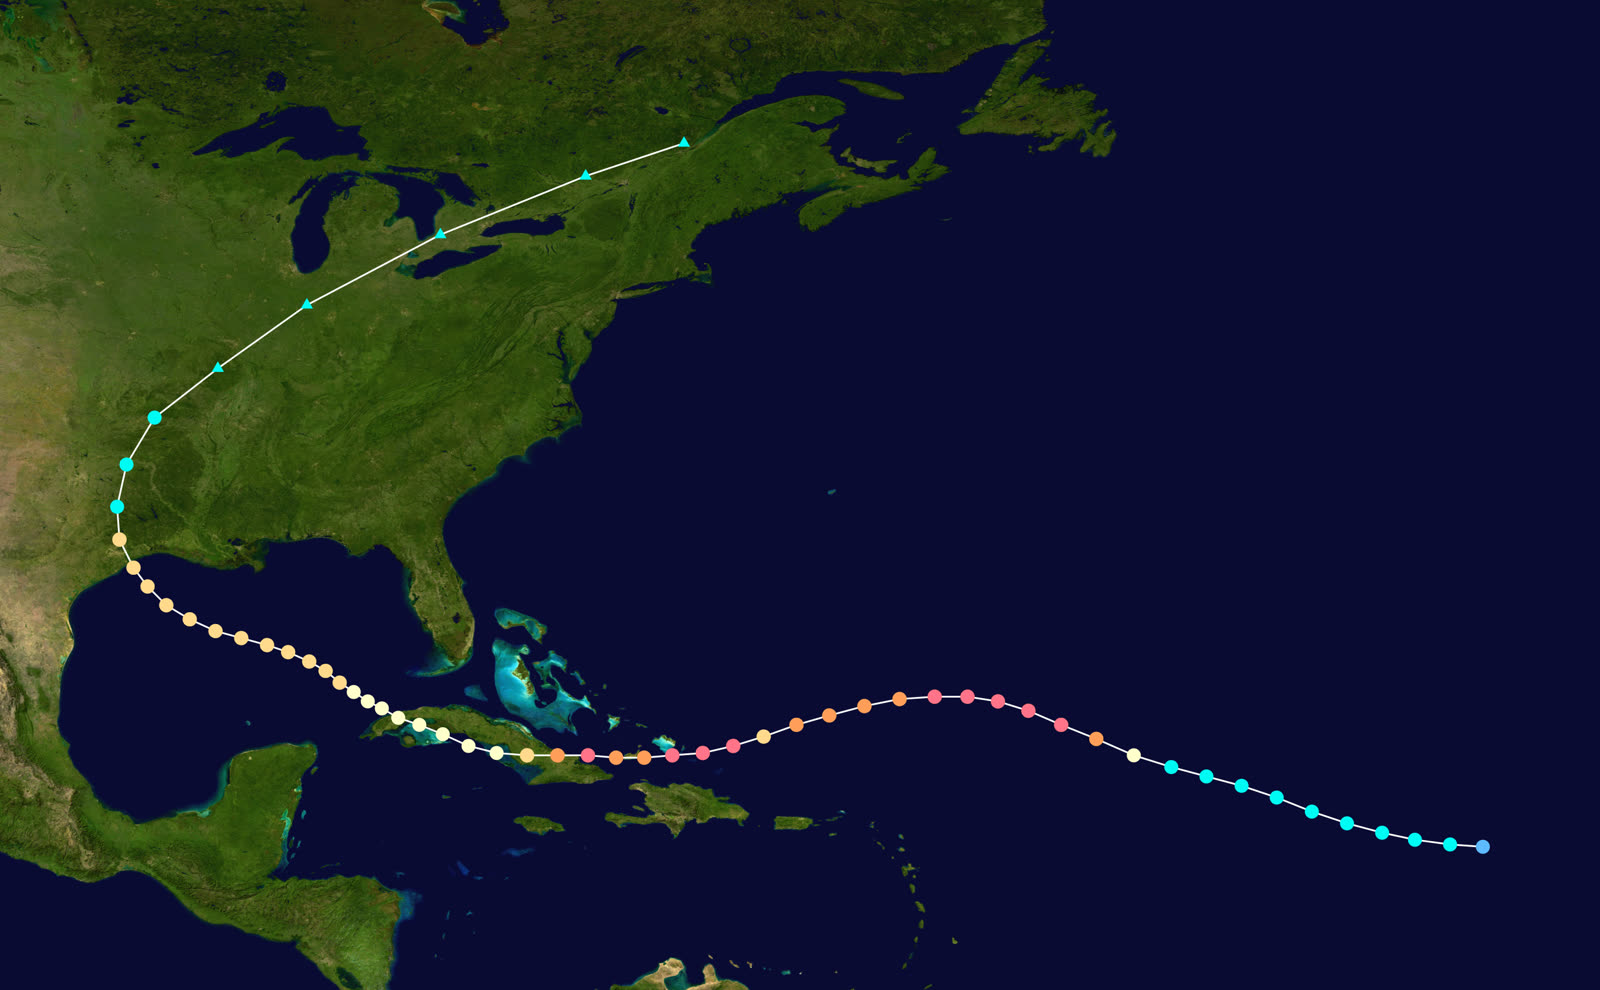
Best track and Saffir-Simpson intensity of Hurricane Ike, September 1-14, 2008
Open Atlantic / Turks and Caicos
CAT 4 PEAK, 145 MPH

Ike peaked at 145 mph on September 4, then raked the Turks and Caicos and Great Inagua at Category 4 strength.

Cuba
TWO CUBAN LANDFALLS

Ike struck eastern Cuba as a Category 4 on September 8 and crossed the island's western end September 9, weakening but spreading its wind field enormously.

Gulf of Mexico
A CAT 2 WITH CAT 5 ENERGY

Over the Gulf, Ike never regained major-hurricane winds but grew into one of the largest hurricanes on record, tropical-storm-force winds spanned over 400 miles, driving surge far beyond what its category implied.

Bolivar Peninsula, TX
15-20 FT SURGE, GILCHRIST ERASED

Surge began flooding the coast a full day before landfall, cutting off escape routes. In Gilchrist, nearly every structure was destroyed; whole neighborhoods on Bolivar were reduced to slabs and pilings.

Galveston, TX
CAT 2 LANDFALL, 110 MPH

The eye crossed Galveston Island at 2:10 a.m. CDT September 13 with 110 mph winds and a 950 mb pressure. Surge overtopped the island behind the seawall and flooded thousands of structures; downtown Houston high-rises lost windows and 2 million+ customers lost power.

Ohio Valley
INLAND WINDSTORM

Ike's remnants merged with a front and delivered hurricane-force gusts as far north as Ohio, adding billions in inland wind losses. U.S. total: about $30 billion in damage and 112 deaths.

02 THE RECORD IN IMAGES
ALL IMAGERY U.S. GOV / PUBLIC DOMAIN
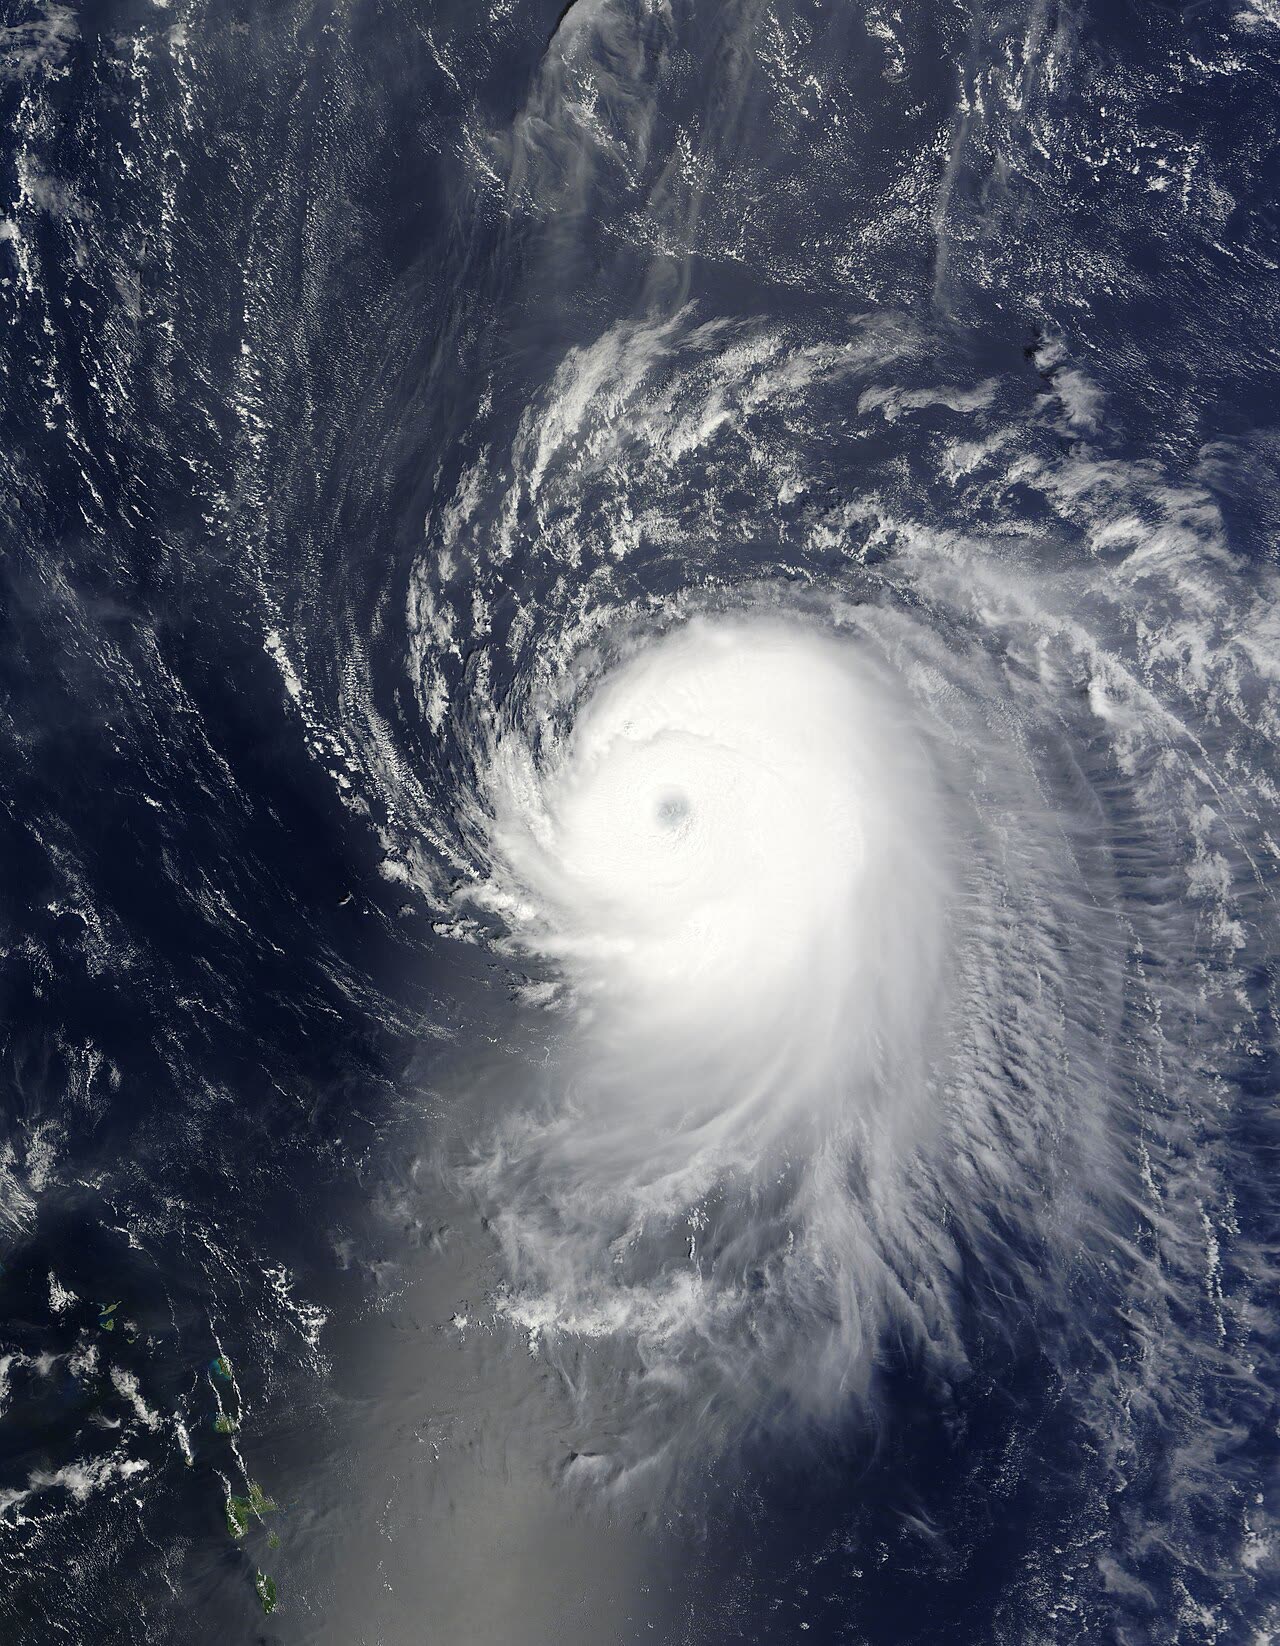
SATELLITE NOAA / NASA
Ike at Category 4 peak intensity, 145 mph, in the open Atlantic, September 4, 2008
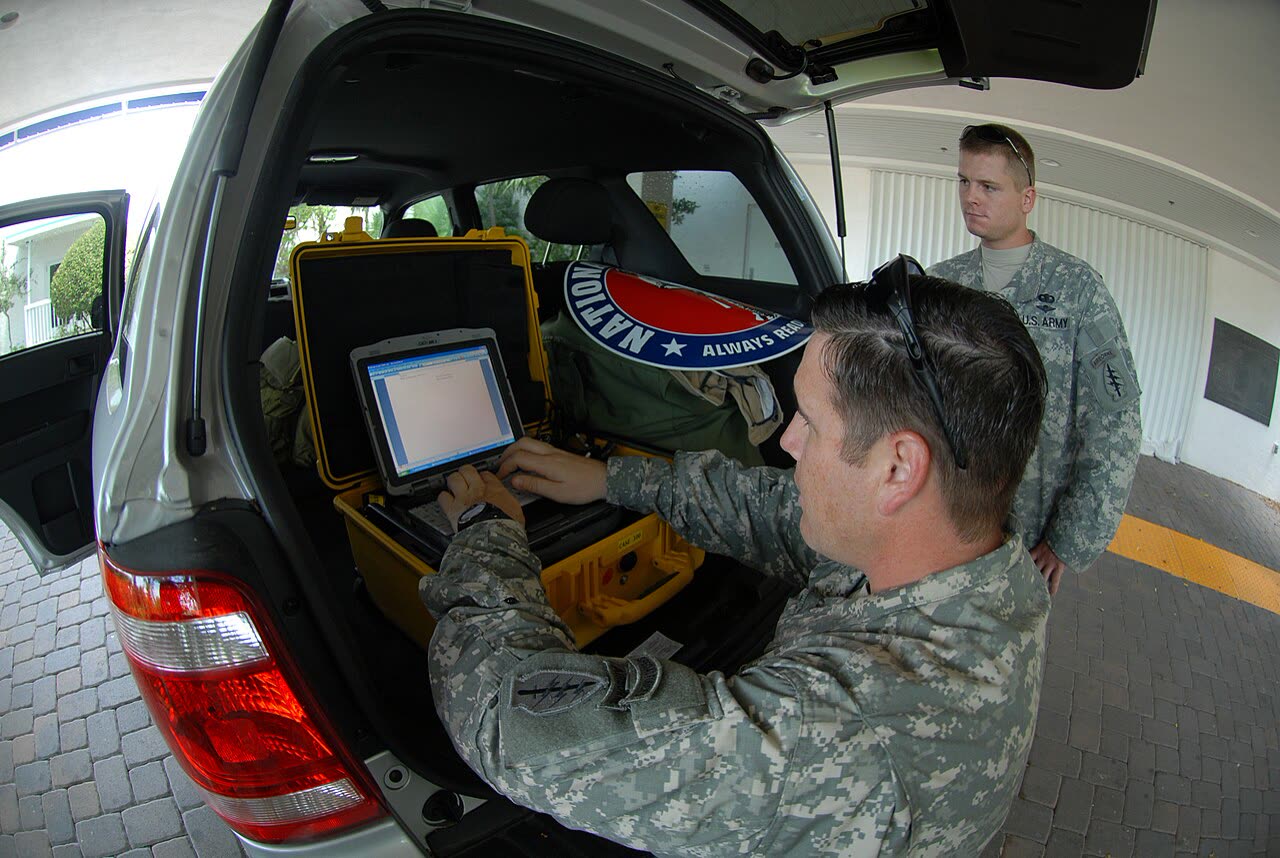
DAMAGE U.S. Army
U.S. Army troops moving through storm debris in Galveston after landfall
MAP NOAA / WPC
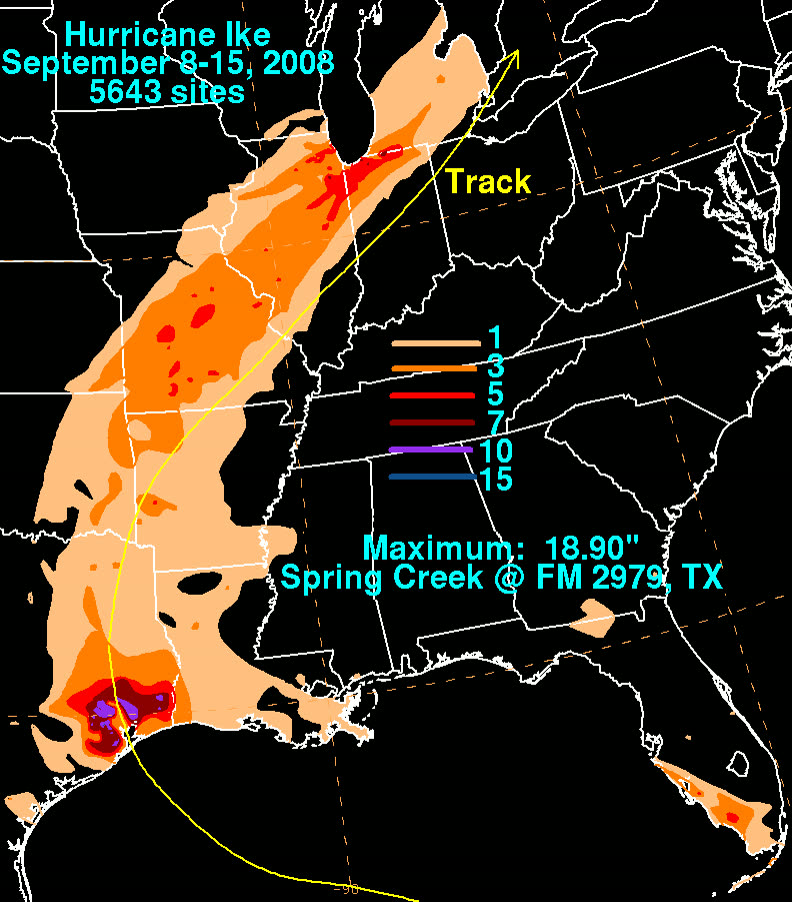
Storm-total rainfall from Ike from the Gulf coast through the Ohio Valley

The storm

Ike peaked as a 145 mph Category 4 in the open Atlantic on September 4, 2008, battered the Turks and Caicos and Great Inagua, then struck Cuba twice. What emerged into the Gulf was a Category 2 by wind speed with the footprint of a far stronger storm: tropical-storm-force winds extending more than 200 miles from the center, among the largest wind fields ever measured in the Atlantic basin.

That size, not the category, wrote the story. Surge driven by Ike's integrated wind energy began inundating the upper Texas coast a full day before the center arrived. The eye crossed Galveston Island at 2:10 a.m. CDT on September 13, 110 mph, 950 mb. Surge ran 15 to 20 feet on the Bolivar Peninsula and 10 to 13 feet through Galveston Bay. Remnant Ike then merged with a front and delivered hurricane-force gusts into the Ohio Valley. The U.S. toll: about $30 billion in damage and 112 deaths, dozens of them people who stayed on Bolivar and Galveston Island.
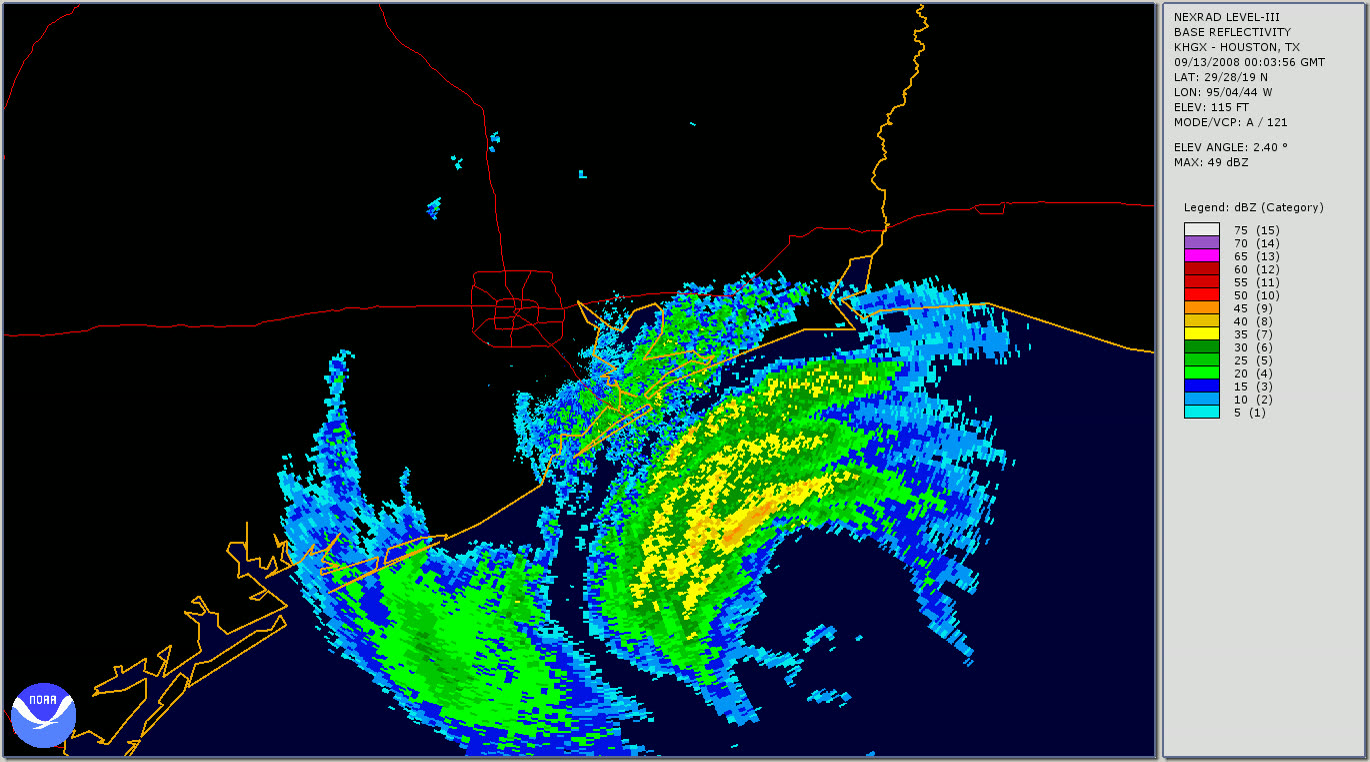
Radar loop of Ike's enormous circulation crossing the Texas coast at Galveston, September 13, 2008
Radar loop of Ike's enormous circulation crossing the Texas coast at Galveston, September 13, 2008 NOAA / NWS

The damage

Gilchrist, on the Bolivar Peninsula, effectively ceased to exist, aerial photos showed a handful of elevated houses standing in a field of slabs. Crystal Beach and Port Bolivar lost most structures. Galveston flooded from the bay side behind its seawall; the Strand historic district sat under feet of water and thousands of homes took surge. Wind damage ran inland through Houston, shattered high-rise glass downtown, roof damage across Harris County, and 2 million-plus customers lost power, some for weeks. Chambers County ranchland and communities along Trinity Bay flooded for miles inland.
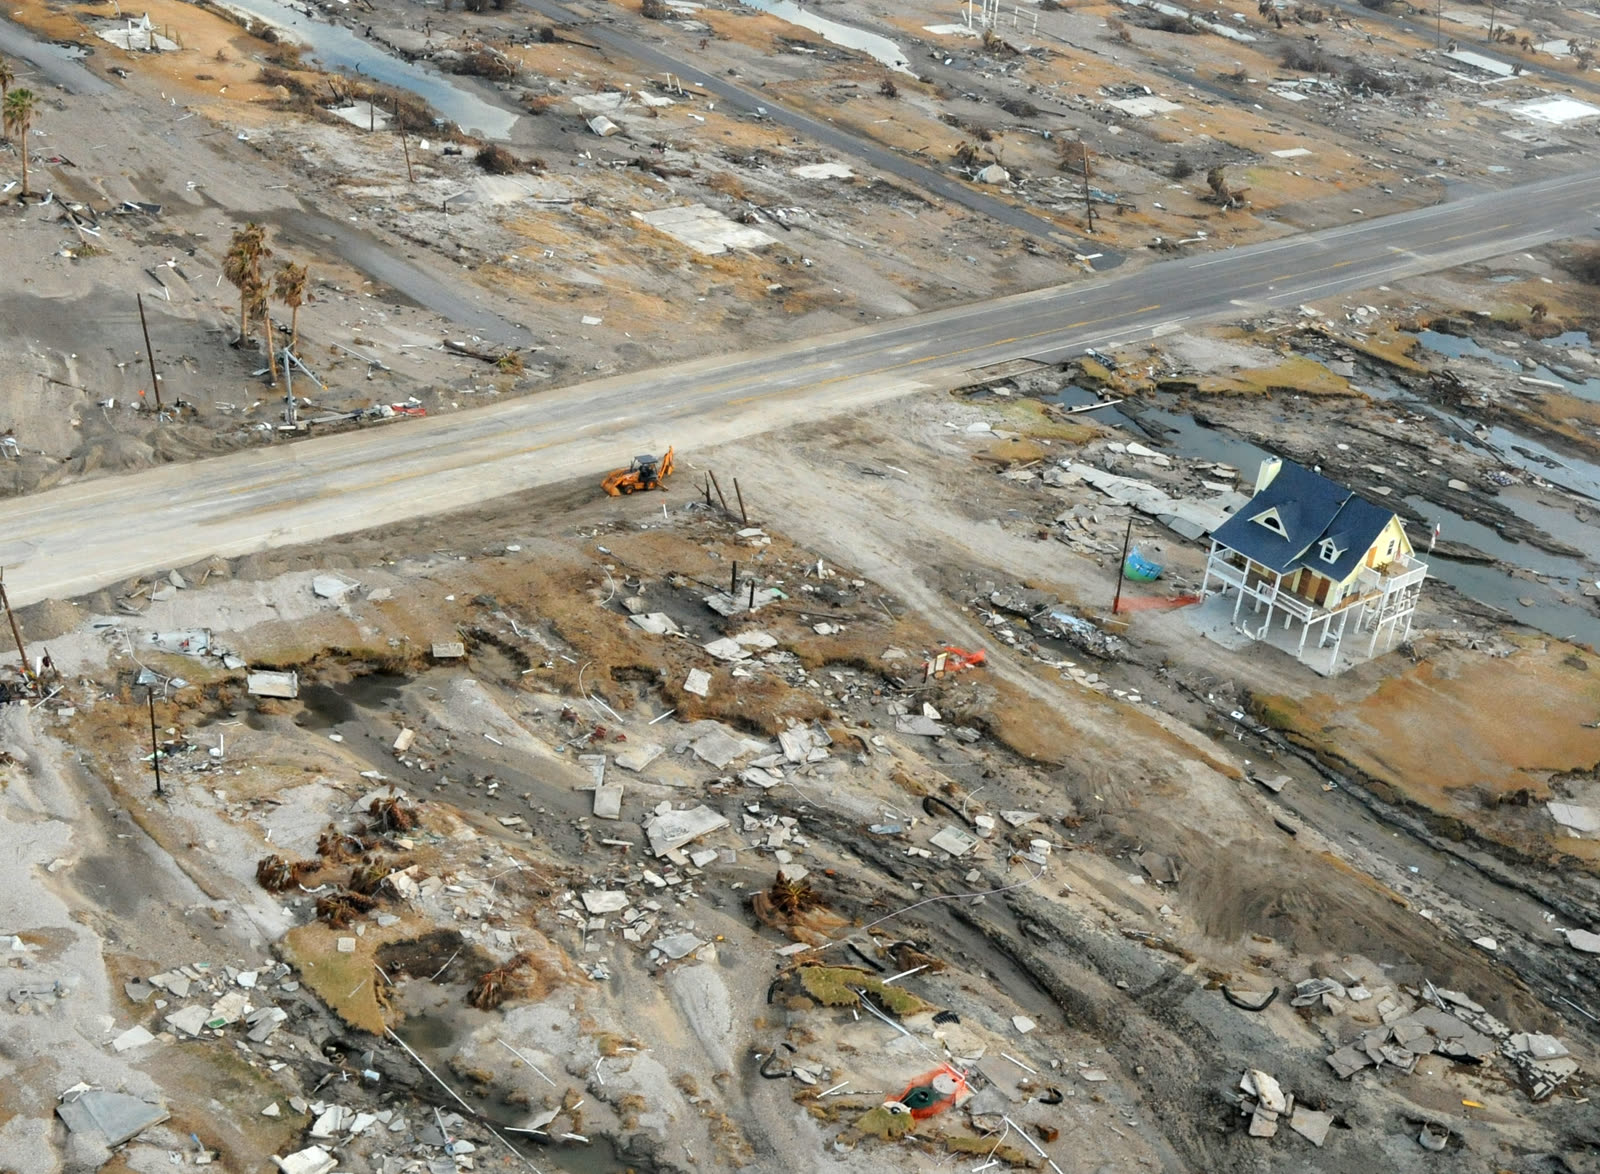
Gilchrist, on the Bolivar Peninsula, after Ike's 15-20 ft surge, nearly every structure swept away
Gilchrist, on the Bolivar Peninsula, after Ike's 15-20 ft surge, nearly every structure swept away FEMA / Jocelyn Augustino

The insurance aftermath

Ike generated roughly 815,000 Texas insurance claims, more than Harvey would, and about $8.7 billion in private-market payments within the first nine months, per Texas Department of Insurance data. But the defining fight was at the Texas Windstorm Insurance Association, the state's coastal wind insurer of last resort.

TWIA received about 93,000 Ike claims and ultimately paid more than $2.3 billion. It was not built for that volume: inspections lagged, payments ran slow and short, and roof settlements in particular drew mass disputes. Thousands of lawsuits followed, including claims filed years after the storm alleging damage never previously reported. On slabbed Bolivar properties, the wind-versus-surge causation fight from Katrina replayed: TWIA covered wind only, the NFIP covered flood only, and total-loss homeowners were caught proving which peril destroyed what.

The litigation wave pushed TWIA to the edge of insolvency and produced a legislative response. In a June 2011 special session, Texas passed HB 3, which rewrote how TWIA claims are disputed: strict claim and suit deadlines, a mandatory appraisal-style dispute process, limits on extra-contractual damages, and a rebuilt funding structure. Policyholder advocates argued it traded away coastal homeowners' leverage; the legislature judged the alternative was a broke wind pool. Either way, Ike is why suing TWIA works differently than suing any other Texas insurer.

Ike also restarted the mega-project debate: the "Ike Dike" coastal barrier concept for Galveston Bay, authorized by Congress in 2022, traces directly to the storm.
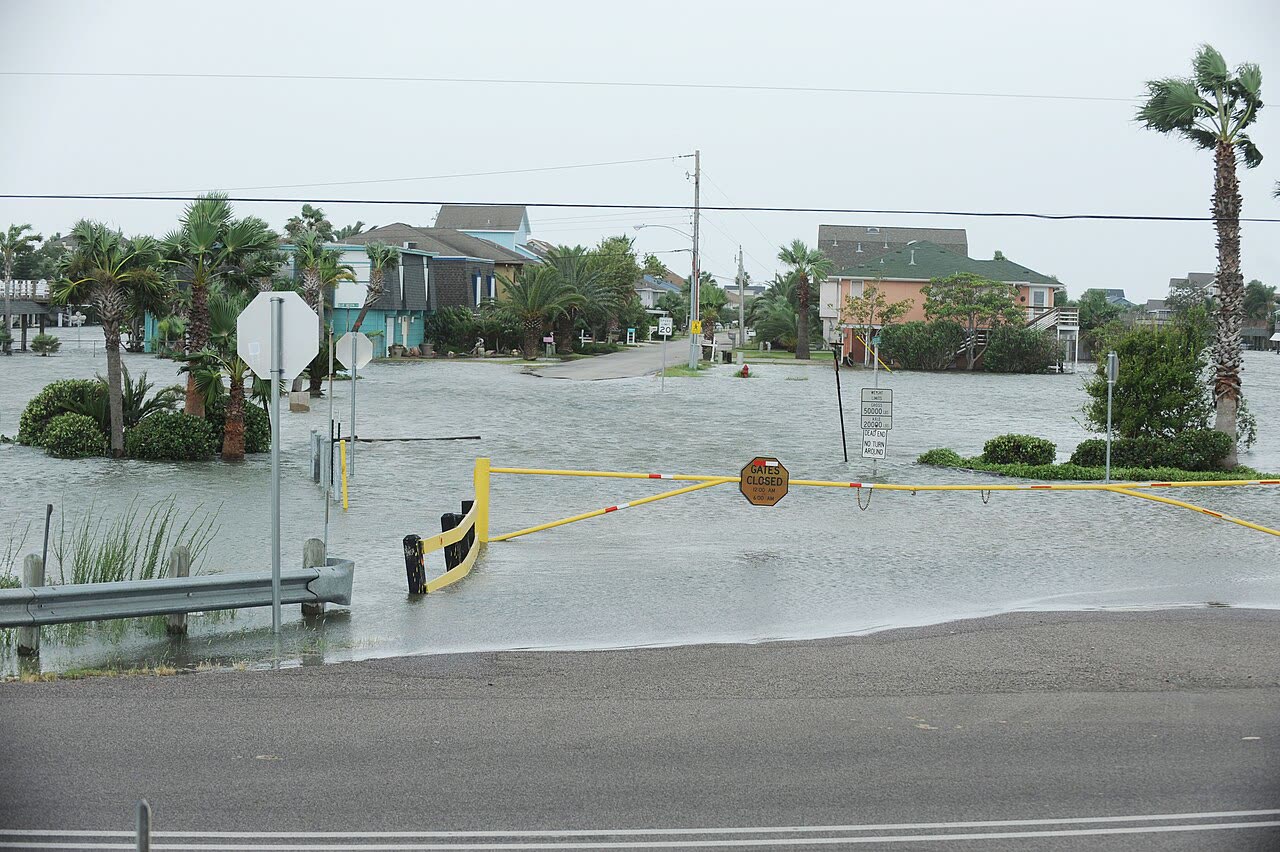
Bayou Vista, TX flooding as Ike's surge arrived hours ahead of the eye, September 12, 2008
Bayou Vista, TX flooding as Ike's surge arrived hours ahead of the eye, September 12, 2008 FEMA / Jocelyn Augustino

What policyholders learned

  • Category understates surge risk. Ike hit as a Category 2; its surge matched a Category 4. Policyholders on slabs learned coverage outcomes depended on carrying both wind and flood policies before the storm.
  • Dual-policy homes needed dual documentation. With TWIA paying wind and NFIP paying flood, each carrier pointed at the other's peril. Owners who documented wind damage evidence (time of loss, debris direction, neighbor accounts) preserved the wind side of total-loss claims.
  • Underpayment was the volume problem. Most TWIA disputes were about scope and amount, partial roof payments, depreciation, missed interior damage, and independent estimates were what reopened them.
  • Late-reported damage became a legal target. The post-Ike suits filed years later drove HB 3's tight deadlines; since 2011, Texas coastal policyholders who miss TWIA's claim and appeal windows lose rights entirely.
  • Slow is a strategy until it's documented. Complaint records and written demand letters, not phone calls, built the delay evidence that supported policyholder suits.

Not legal advice; consult an attorney about your specific claim. Damage figures are nominal (not inflation-adjusted) unless noted.

AT LANDFALL · HURRICANE IKE · 2008
15-20 ft
OF STORM SURGE · BOLIVAR PENINSULA
REPRESENTATIVE FOOTAGE
03 THE FULL RECORD

Every official record of Ike

Reports, imagery archives, flood data, and claims records, straight from the agencies.

FREE CASE REVIEW · NO FEE UNLESS YOU RECOVER
Ike claim denied?
CALL SC · 843-542-0454CALL FL · 813-588-0164FREE CLAIM REVIEW
RELATED GUIDES
HurricaneLaw.Pro, Florida and South Carolina property insurance claim resource HURRICANELAW.PRO

A comprehensive property-insurance claim resource for policyholders: denied and underpaid claims, coverage and bad-faith law, storm dossiers, carrier profiles, city guides, and the complete claims playbook. Florida and South Carolina.

▸ SEE THE FULL SITE MAP →
STORM ALERTS SOURCED FROM NOAA / NHC
SOUTH CAROLINA
496 Bramson Court, Suite 100
Mount Pleasant, SC 29464
CALL OR TEXT
FLORIDA
CALL OR TEXT
CLAIMS 9
BAD FAITH 7
DENIAL FILINGS
HOW CLAIMS GET DENIED
DENIAL DOCUMENTS
DENIALS, ANSWERED 9
COVERAGE 13
COMMERCIAL 8
ROOFS 8
TREES 5
DIRECTORIES
STORMS 51
WEATHER
NEWS & SITE 22
STORM ARCHIVE, CITIES & NEWS
Most recent below. Every storm dossier, city resource, and article is on its hub (linked at each heading) or the grouped site map →. All 73 carriers and 95 public-adjuster firms are in the Directories column above.
STORM ARCHIVE · 51 →
Hurricane Debby 2024Hurricane Helene 2024Hurricane Milton 2024Hurricane Idalia 2023Hurricane Ian 2022Hurricane Nicole 2022Hurricane Ida 2021Hurricane Laura 2020 View all 51 →
FLORIDA CITY RESOURCES · 37 →
Boca RatonBradentonCape CoralClearwaterCrestviewDaytona BeachDestinDunedin View all 37 →
SOUTH CAROLINA CITY RESOURCES · 8 →
BeaufortCharlestonColumbiaFlorenceGreenvilleHilton Head IslandMount PleasantMyrtle Beach
NEWS & UPDATES · 22 →

Coverage summaries, policy-language quotations, dollar figures, deadlines, and chart examples throughout this site are general information based on typical or standard policy forms and are illustrative only: they are not a quote, a guarantee of coverage, or a promise of any outcome. Every insurance policy is different: your own policy, endorsements, and state law control, so read your policy and confirm current statutes. Weather imagery courtesy of NOAA, the National Hurricane Center, and the National Weather Service. Legal services are provided by Halversen Law. Nothing on this site is legal advice; consult an attorney about your specific claim.

PrivacyTermsDisclaimerAboutContact
This site is not legal advice, and it is not a substitute for an attorney. Anything legal needs a licensed lawyer reading your policy and your facts. We recommend Halversen Law: the free claim review is the fastest way to get real eyes on your claim.
© 2026 HURRICANELAW.PRO · ALL RIGHTS RESERVED 27.9°N 82.5°W · ATLANTIC BASIN MONITOR
LAW FIRM
Halversen Law LICENSED · FLORIDA & SOUTH CAROLINA

Legal matters are handled by Halversen Law, a law firm licensed in Florida and South Carolina.

FREE CASE REVIEW