
ACTIVE STORM TRACK →
PROPERTY-INSURANCE CLAIM HELP FL CITIESSC CITIESGUIDESTATESNEWSSITE MAPABOUT
HurricaneLaw.Pro, Florida and South Carolina property insurance claim resource HURRICANELAW.PRO
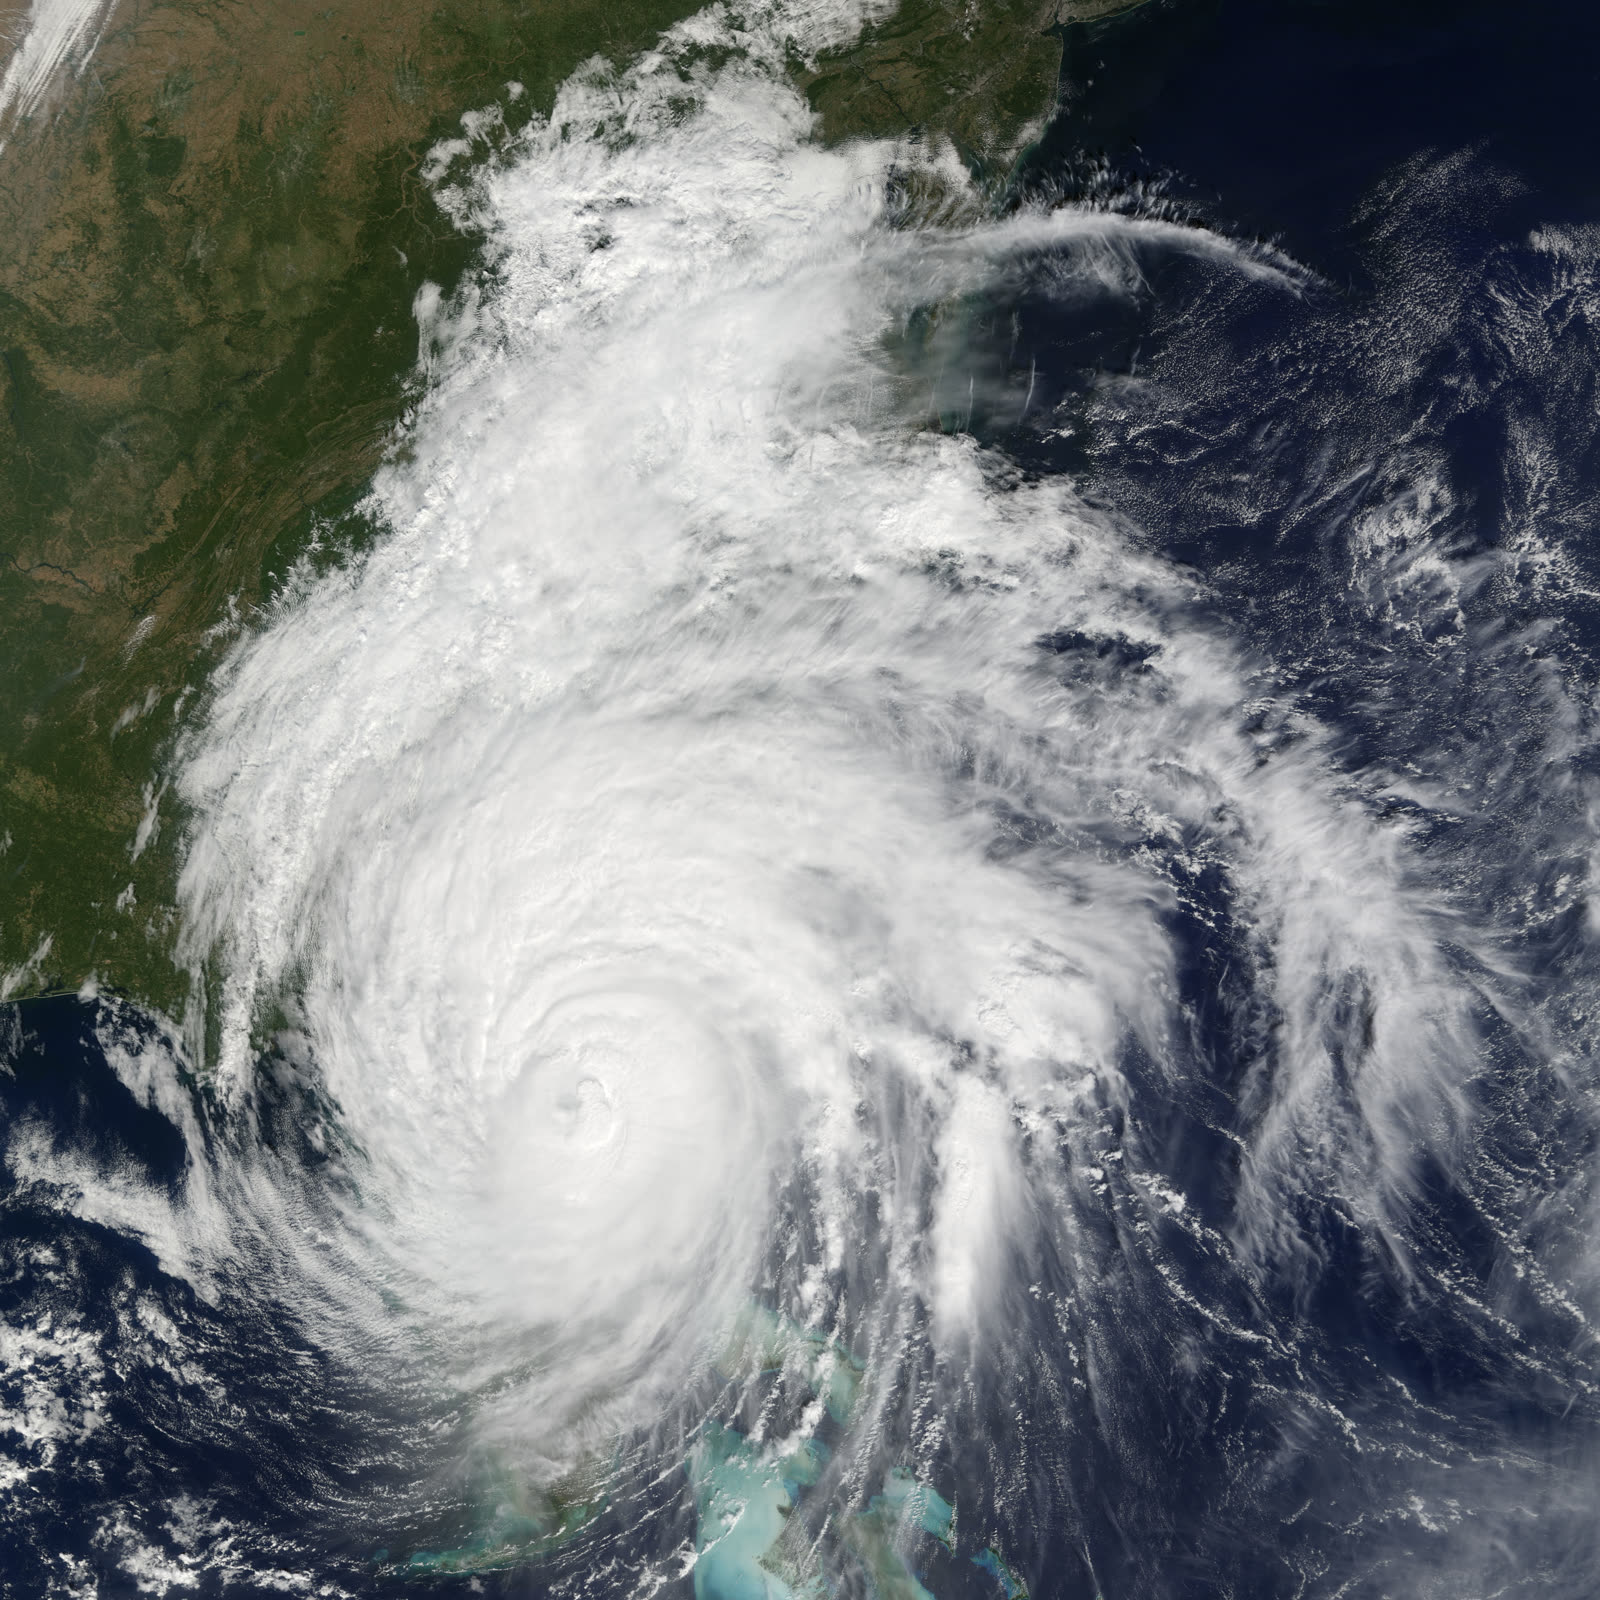
Matthew hugging the Florida coast on October 7, 2016, the eyewall stayed just offshore for over 36 hours
STORM ARCHIVE / 2016 LANDFALL 33.0°N 79.6°W
CAT 1 AT LANDFALL PEAK CAT 5 FL & SC · 2016 · 165 mph

Hurricane Matthew

Landfall: McClellanville, SC, after paralleling the entire FL east coast offshore · 2016-10-08. Matthew never made a Florida landfall, and still generated 100,000+ Florida claims, proving a near-miss can be a full-scale insurance event

NASA Earth Observatory
AT LANDFALL
CAT 1
PEAK INTENSITY
CAT 5 · 165 mph
PRESSURE
934 mb (peak); 963 mb at SC landfall
STORM SURGE
6-8 ft
DAMAGE
$10.3B (US)
DEATHS
34 (US)
01 THE PATH

Where it hit, start to finish

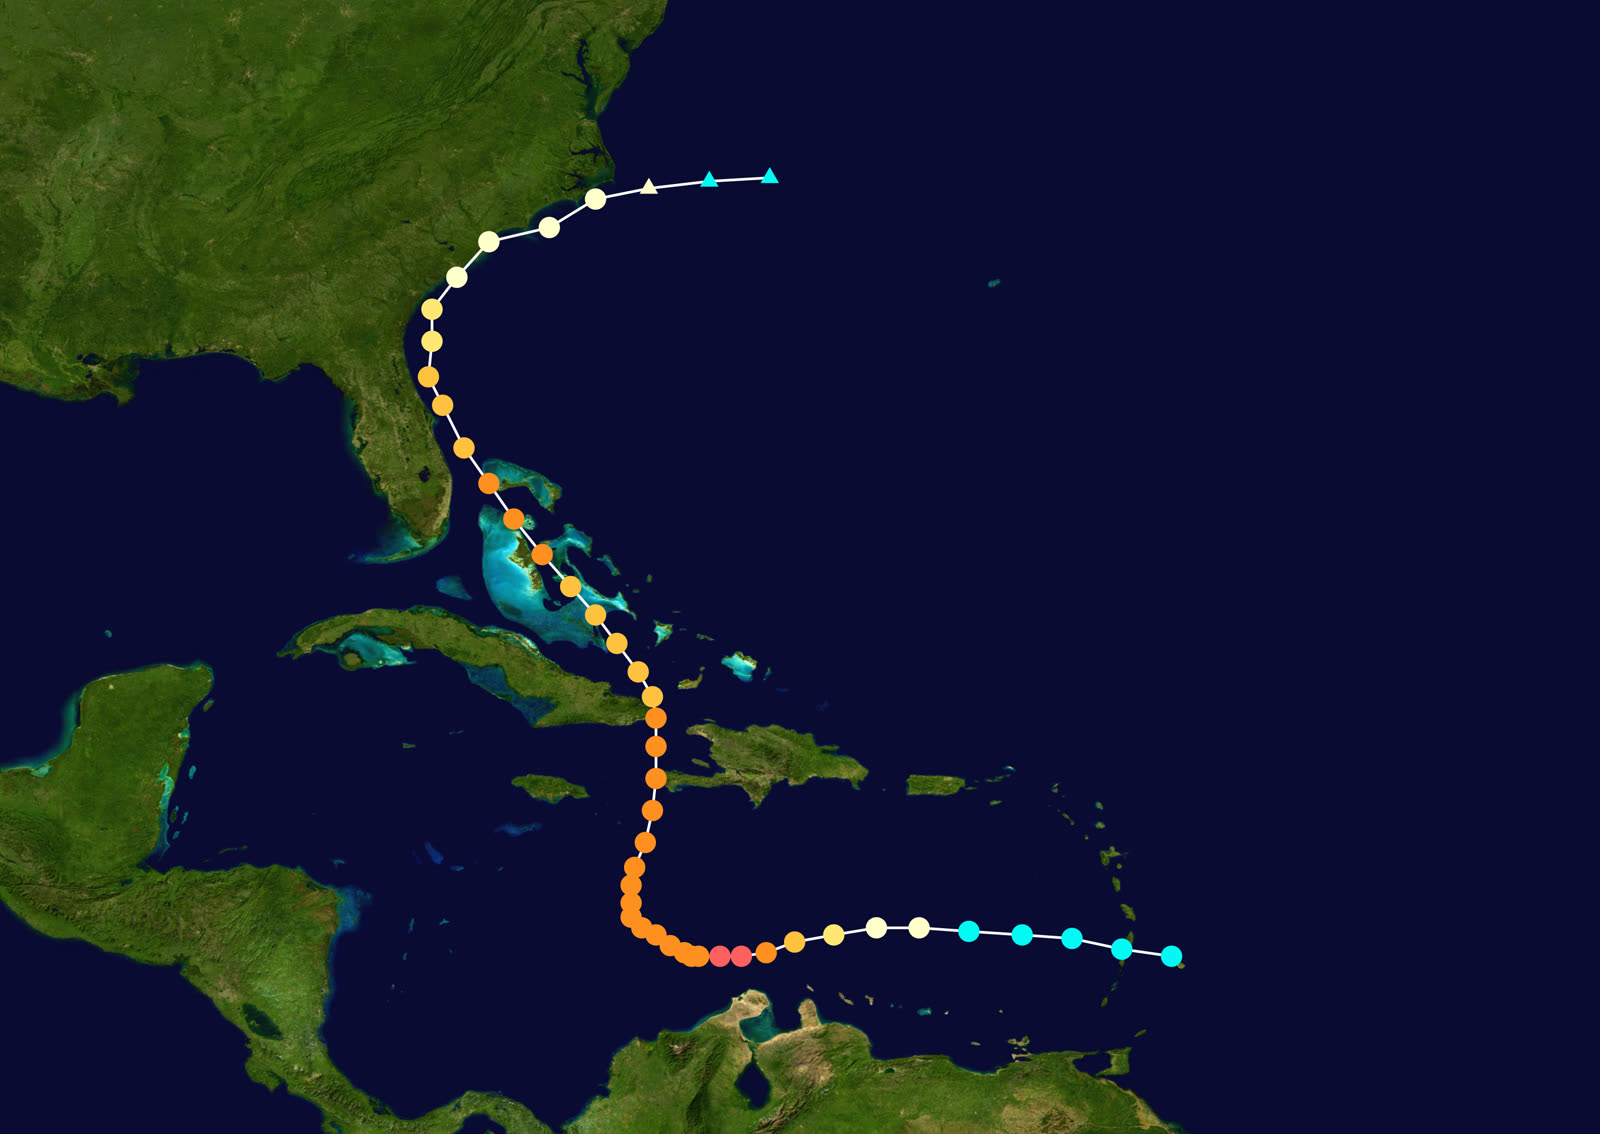
TRACK · HURRICANE MATTHEWNOAA / NHC (best-track data)
Best track of Hurricane Matthew, September 28 - October 9, 2016
Caribbean Sea / Haiti
CATEGORY 5 PEAK - 165 MPH

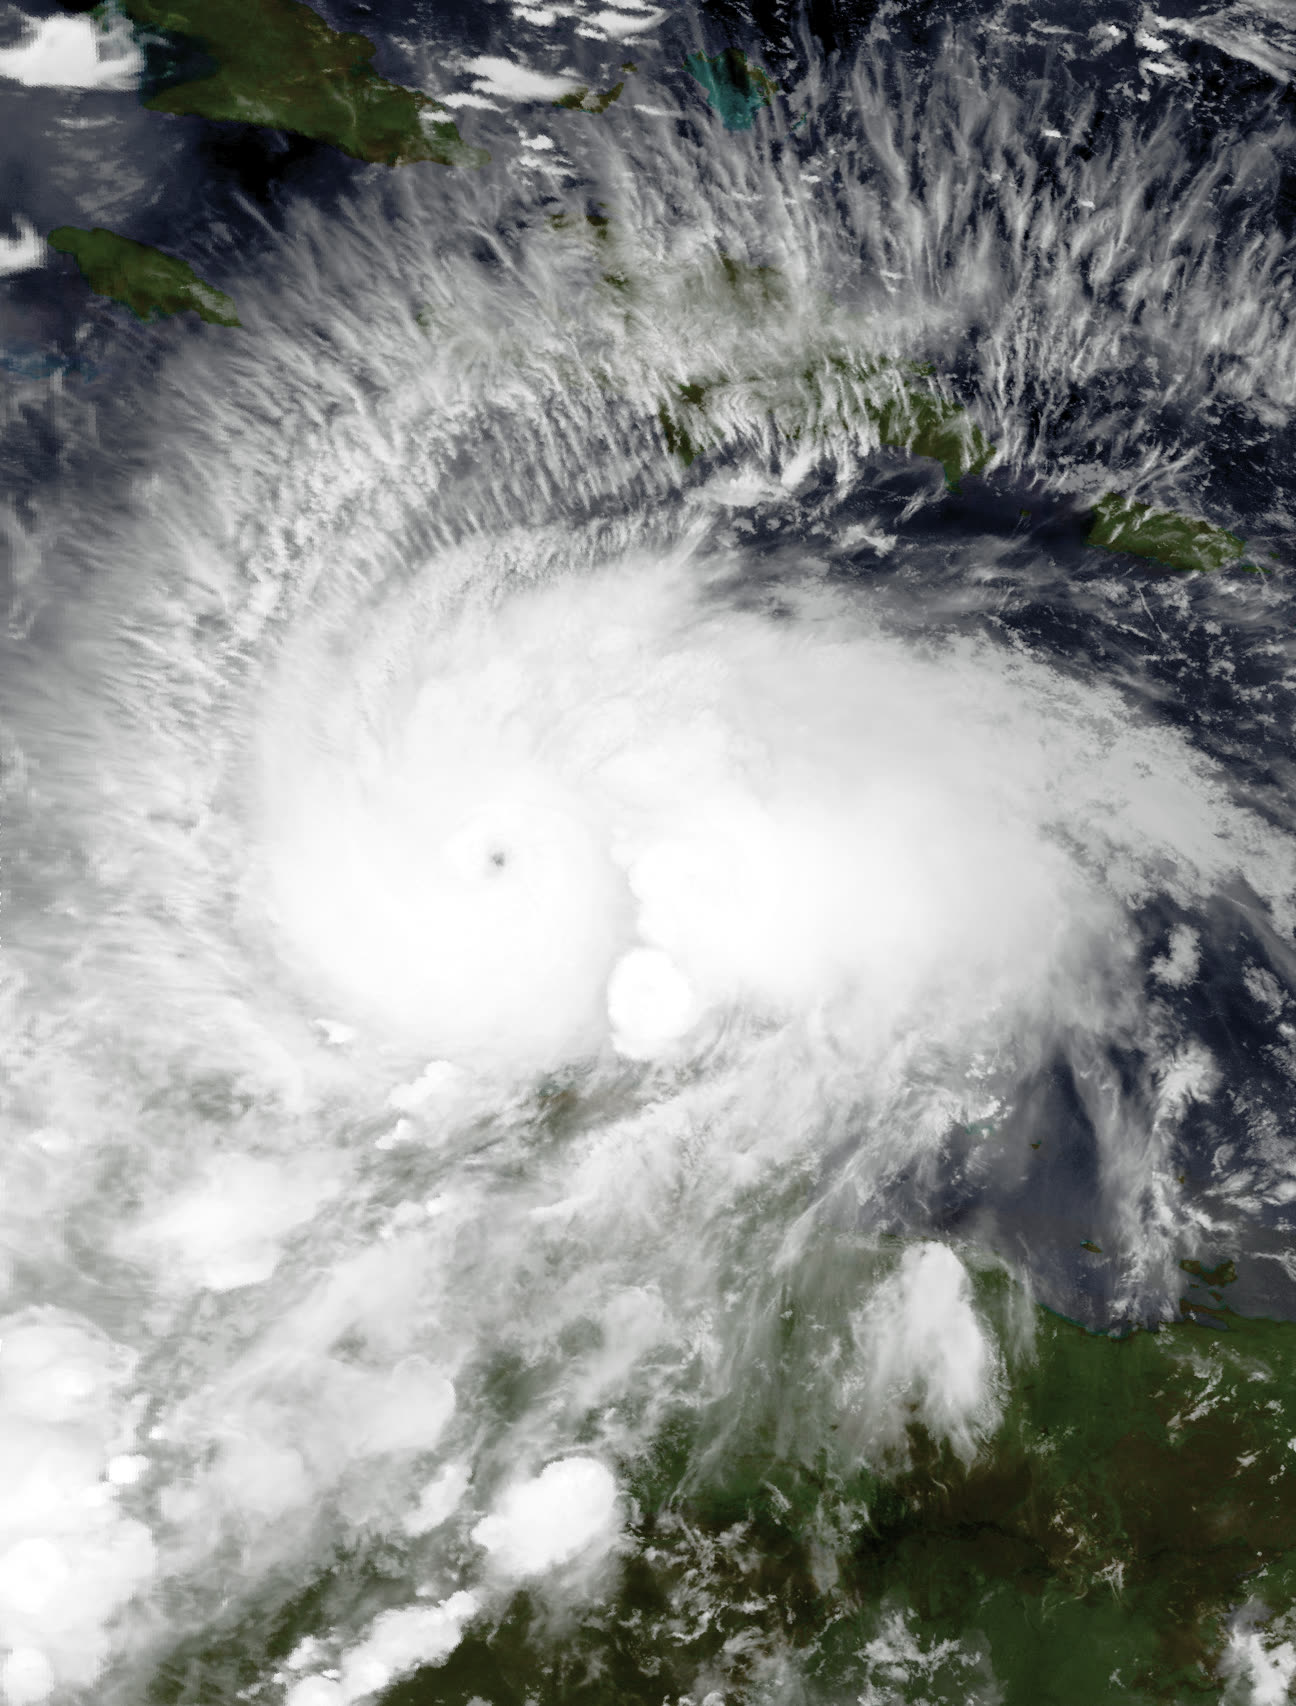
Matthew exploded to Category 5 on October 1, the Atlantic's southernmost Cat 5 on record, then struck Haiti's Tiburon Peninsula at Category 4, killing over 500 people there.

Cape Canaveral / Space Coast, FL
EYEWALL 25 MILES OFFSHORE

Matthew paralleled Florida's east coast October 6-7 as a Cat 3-4. The western eyewall grazed Cape Canaveral; Kennedy Space Center took wind damage and over 1 million Florida customers lost power.

St. Augustine / Flagler Beach, FL
SURGE AND EROSION WITHOUT LANDFALL

Surge flooded St. Augustine's historic district and Jacksonville's beach towns; erosion collapsed a stretch of oceanfront highway A1A at Flagler Beach.

McClellanville, SC
CAT 1 LANDFALL - OCTOBER 8

After 1,000 miles offshore, Matthew finally made US landfall at McClellanville at 11 a.m., Category 1, near 963 mb; close to where Hugo struck in 1989. Charleston flooded on a near-record tide; Edisto Beach took heavy surge damage.

Nichols, SC / Lumber River basin
INLAND FLOOD DISASTER DAYS LATER

10-17 inches of rain sent the Little Pee Dee and Lumber rivers to record crests. The town of Nichols flooded nearly end to end days after skies cleared; adjacent North Carolina counted most of the storm's 34 US deaths in similar river flooding.

Off Cape Hatteras, NC
EXIT TO SEA

Matthew turned east on October 9 and lost tropical status, leaving $10.3 billion in US damage across five states.

02 THE RECORD IN IMAGES
ALL IMAGERY U.S. GOV / PUBLIC DOMAIN
SATELLITE NASA / NRL
Matthew near peak intensity as a 165-mph Category 5 in the Caribbean, October 1, 2016
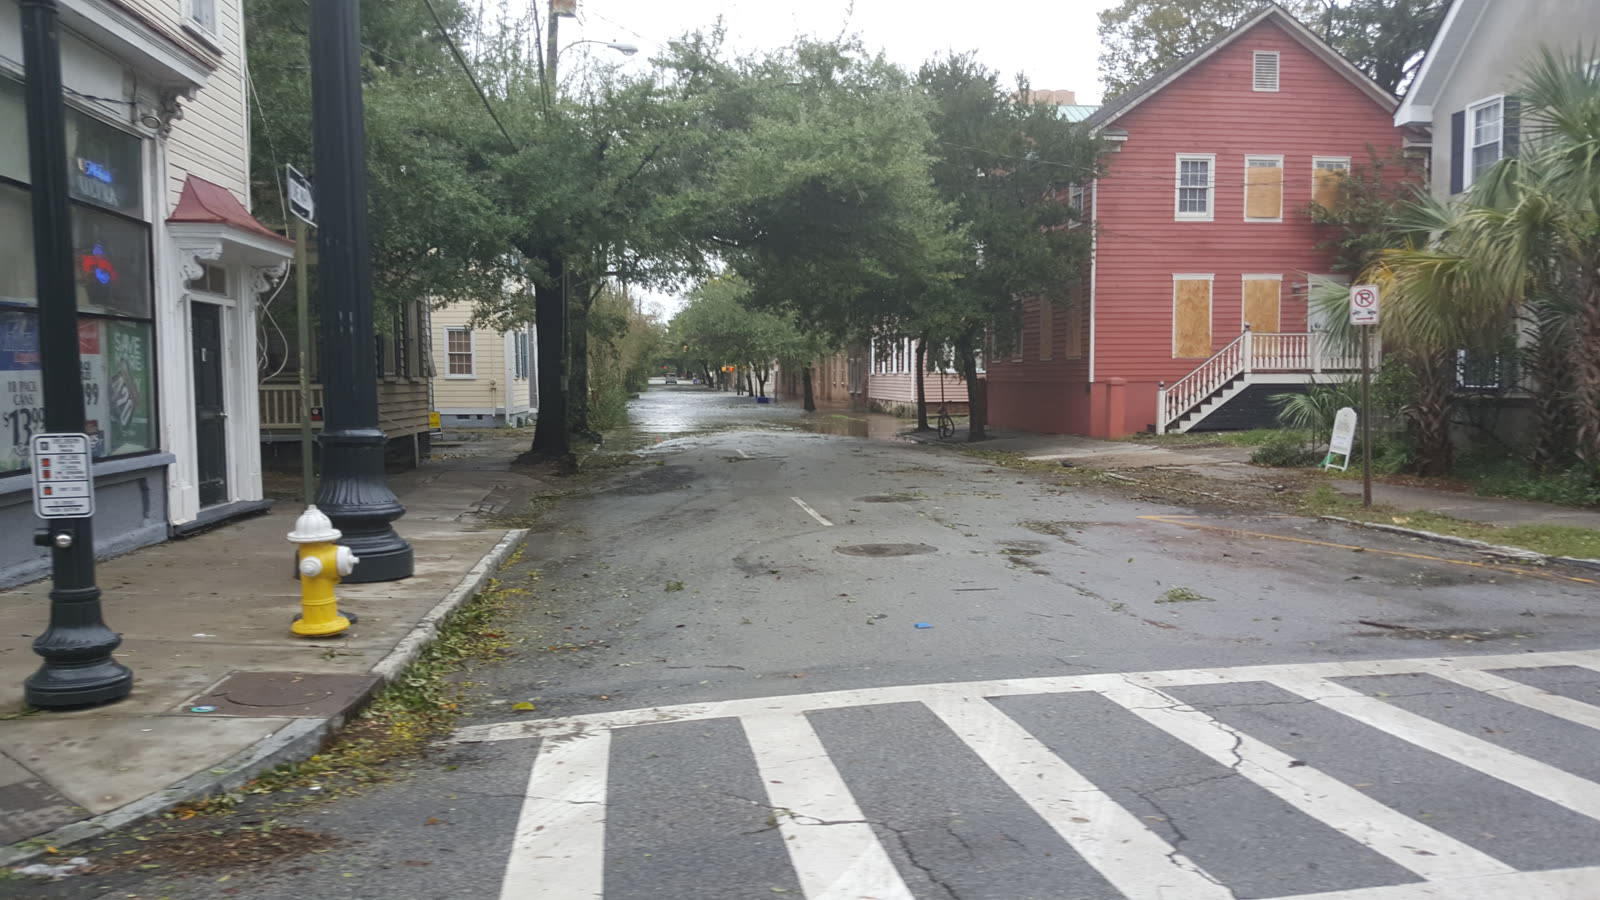
FLOOD US Army National Guard
South Carolina National Guard moving through flooded Charleston streets after landfall
MAP NOAA / NHC
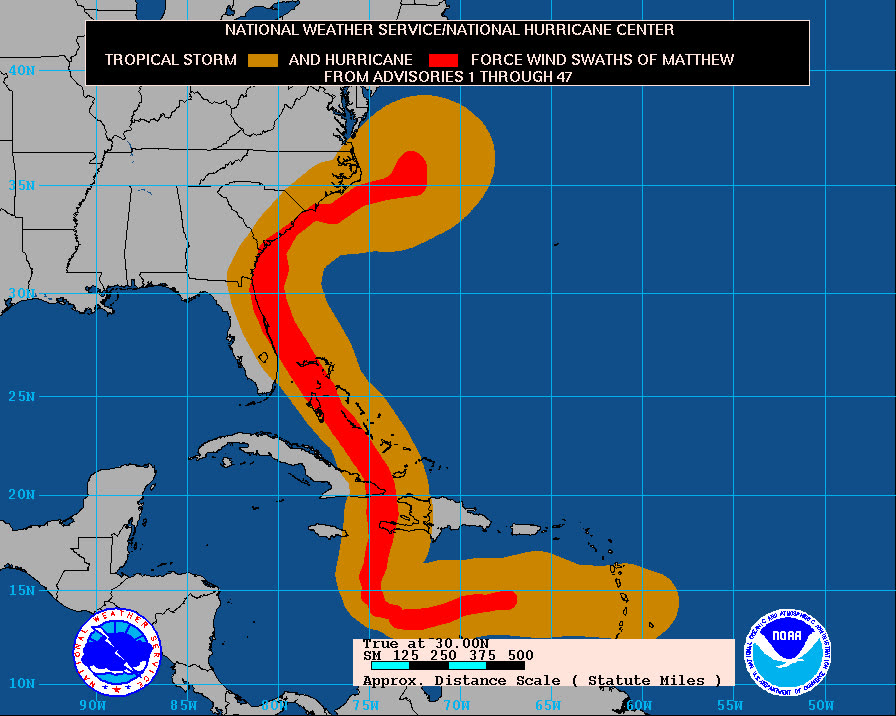
Cumulative wind history, hurricane-force winds brushed 500 miles of coastline without a Florida landfall

The storm

Matthew became the Atlantic's southernmost Category 5 on record on October 1, 2016, peaking at 165 mph in the Caribbean. It devastated Haiti's Tiburon Peninsula as a Category 4, over 500 deaths there, then crossed eastern Cuba and raked the Bahamas.

What followed was one of the strangest major-hurricane tracks in US history: Matthew paralleled the entire Florida east coast October 6-7 as a Category 3-4, its eyewall 25-40 miles offshore, never making landfall. The center hugged the Georgia and South Carolina coasts before finally coming ashore at McClellanville, South Carolina, Hugo's old landfall zone, at 11 a.m. on October 8, as a Category 1.

The rain kept going after the wind stopped. Ten to seventeen inches fell across the eastern Carolinas, and rivers crested days later at record levels. The US toll: 34 deaths and $10.3 billion in damage across Florida, Georgia, the Carolinas, and Virginia.
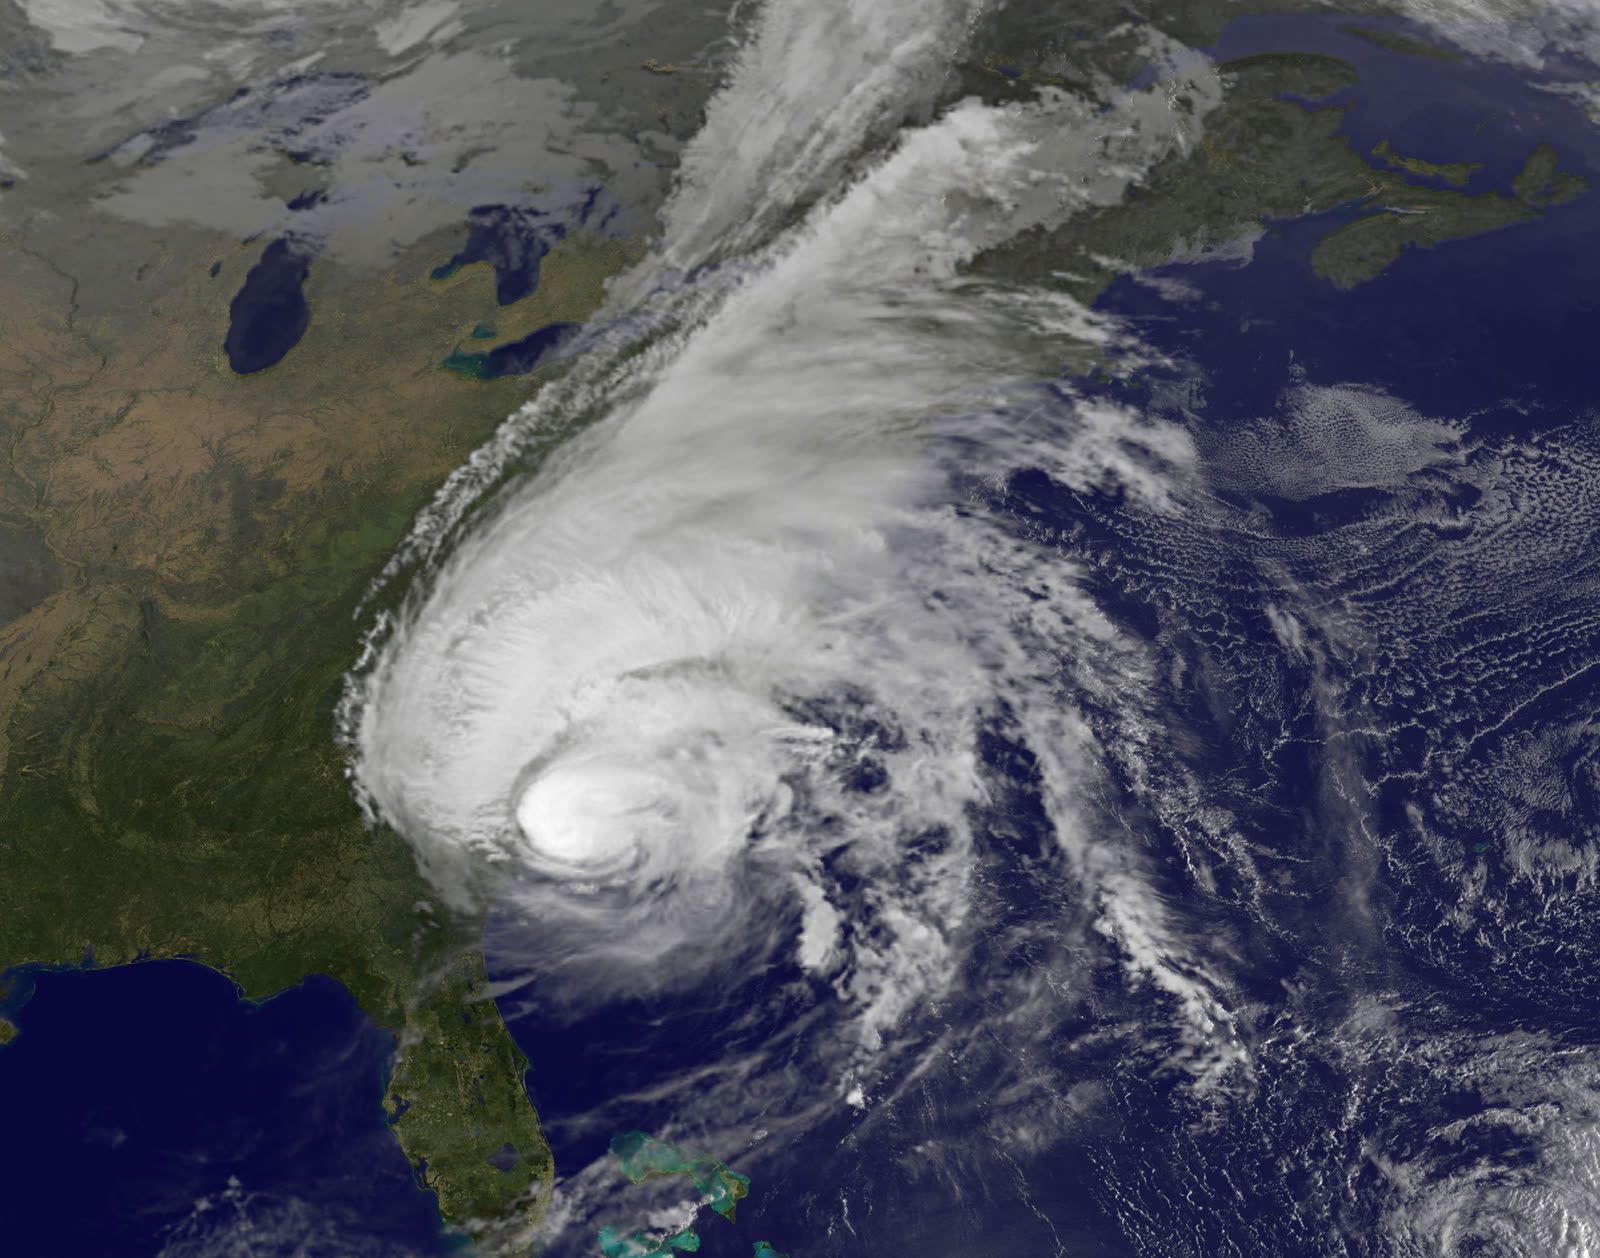
Matthew on the morning of October 8, hours before its Category 1 landfall at McClellanville, SC
Matthew on the morning of October 8, hours before its Category 1 landfall at McClellanville, SC NOAA

The damage

Florida's damage came without a landfall. Over a million customers lost power; Kennedy Space Center took roof and facility damage from the grazing eyewall; surge flooded St. Augustine's historic district and the Jacksonville beach towns; and erosion collapsed part of oceanfront highway A1A at Flagler Beach. Dune loss ran the length of Volusia, Flagler, and St. Johns counties, erosion that Ian and Nicole would finish off six years later.

In South Carolina, Charleston flooded on one of its highest tides since Hugo, Edisto Beach took direct surge damage, and Hilton Head lost thousands of trees onto homes. Then came the inland flood: the Little Pee Dee and Lumber rivers put the town of Nichols underwater nearly end to end, days after the storm had passed.
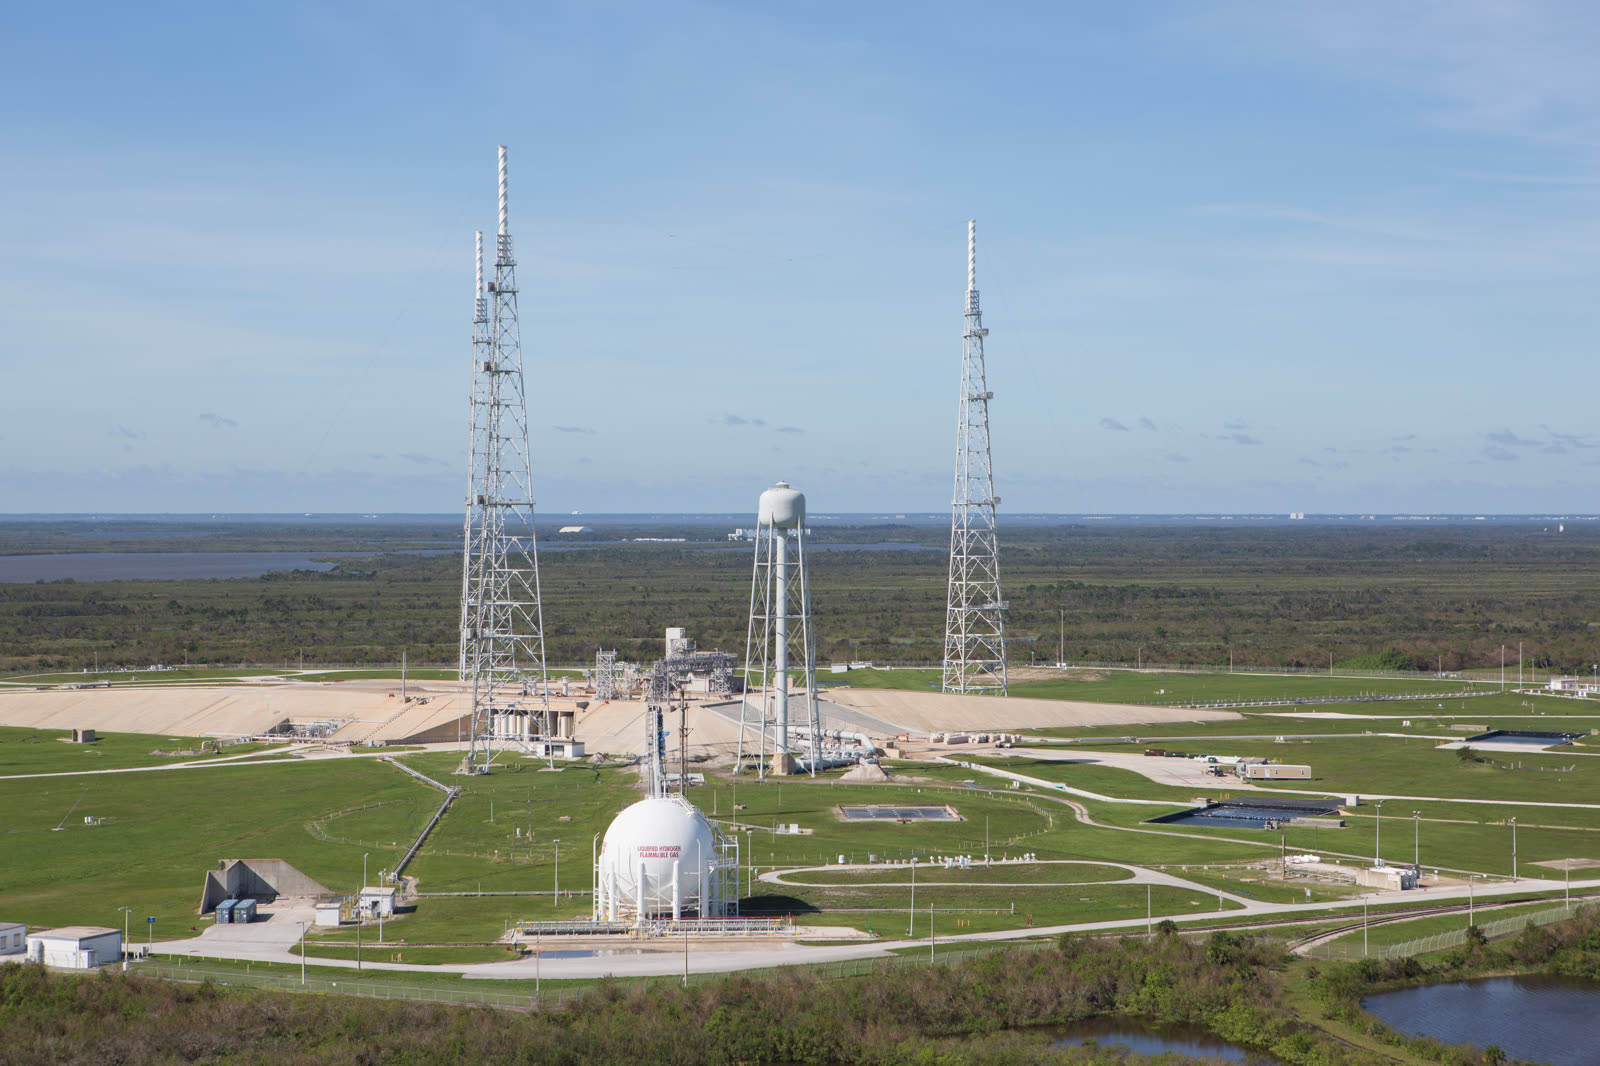
NASA aerial damage survey of Kennedy Space Center after Matthew's eyewall grazed Cape Canaveral
NASA aerial damage survey of Kennedy Space Center after Matthew's eyewall grazed Cape Canaveral NASA

The insurance aftermath

Matthew proved a near-miss is still a mass claims event. Two weeks after the storm, FLOIR's data call already showed more than 91,000 Florida claims, nearly 80,000 residential, with estimated insured losses of $550 million; the count kept climbing past 100,000. South Carolina's private insurance claims also totaled roughly $550 million. RMS put total US insured losses near $5 billion.

Because Matthew was a named hurricane, percentage hurricane deductibles (2-5% of dwelling limit) applied throughout both states, so a large share of Florida's wind claims, mostly shingle and screen-enclosure losses, closed below deductible. That math became the defining complaint of the storm: six-figure deductible thresholds against five-figure damage.

The coastal fights were about causation. St. Augustine and the beach towns took wind and surge together, and carriers attributed water-line damage to excluded flood; only NFIP or private flood policies responded below that line. Beachfront owners also learned that erosion and land loss are excluded entirely, a seawall and lost dune are not a covered peril, even when the house above them is newly condemned.

South Carolina's inland flooding was almost purely an NFIP event. Nichols and the Lumber River basin had minimal flood-insurance penetration, these were inland towns outside mapped high-risk zones, so FEMA Individual Assistance under DR-4286, not insurance, carried most households. It was South Carolina's second federally declared flood disaster in 12 months, following the October 2015 rain event, and the back-to-back losses pushed inland flood mapping and buyout programs up the state's agenda. When Florence flooded the same river basins again in 2018, Nichols flooded again.
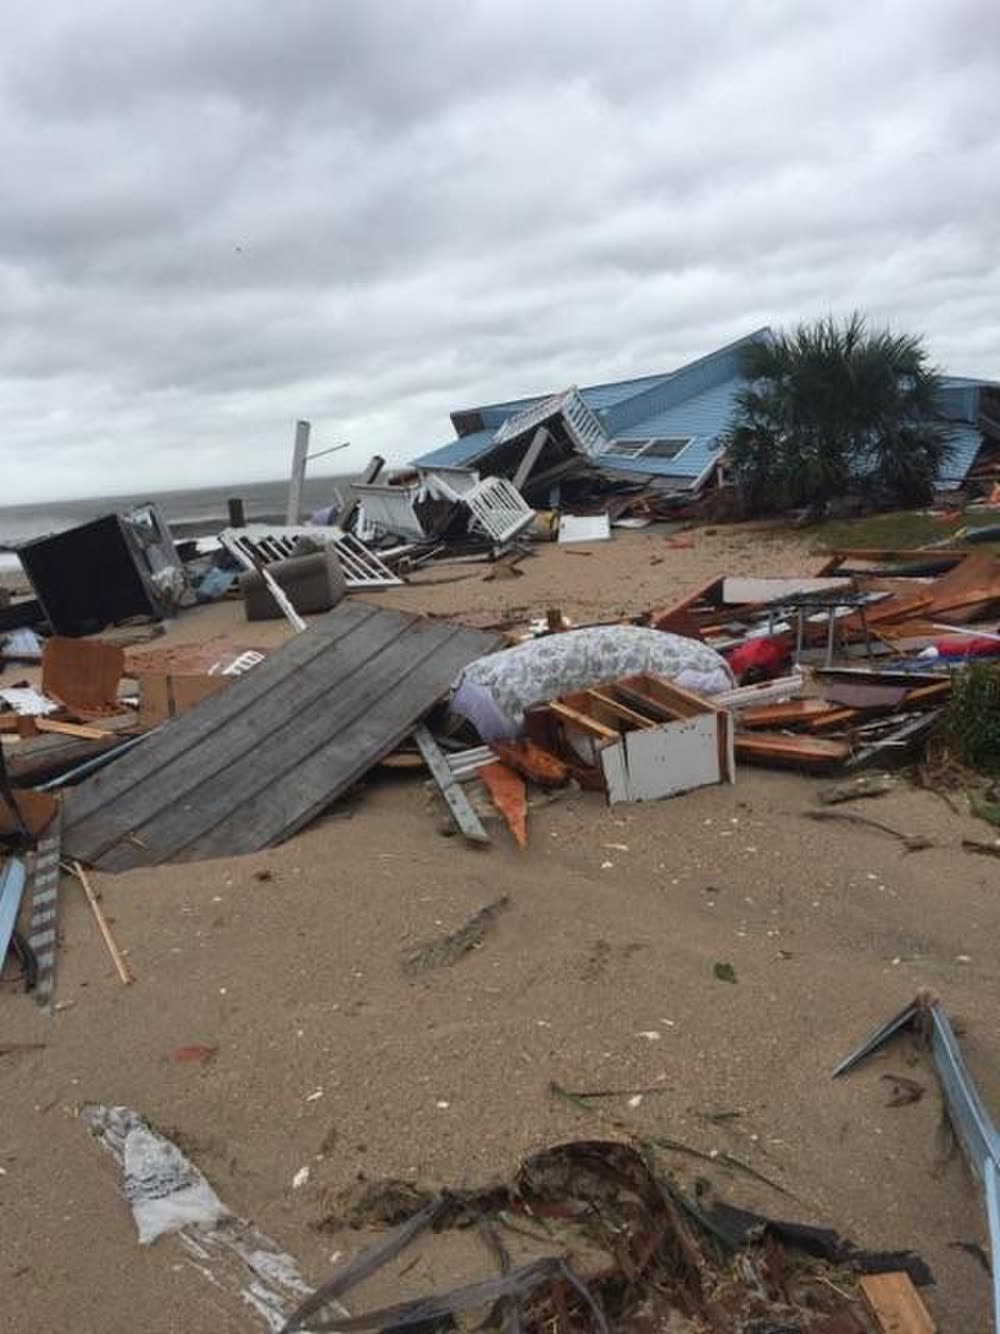
Surge and flood damage at Edisto Beach, SC, October 8, 2016
Surge and flood damage at Edisto Beach, SC, October 8, 2016 US Army National Guard

What policyholders learned

  • No landfall still means hurricane deductibles. A named hurricane offshore triggers the percentage deductible; documenting every category of damage (roof, screens, fencing, interior water) was what pushed claims over the threshold.
  • The water line is where the claim gets contested. Mixed wind-surge losses in St. Augustine turned on evidence of wind damage occurring before the flood arrived, photos, timestamps, neighbor accounts.
  • Erosion is not a covered peril. Oceanfront owners at Flagler Beach and Edisto found dune and land loss excluded; only damage to insured structures counted.
  • Inland homes outside flood zones flood. Nichols was not a mapped high-risk area. Lender rules, not risk, drive flood-policy take-up, and rivers do not read flood maps.
  • River crests lag the storm. Claims-critical documentation in the Carolinas happened days after landfall; owners who waited out the crest and photographed high-water marks had the stronger NFIP files.

Not legal advice; consult an attorney about your specific claim. Damage figures are nominal (not inflation-adjusted) unless noted.

AT LANDFALL · HURRICANE MATTHEW · 2016
6-8 ft
OF STORM SURGE · GA / LOWER SC COAST
REPRESENTATIVE FOOTAGE
03 THE FULL RECORD

Every official record of Matthew

Reports, imagery archives, flood data, and claims records, straight from the agencies.

FREE CASE REVIEW · NO FEE UNLESS YOU RECOVER
Matthew claim denied?
CALL SC · 843-542-0454CALL FL · 813-588-0164FREE CLAIM REVIEW
RELATED GUIDES
HurricaneLaw.Pro, Florida and South Carolina property insurance claim resource HURRICANELAW.PRO

A comprehensive property-insurance claim resource for policyholders: denied and underpaid claims, coverage and bad-faith law, storm dossiers, carrier profiles, city guides, and the complete claims playbook. Florida and South Carolina.

▸ SEE THE FULL SITE MAP →
STORM ALERTS SOURCED FROM NOAA / NHC
SOUTH CAROLINA
496 Bramson Court, Suite 100
Mount Pleasant, SC 29464
CALL OR TEXT
FLORIDA
CALL OR TEXT
CLAIMS 9
BAD FAITH 7
DENIAL FILINGS
HOW CLAIMS GET DENIED
DENIAL DOCUMENTS
DENIALS, ANSWERED 9
COVERAGE 13
COMMERCIAL 8
ROOFS 8
TREES 5
DIRECTORIES
STORMS 51
WEATHER
NEWS & SITE 22
STORM ARCHIVE, CITIES & NEWS
Most recent below. Every storm dossier, city resource, and article is on its hub (linked at each heading) or the grouped site map →. All 73 carriers and 95 public-adjuster firms are in the Directories column above.
STORM ARCHIVE · 51 →
Hurricane Debby 2024Hurricane Helene 2024Hurricane Milton 2024Hurricane Idalia 2023Hurricane Ian 2022Hurricane Nicole 2022Hurricane Ida 2021Hurricane Laura 2020 View all 51 →
FLORIDA CITY RESOURCES · 37 →
Boca RatonBradentonCape CoralClearwaterCrestviewDaytona BeachDestinDunedin View all 37 →
SOUTH CAROLINA CITY RESOURCES · 8 →
BeaufortCharlestonColumbiaFlorenceGreenvilleHilton Head IslandMount PleasantMyrtle Beach
NEWS & UPDATES · 22 →

Coverage summaries, policy-language quotations, dollar figures, deadlines, and chart examples throughout this site are general information based on typical or standard policy forms and are illustrative only: they are not a quote, a guarantee of coverage, or a promise of any outcome. Every insurance policy is different: your own policy, endorsements, and state law control, so read your policy and confirm current statutes. Weather imagery courtesy of NOAA, the National Hurricane Center, and the National Weather Service. Legal services are provided by Halversen Law. Nothing on this site is legal advice; consult an attorney about your specific claim.

PrivacyTermsDisclaimerAboutContact
This site is not legal advice, and it is not a substitute for an attorney. Anything legal needs a licensed lawyer reading your policy and your facts. We recommend Halversen Law: the free claim review is the fastest way to get real eyes on your claim.
© 2026 HURRICANELAW.PRO · ALL RIGHTS RESERVED 27.9°N 82.5°W · ATLANTIC BASIN MONITOR
LAW FIRM
Halversen Law LICENSED · FLORIDA & SOUTH CAROLINA

Legal matters are handled by Halversen Law, a law firm licensed in Florida and South Carolina.

FREE CASE REVIEW