The storm
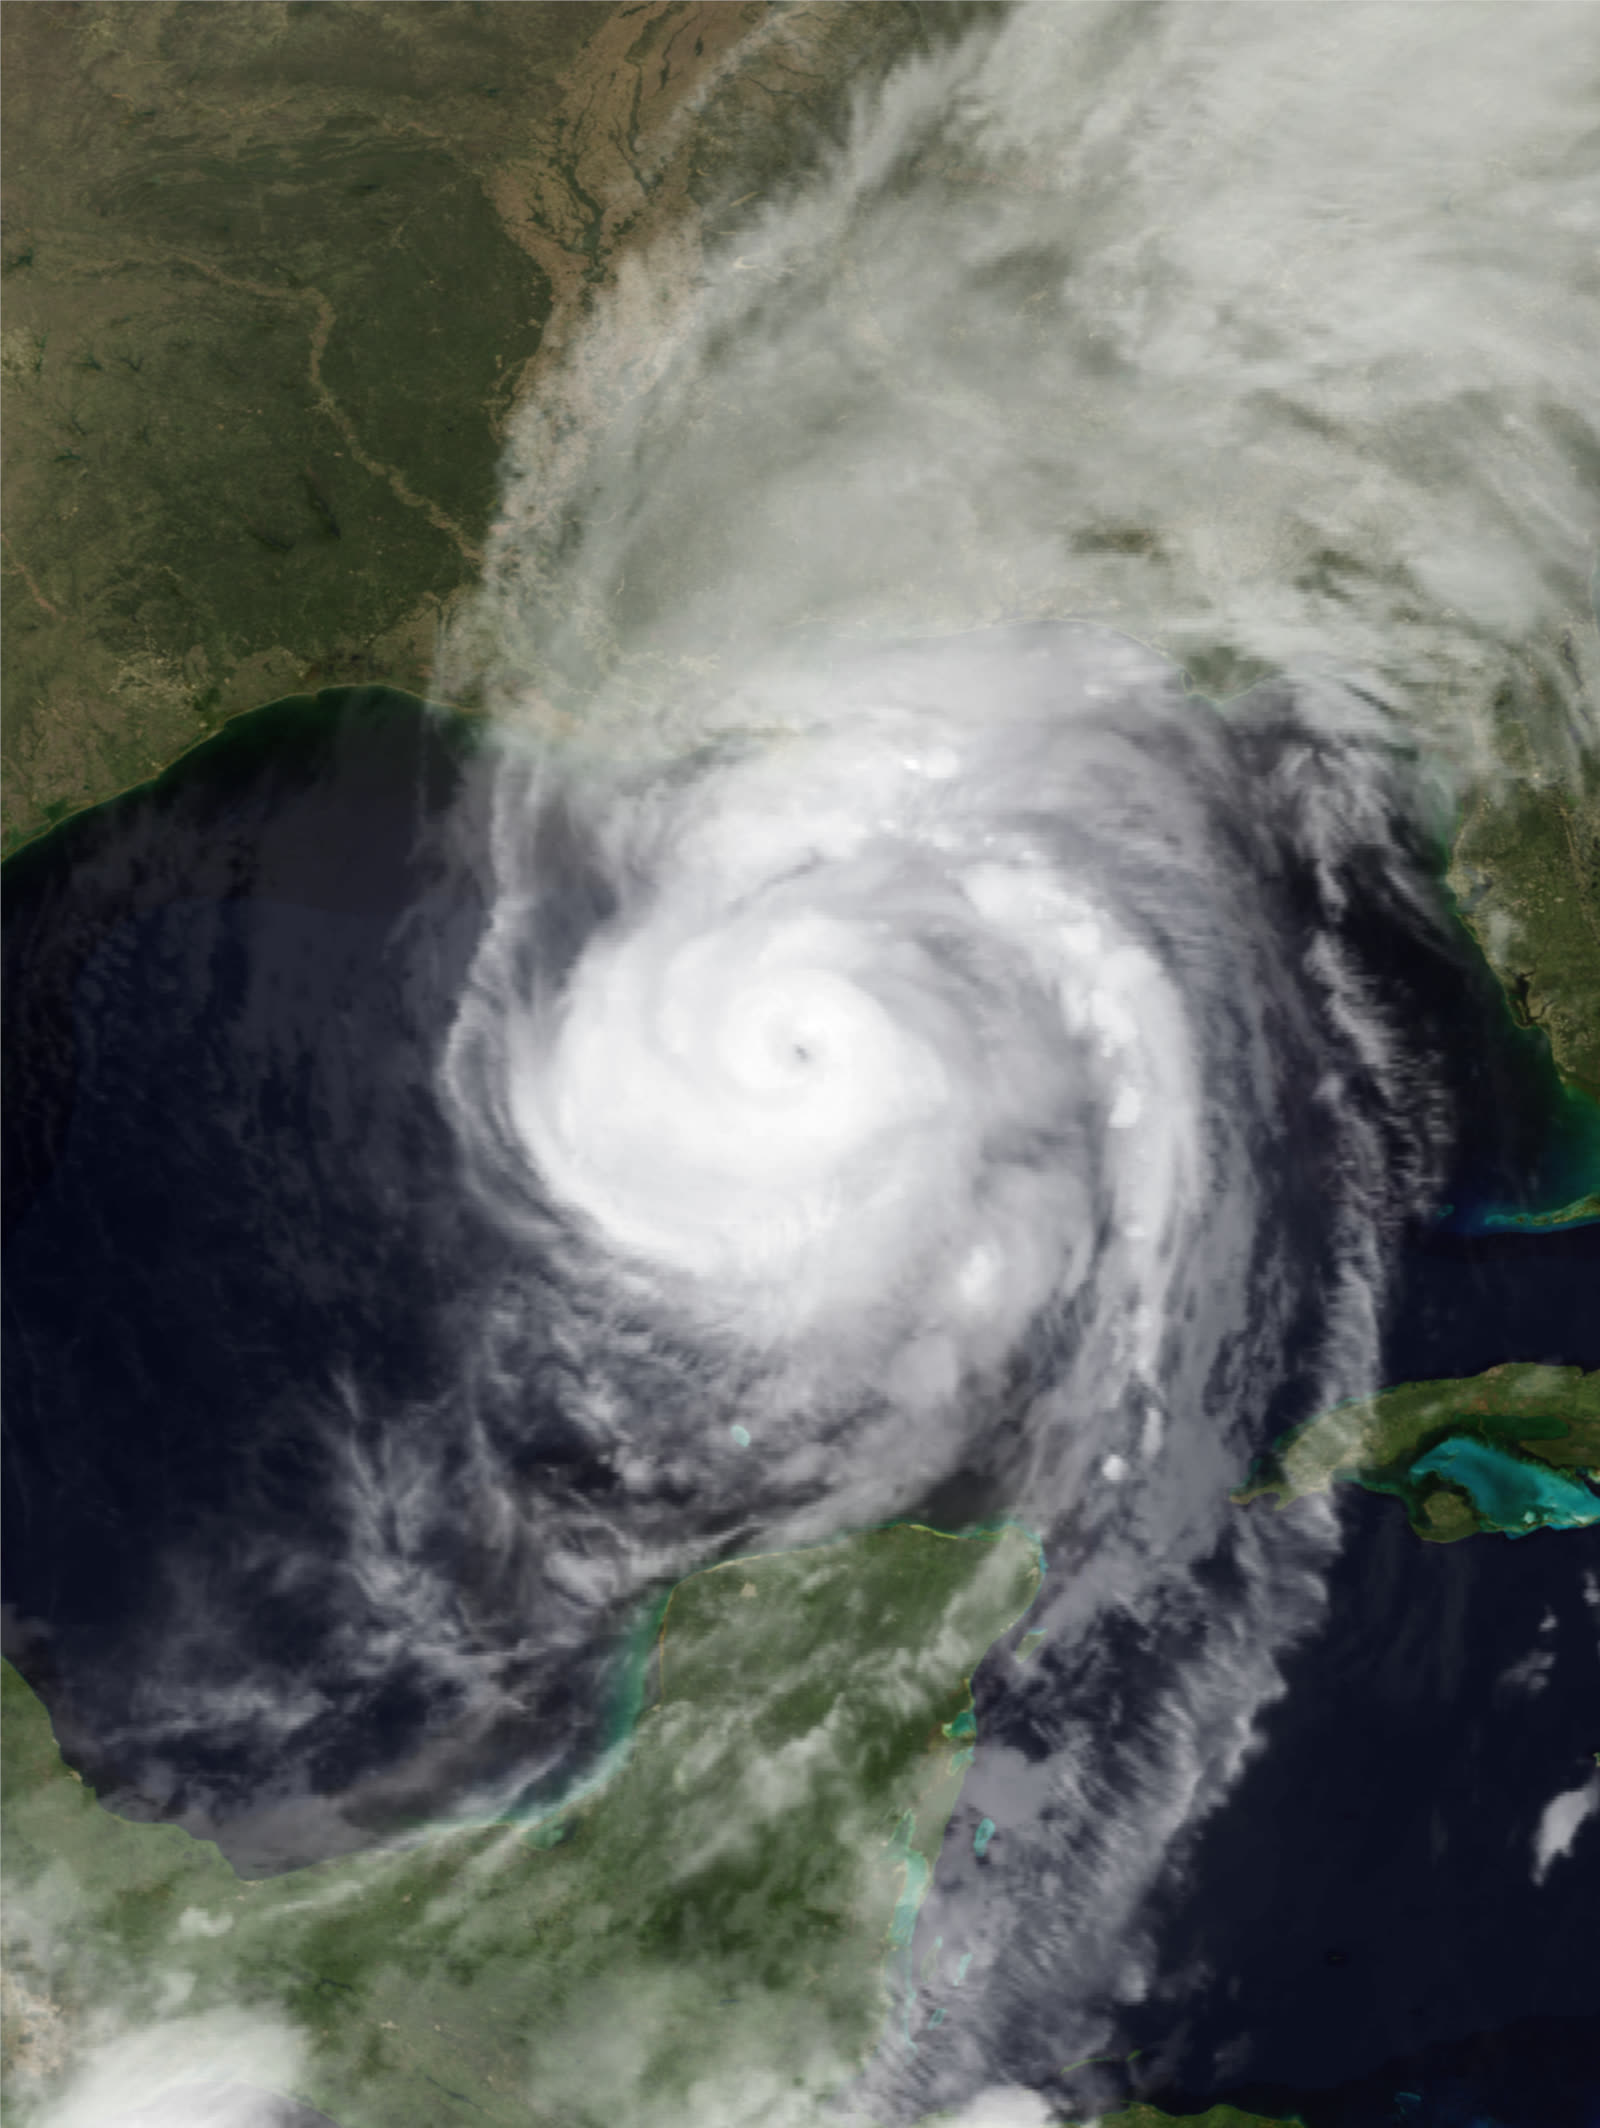
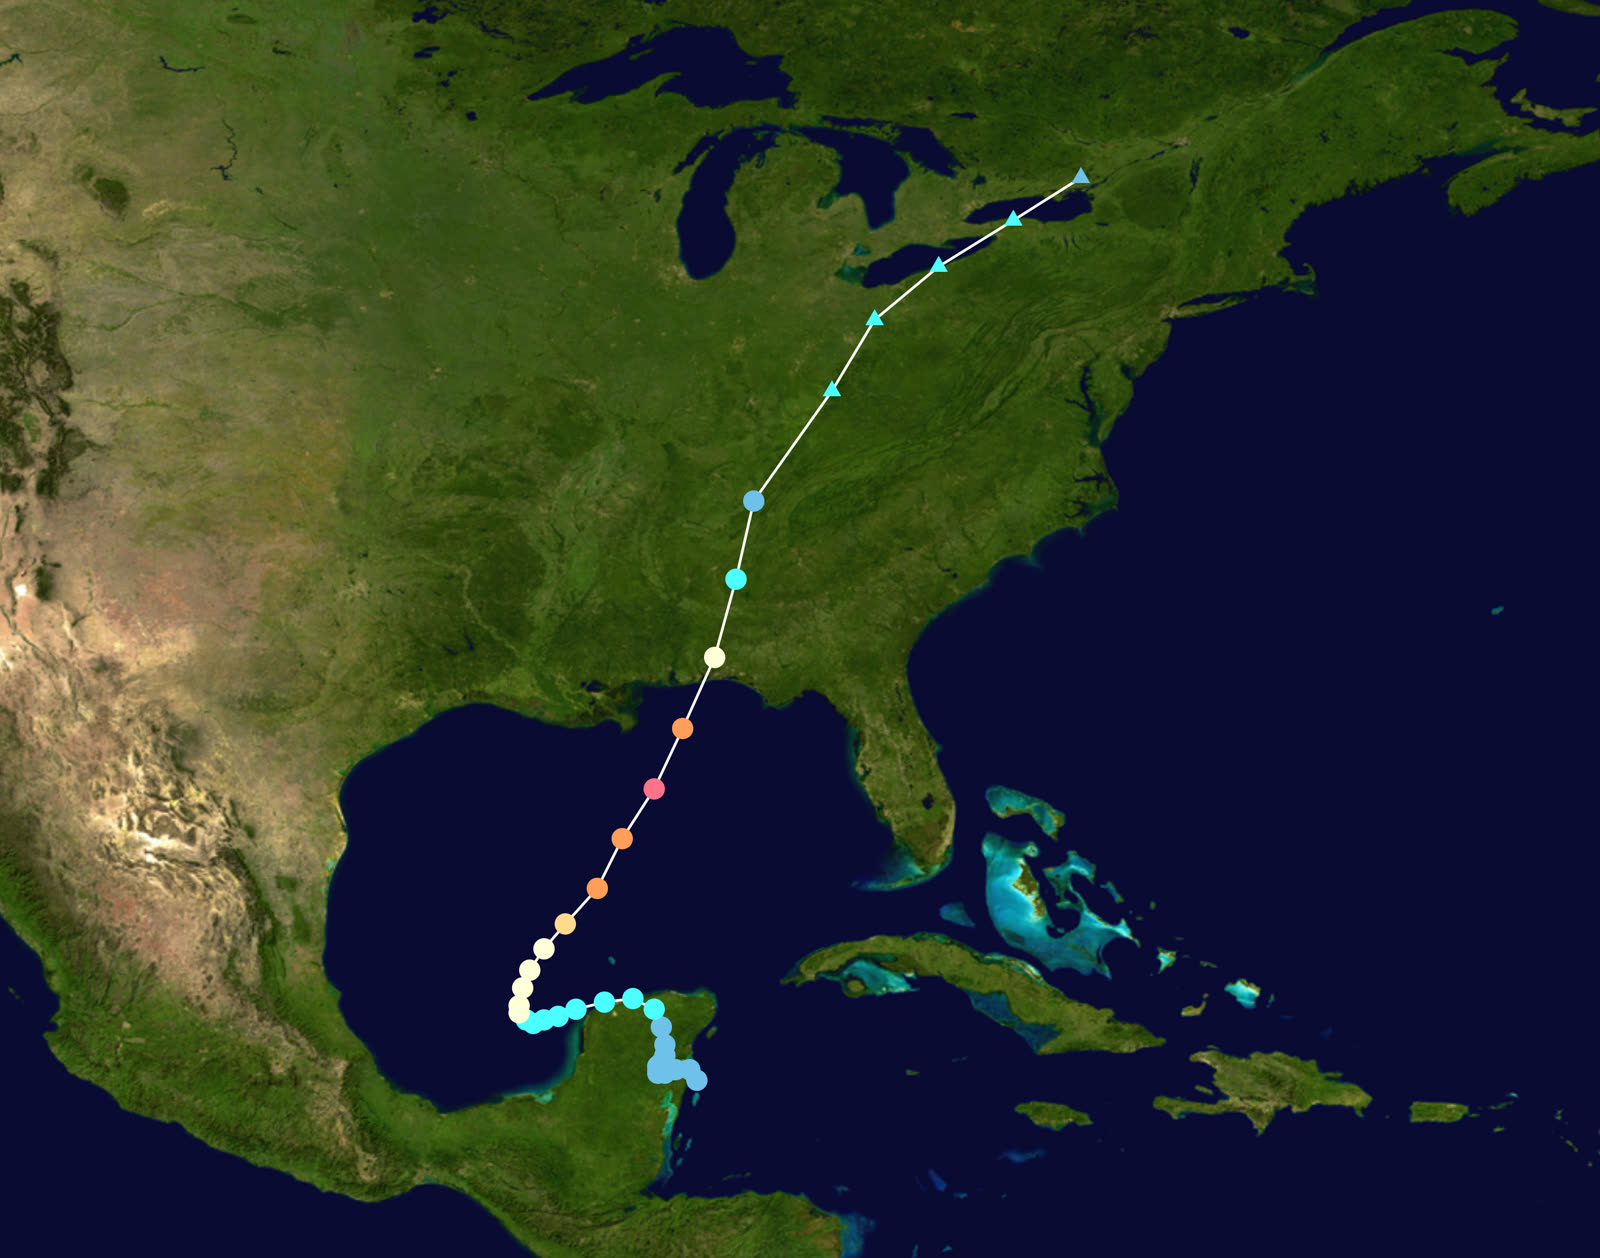
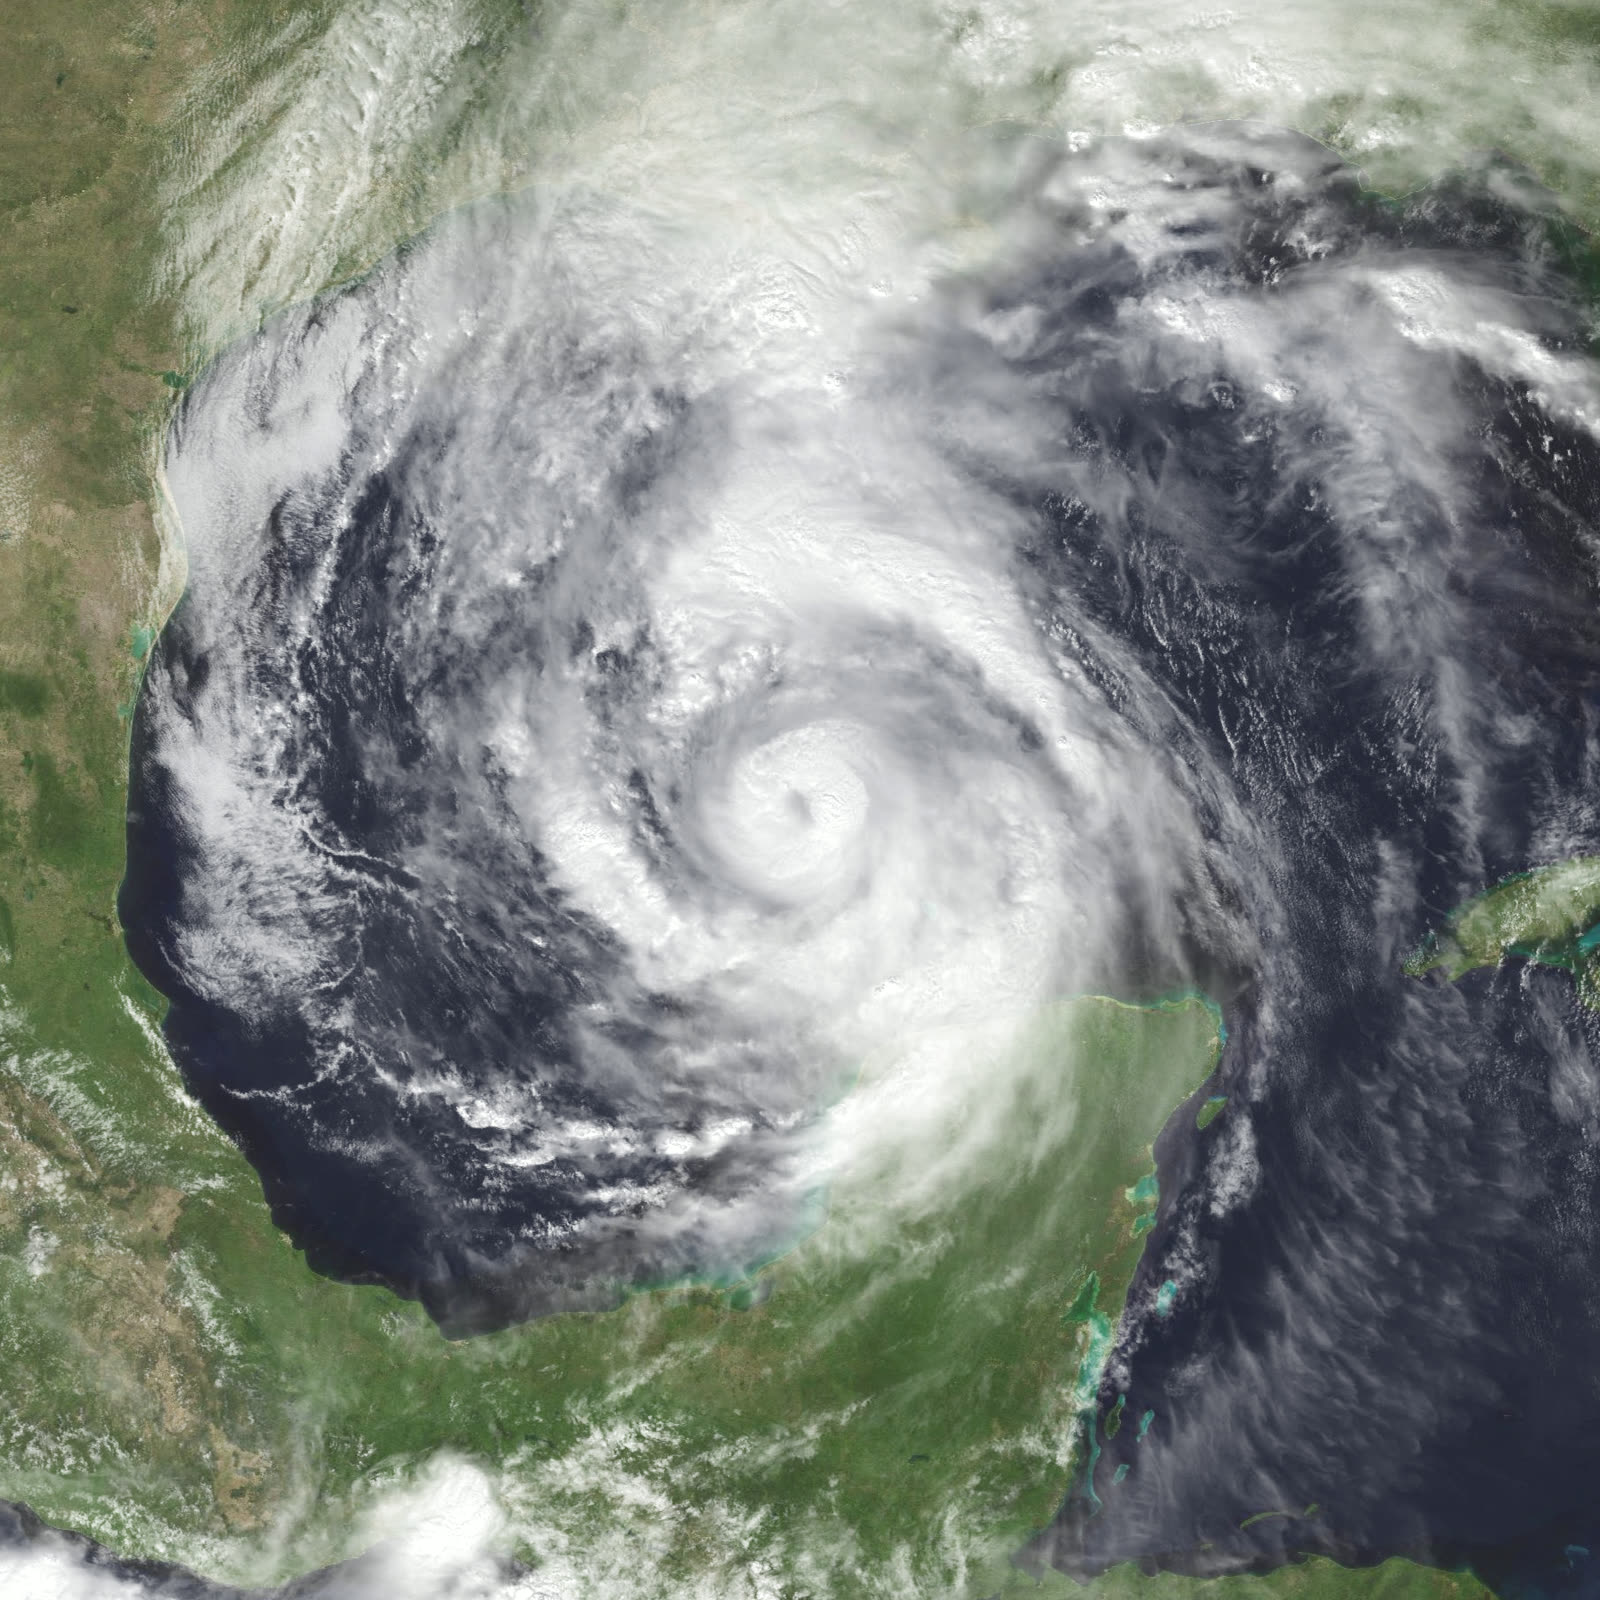
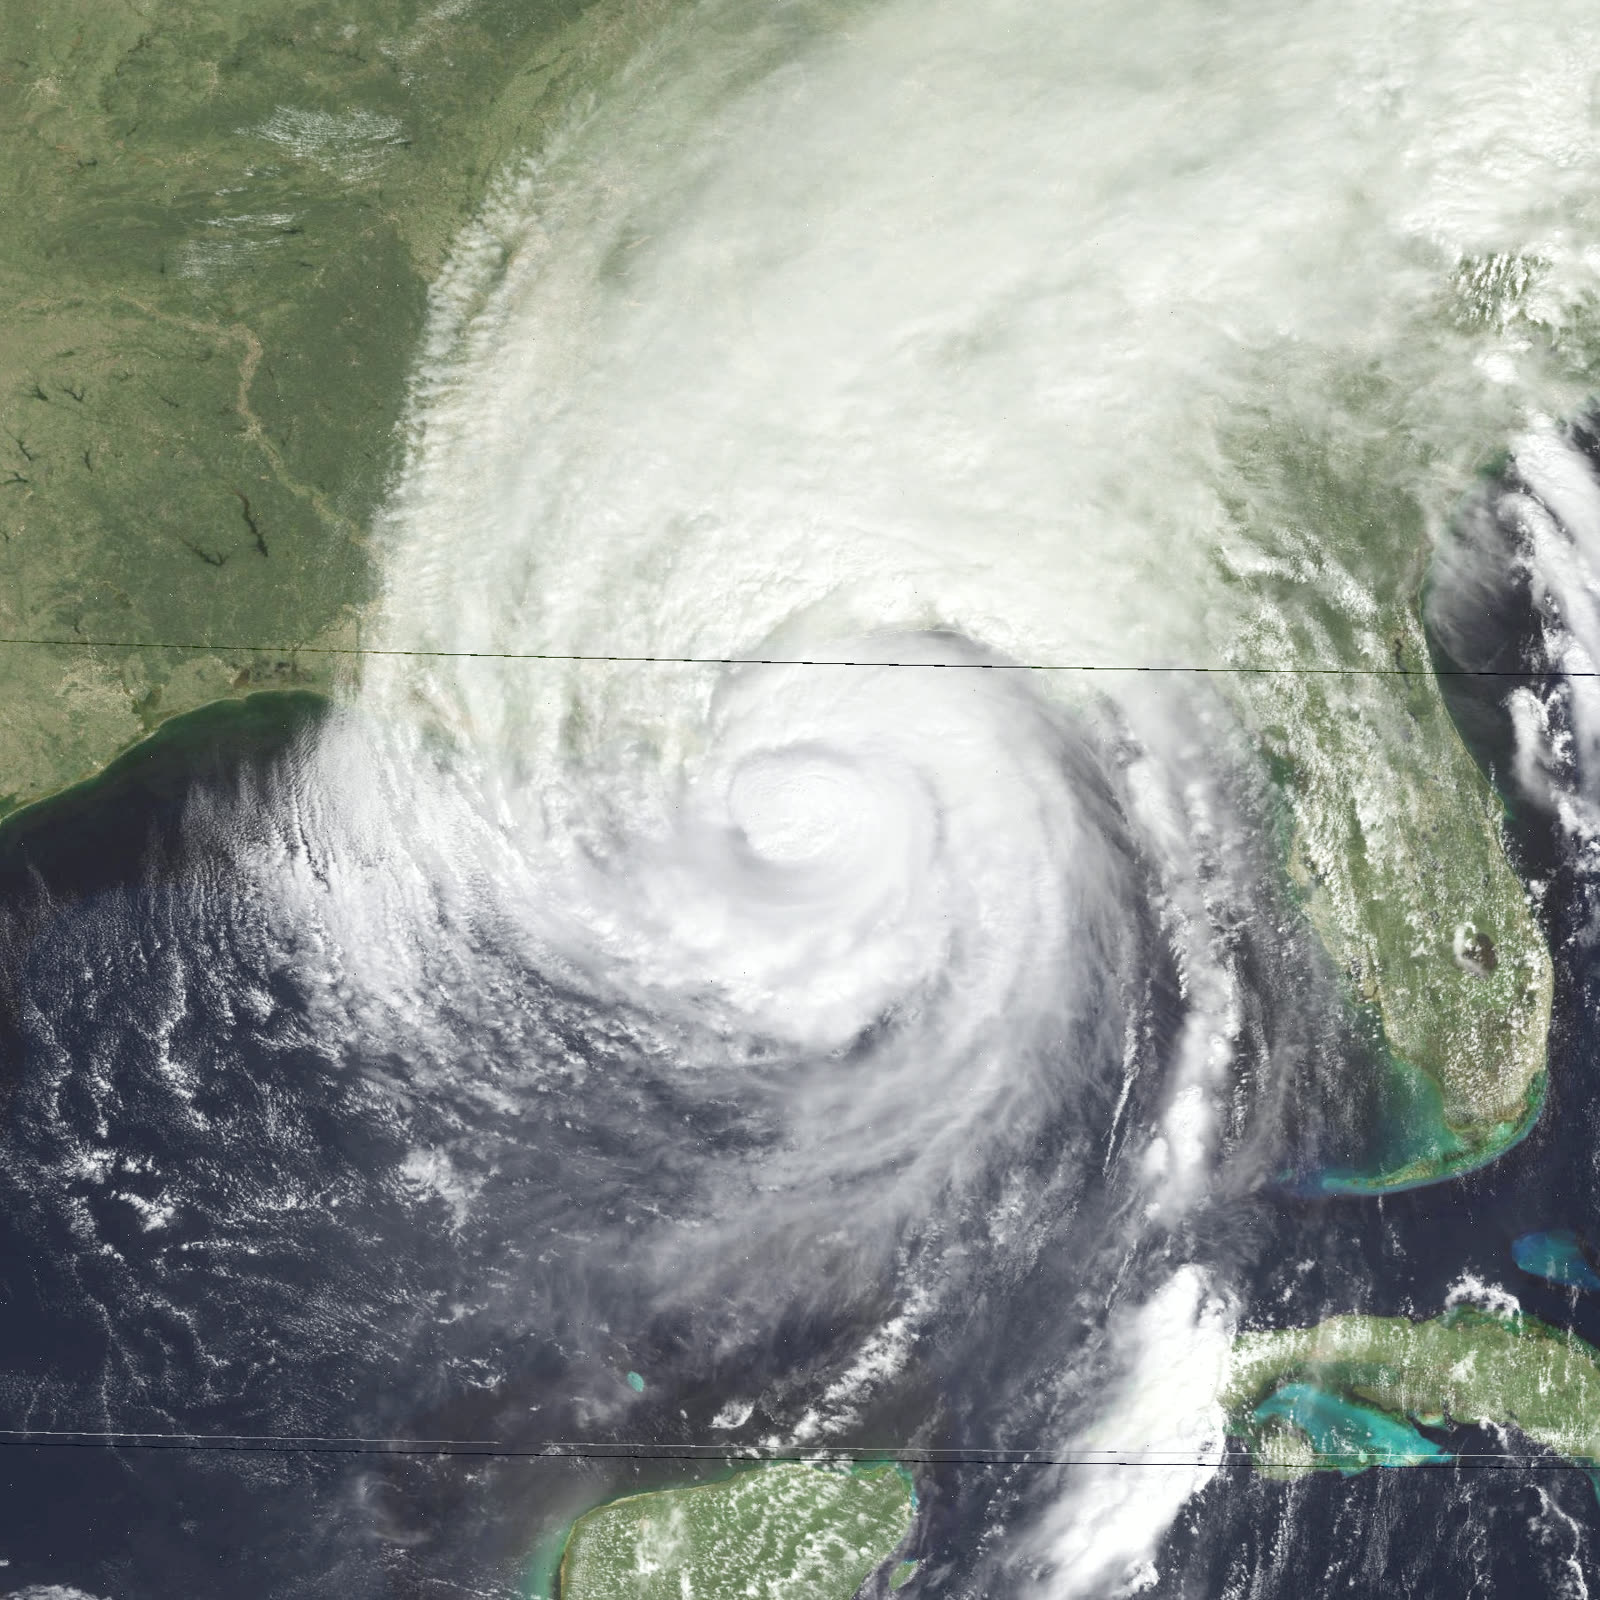
Opal formed near the Yucatan on September 27, 1995, and spent days as a disorganized rainmaker, killing 50 people in Guatemala and Mexico. Then it moved over a warm eddy in the central Gulf and became a different storm.
Overnight on October 3-4, Opal jumped from Category 1 to Category 4, peaking at 150 mph with a 916 mb pressure, at the time the most intense Category 4 Atlantic hurricane on record by pressure. The intensification happened while the Panhandle slept; morning evacuees hit gridlock on US 98 and I-10 as the storm accelerated north at more than 20 mph.
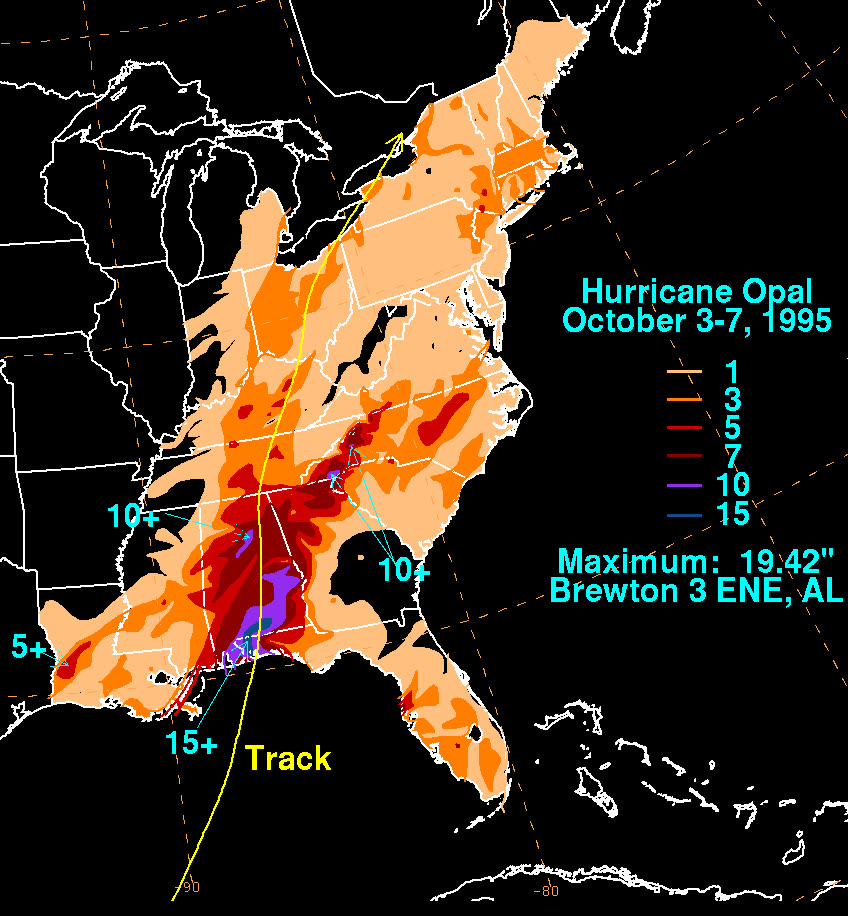
An eyewall replacement cycle weakened Opal to Category 3 (115 mph) before landfall between Pensacola Beach and Navarre Beach around 6 p.m. CDT on October 4. The wind weakened; the surge did not. Water built during the Category 4 phase came ashore at 8 to 15 feet along the Panhandle. Opal raced inland, stayed at hurricane strength deep into Alabama, and dissipated over Ontario on October 6. US toll: 9 direct deaths, about $5.1 billion in damage, $2.1 billion of it in Florida.
The damage
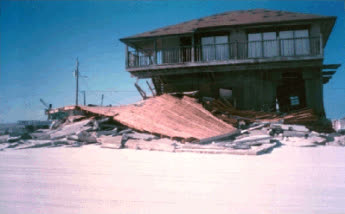
Surge did the signature damage. Nearly a mile of US 98 near Eglin Air Force Base was destroyed outright. Gulf-front structures from Pensacola Beach through Navarre, Fort Walton Beach, and Destin were gutted or swept off foundations; across Escambia, Santa Rosa, Okaloosa, and Bay counties, nearly 300 homes were destroyed and 1,000 more took major damage.
The contrast with 1975 was measurable: post-Opal engineering surveys found buildings permitted under the post-Eloise Coastal Construction Control Line, elevated, pile-founded, behind the setback, survived at far higher rates than pre-CCCL construction on the same beaches. Inland, wind was the story: a then-record 476,000 customers lost power in Alabama, and Atlanta lost more than 4,000 trees.
The insurance aftermath
Opal hit an insurance market still in triage from Andrew (1992). Insured US losses reached about $2.1 billion, at the time one of the five costliest US hurricanes for insurers, landing on carriers already shrinking their Florida coastal books.
The stress showed in the state's residual mechanisms. The Florida Windstorm Underwriting Association, the wind pool covering coastal properties private carriers refused, levied $117 million in assessments on the industry for its 1995 losses from Erin and Opal. Those assessments were passed through to policyholders statewide as surcharges, an early demonstration of how Florida socializes coastal wind losses. The FWUA then grew rapidly after 1995: eligibility expansions, continued unavailability of private windstorm coverage in the most exposed areas, and carriers' "accelerated exposure reduction" plans pushed more Panhandle and coastal risk into the pool. That growth track led to the FWUA's 2002 merger into Citizens Property Insurance Corporation, today's insurer of last resort.
Claims themselves split on the wind/water line. With surge doing the beachfront destruction and landfall winds a category below the surge's strength, carriers attributed slab-level losses to excluded flood; NFIP policies, where owners had them, capped out well below Gulf-front rebuild costs. The evacuation failure also had a paper trail: post-storm reviews of the gridlock reshaped Panhandle evacuation planning and clearance-time modeling.
Federal recovery ran through DR-1069, declared the day of landfall.
What policyholders learned
- Surge follows peak strength, not landfall category. Opal's "weakened" Cat 3 label did not shrink the Cat 4 surge; owners who assumed wind-policy coverage for water damage met the flood exclusion.
- Slab cases became causation fights. Where only a foundation remained, carriers presumed excluded surge; owners with pre-storm photos, elevation certificates, and wind-timing evidence recovered more.
- Wind-pool coverage came with statewide strings. FWUA policyholders and every other Florida insured paid post-Opal assessments, pool coverage is real but its costs are socialized and its limits matter.
- CCCL-era construction paid off in survival and in claims. Elevated, post-1975-code buildings both survived better and produced cleaner wind-versus-water claim files.
- NFIP limits lag Gulf-front values. Flood policies capped at program limits left large uninsured gaps on high-value beachfront homes, a gap repeated in every Panhandle storm since.
Not legal advice; consult an attorney about your specific claim. Damage figures are nominal (not inflation-adjusted) unless noted.