
ACTIVE STORM TRACK →
PROPERTY-INSURANCE CLAIM HELP FL CITIESSC CITIESGUIDESTATESNEWSSITE MAPABOUT
HurricaneLaw.Pro, Florida and South Carolina property insurance claim resource HURRICANELAW.PRO
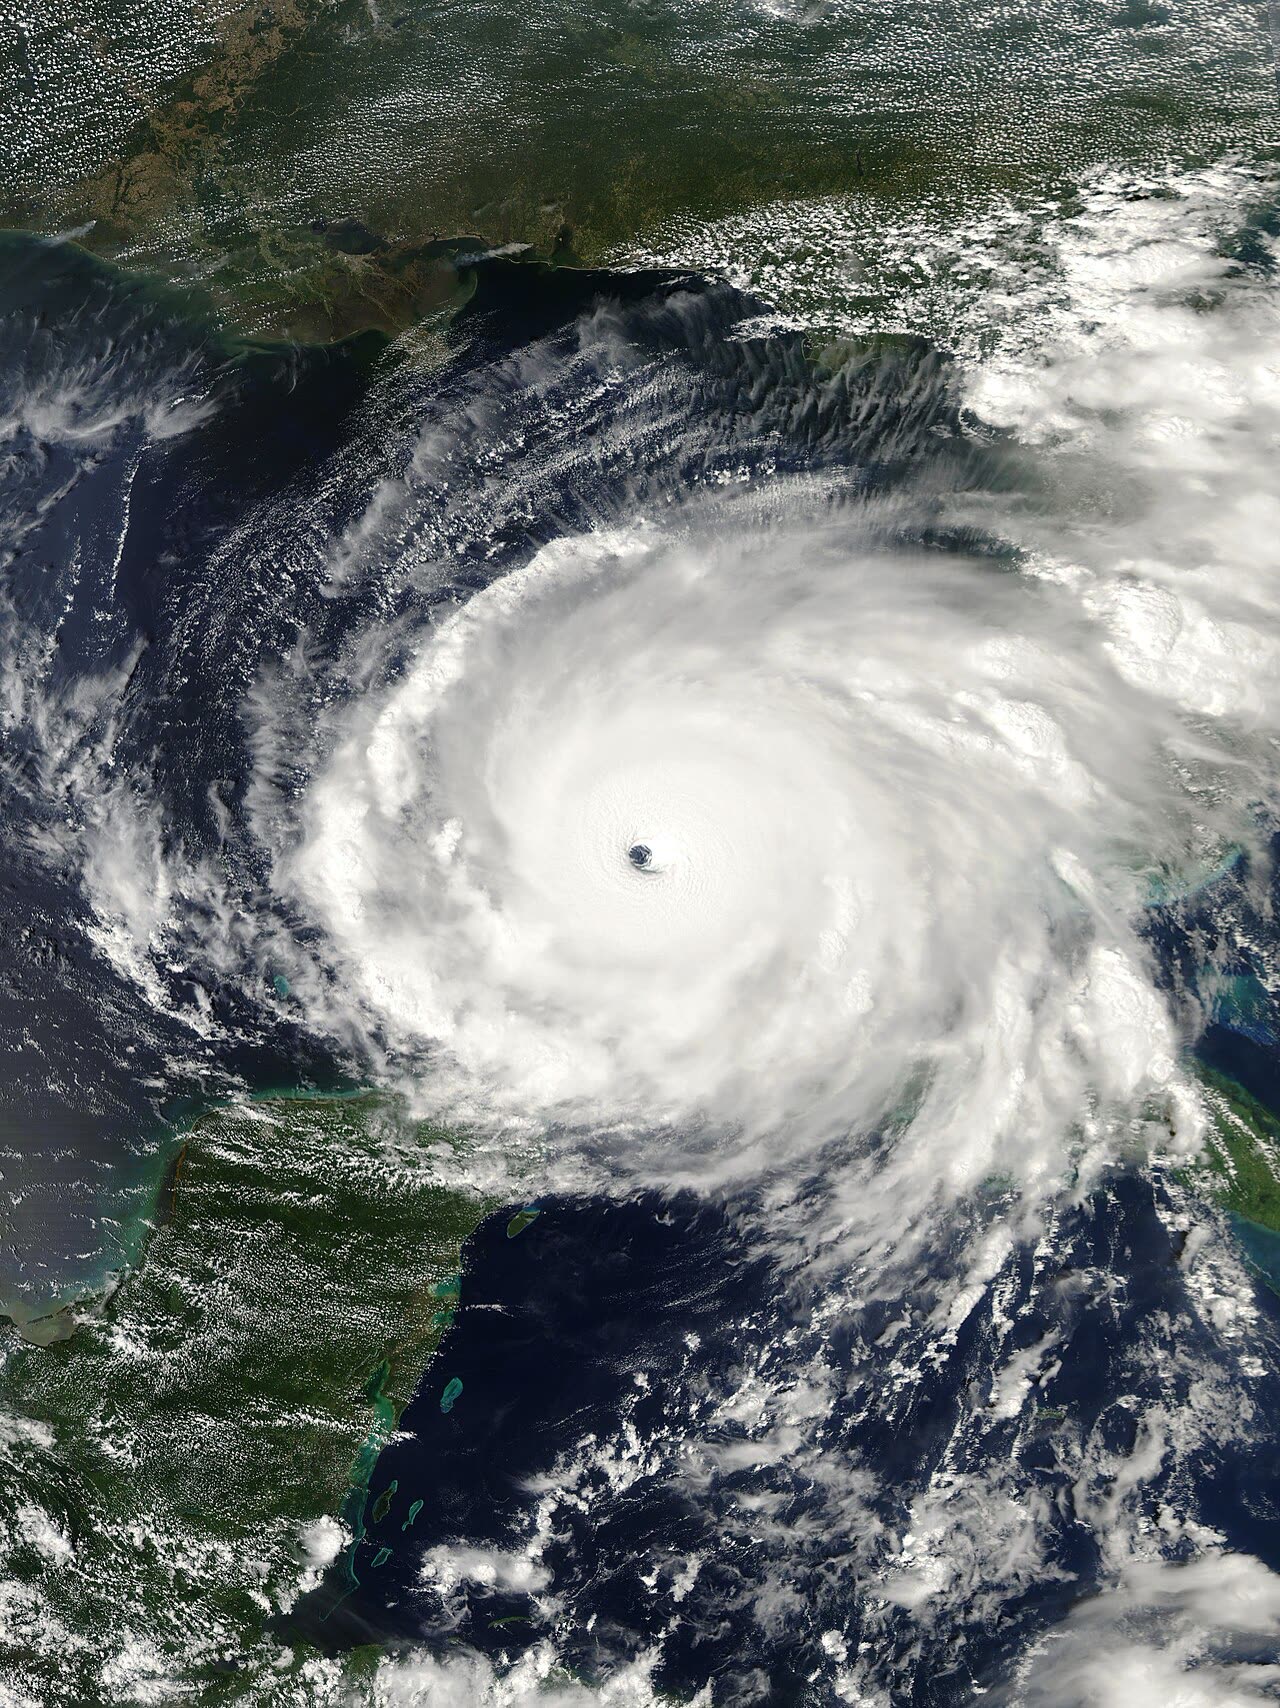
Rita near peak Category 5 intensity, 180 mph, 895 mb, in the central Gulf, September 21, 2005
STORM ARCHIVE / 2005 LANDFALL 29.7°N 93.6°W
CAT 3 AT LANDFALL PEAK CAT 5 US · 2005 · 180 mph

Hurricane Rita

Landfall: Johnson Bayou, LA (Texas-Louisiana line) · 2005-09-24. Rita caused $18.5B in damage but only $5.6B in insured payouts, the surge that leveled Cameron Parish was excluded as flood

NOAA / NESDIS
AT LANDFALL
CAT 3
PEAK INTENSITY
CAT 5 · 180 mph
PRESSURE
895 mb (peak)
STORM SURGE
up to 15 ft
DAMAGE
$18.5B
DEATHS
7 direct
01 THE PATH

Where it hit, start to finish

TRACK · HURRICANE RITANOAA / NHC (best-track data)
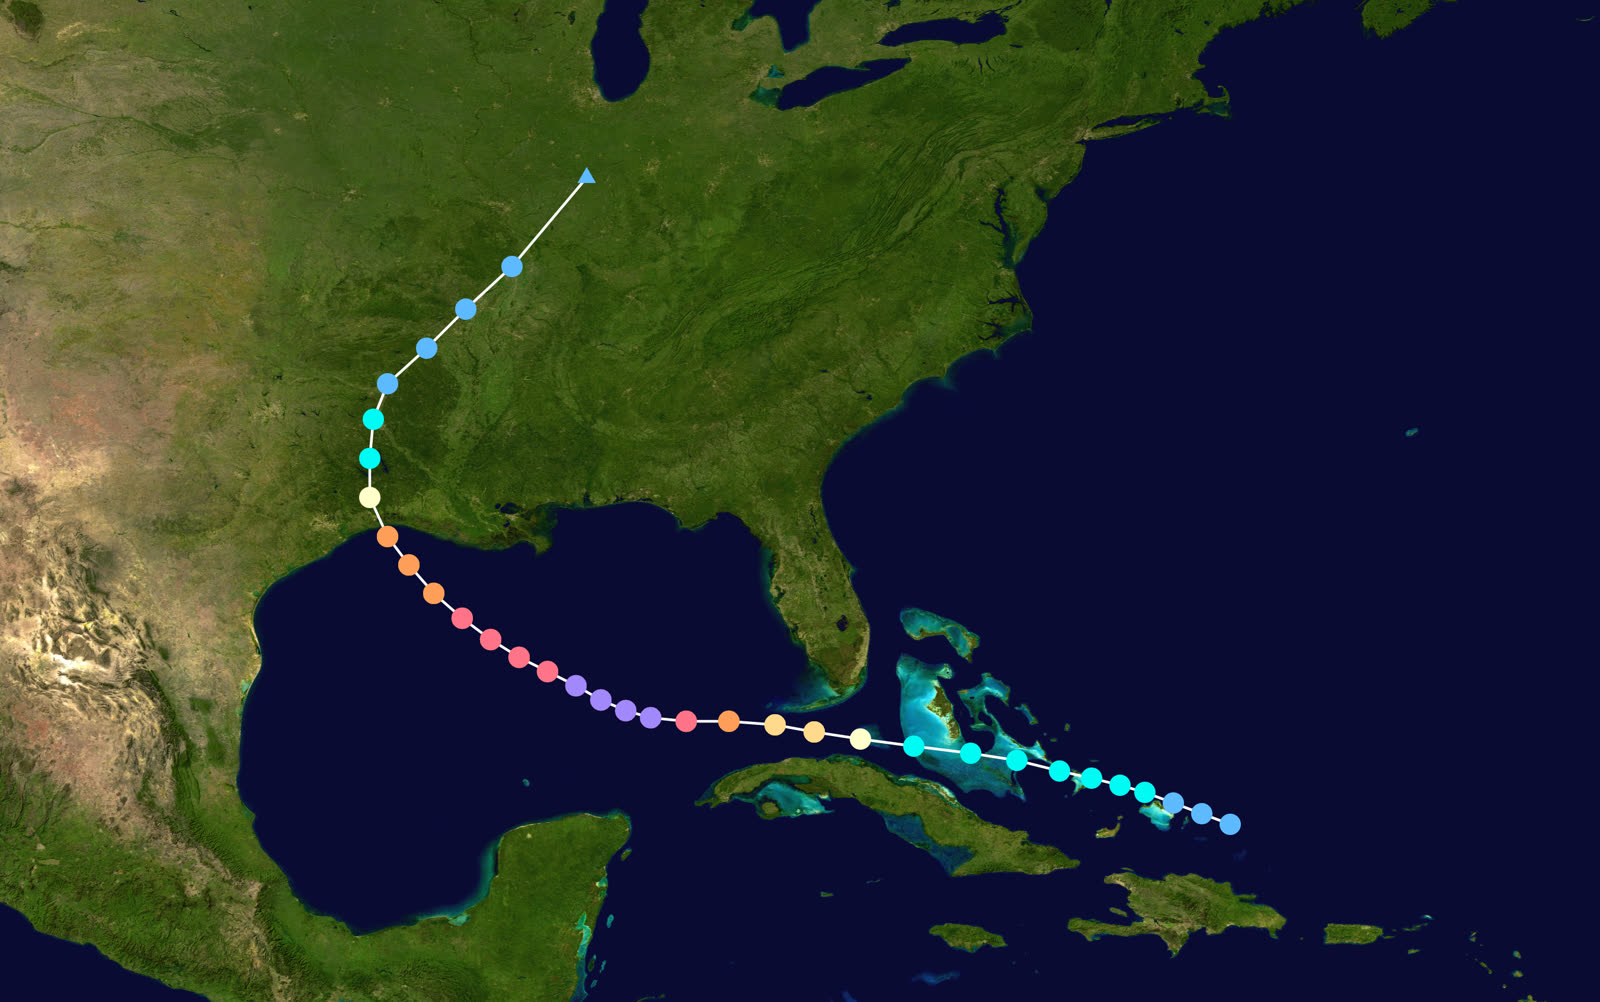
Best track and Saffir-Simpson intensity of Hurricane Rita, September 18-26, 2005
Florida Straits / Key West
CAT 2 PASS SOUTH OF THE KEYS

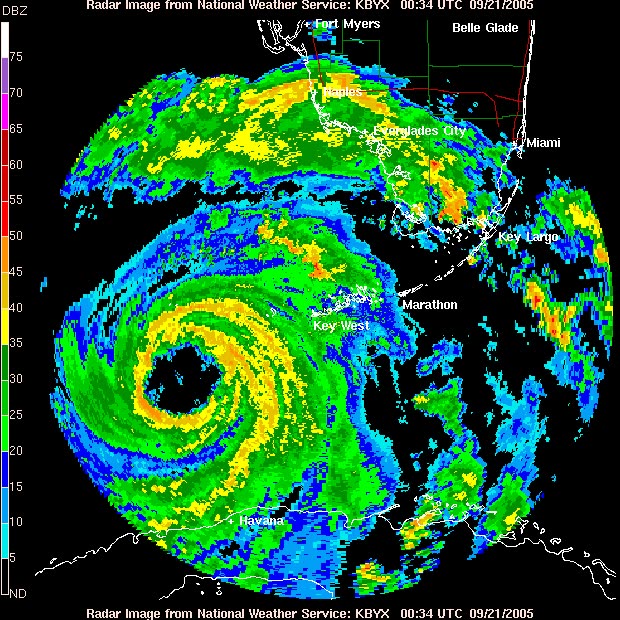
Rita formed near the Turks and Caicos on September 18 and passed just south of Key West on September 20 as a Category 2, flooding parts of the lower Keys.

Central Gulf of Mexico
895 MB, PEAK 180 MPH

Over the Gulf's warm Loop Current, Rita exploded to 180 mph and 895 mb on September 21-22, at the time the third-lowest pressure ever measured in an Atlantic hurricane, weeks after Katrina set the fourth.

Houston-Galveston, TX
EVACUATION OF ~3 MILLION

Forecast tracks near Houston triggered one of the largest evacuations in U.S. history. Gridlock, heat, and a bus fire killed far more people than the storm itself, most of Rita's death toll was indirect.

Johnson Bayou / Sabine Pass
CAT 3 LANDFALL, 115 MPH

Landfall came at 2:40 a.m. CDT September 24 at the Texas-Louisiana line as a Category 3 with 115 mph winds and a 937 mb pressure. Surge near 15 feet swept Cameron Parish; Holly Beach, Cameron, and Creole were largely destroyed.

New Orleans, LA
LEVEES OVERTOPPED AGAIN

Rita's surge overtopped patched Katrina levee breaches on September 23, re-flooding the Lower Ninth Ward before Rita ever made landfall 250 miles away.

Beaumont-Port Arthur, TX / inland LA
WIND AND INLAND FLOOD

Hurricane-force winds raked southeast Texas and southwest Louisiana; Vermilion Parish towns like Erath and Delcambre flooded. Rita dissipated over Arkansas September 26. Total: $18.5 billion in damage, 7 direct deaths.

02 THE RECORD IN IMAGES
ALL IMAGERY U.S. GOV / PUBLIC DOMAIN
RADAR NOAA / NWS Key West
Key West radar as Rita passed south of the Florida Keys as a Category 2, September 20-21, 2005
MAP NOAA / WPC
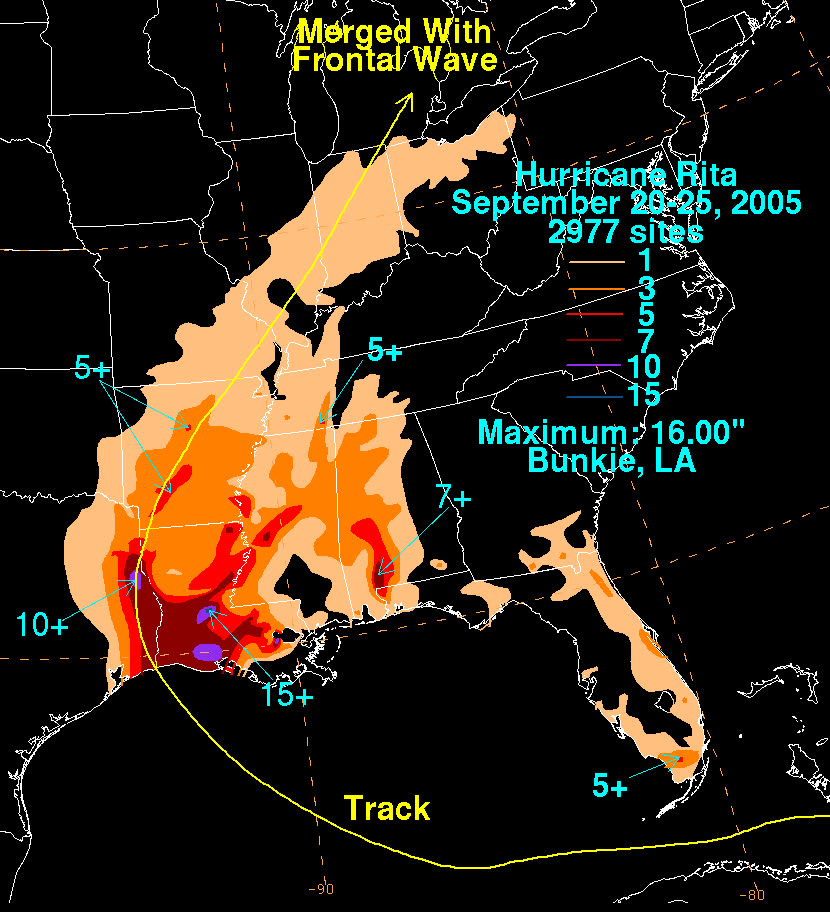
Storm-total rainfall from Rita across Louisiana, Texas, and the lower Mississippi Valley

The storm

Rita formed near the Turks and Caicos on September 18, 2005, 20 days after Katrina, and crossed the Florida Straits as a Category 2, passing just south of Key West. Over the central Gulf it intensified as fast as any storm on record to that point: 180 mph winds and a 895 mb pressure on September 21-22, then the third-lowest pressure ever measured in an Atlantic hurricane.

With Katrina three weeks old, roughly three million people fled the Texas coast, one of the largest evacuations in U.S. history. The evacuation itself proved deadlier than the storm: gridlock, heat, and a bus fire near Dallas that killed 23 nursing-home evacuees.

Rita weakened before landfall and came ashore at 2:40 a.m. CDT on September 24 near Johnson Bayou, Louisiana, at the Texas-Louisiana line, Category 3, 115 mph, 937 mb. Surge near 15 feet inundated Cameron Parish. A day earlier, Rita's outer surge had overtopped patched levees in New Orleans and re-flooded the Lower Ninth Ward. The storm dissipated over Arkansas on September 26. Toll: $18.5 billion in damage, 7 direct deaths, and well over 100 total including evacuation-related fatalities.
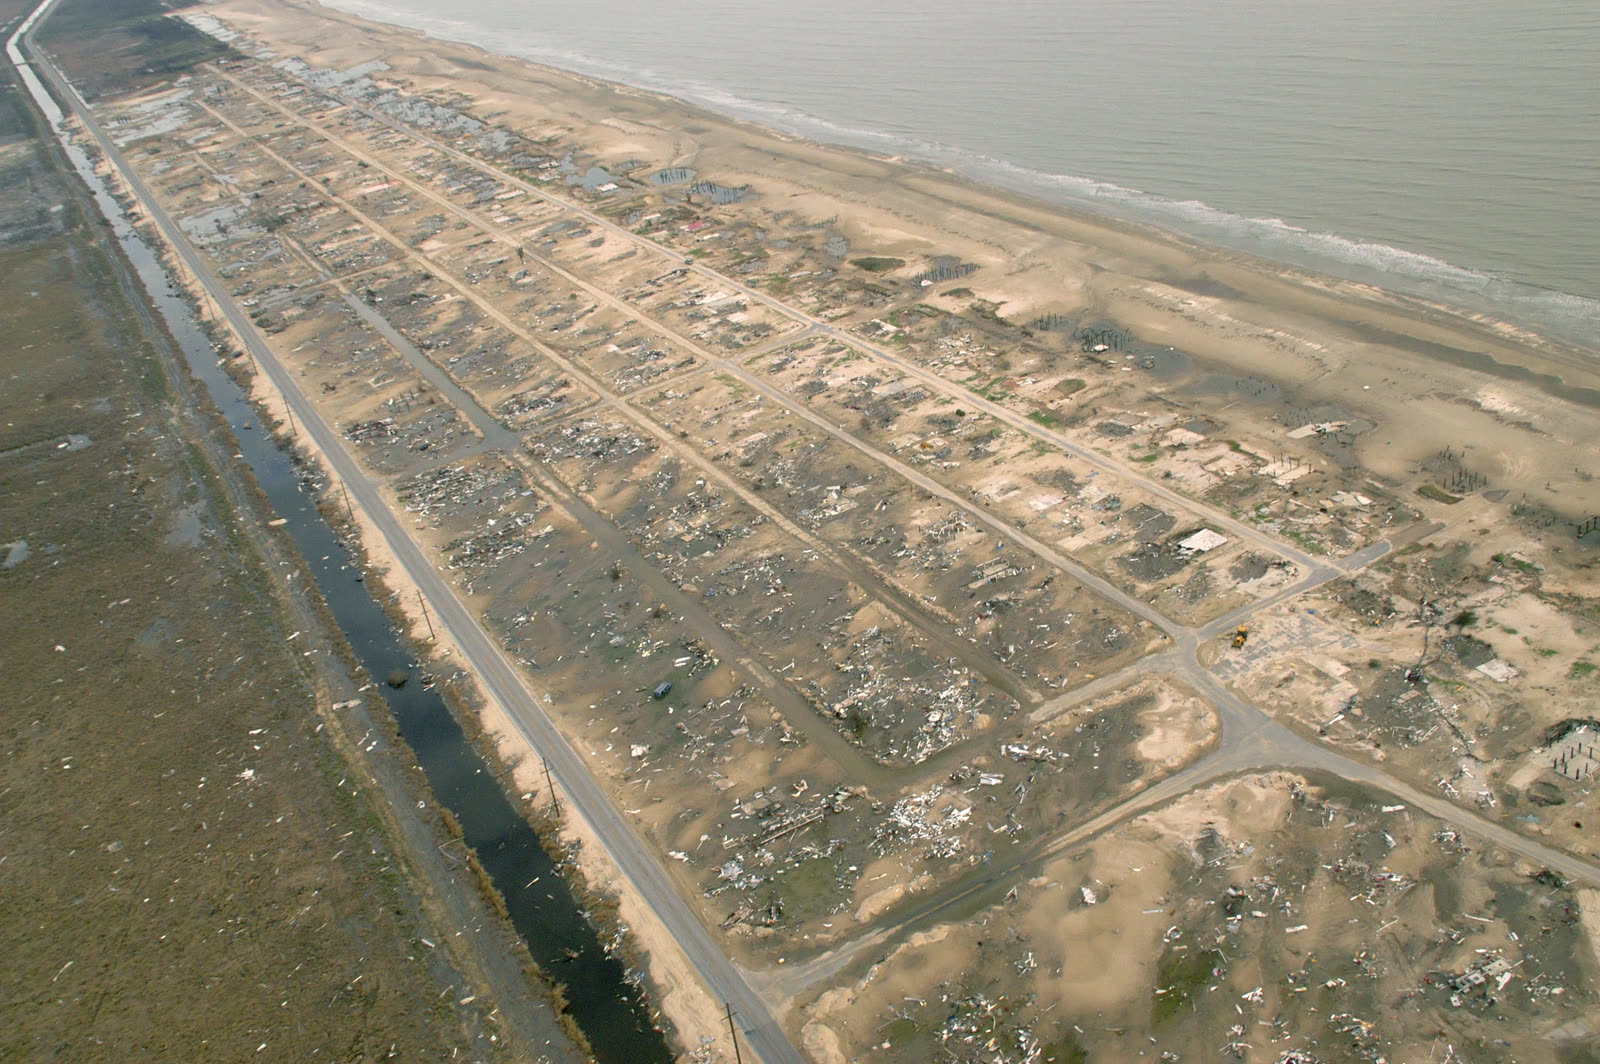
Holly Beach, LA, a community of roughly 500 structures leveled by Rita's surge, photographed weeks later
Holly Beach, LA, a community of roughly 500 structures leveled by Rita's surge, photographed weeks later FEMA / Marvin Nauman

The damage

Cameron Parish took the core. Holly Beach, a beach community of about 500 structures, was leveled so completely that little debris remained. In the town of Cameron, roughly 90 percent of structures were damaged or destroyed; Cameron High School was surge-wrecked and demolished. Creole and Grand Chenier fared similarly. Inland, surge pushed up bayous into Vermilion Parish, flooding Erath, Delcambre, and Abbeville-area communities.

On the Texas side, Beaumont and Port Arthur took sustained hurricane-force wind: roofs opened, trees down region-wide, power out for weeks across the Golden Triangle. Offshore, Rita and Katrina together wrecked more than 100 Gulf oil and gas platforms.
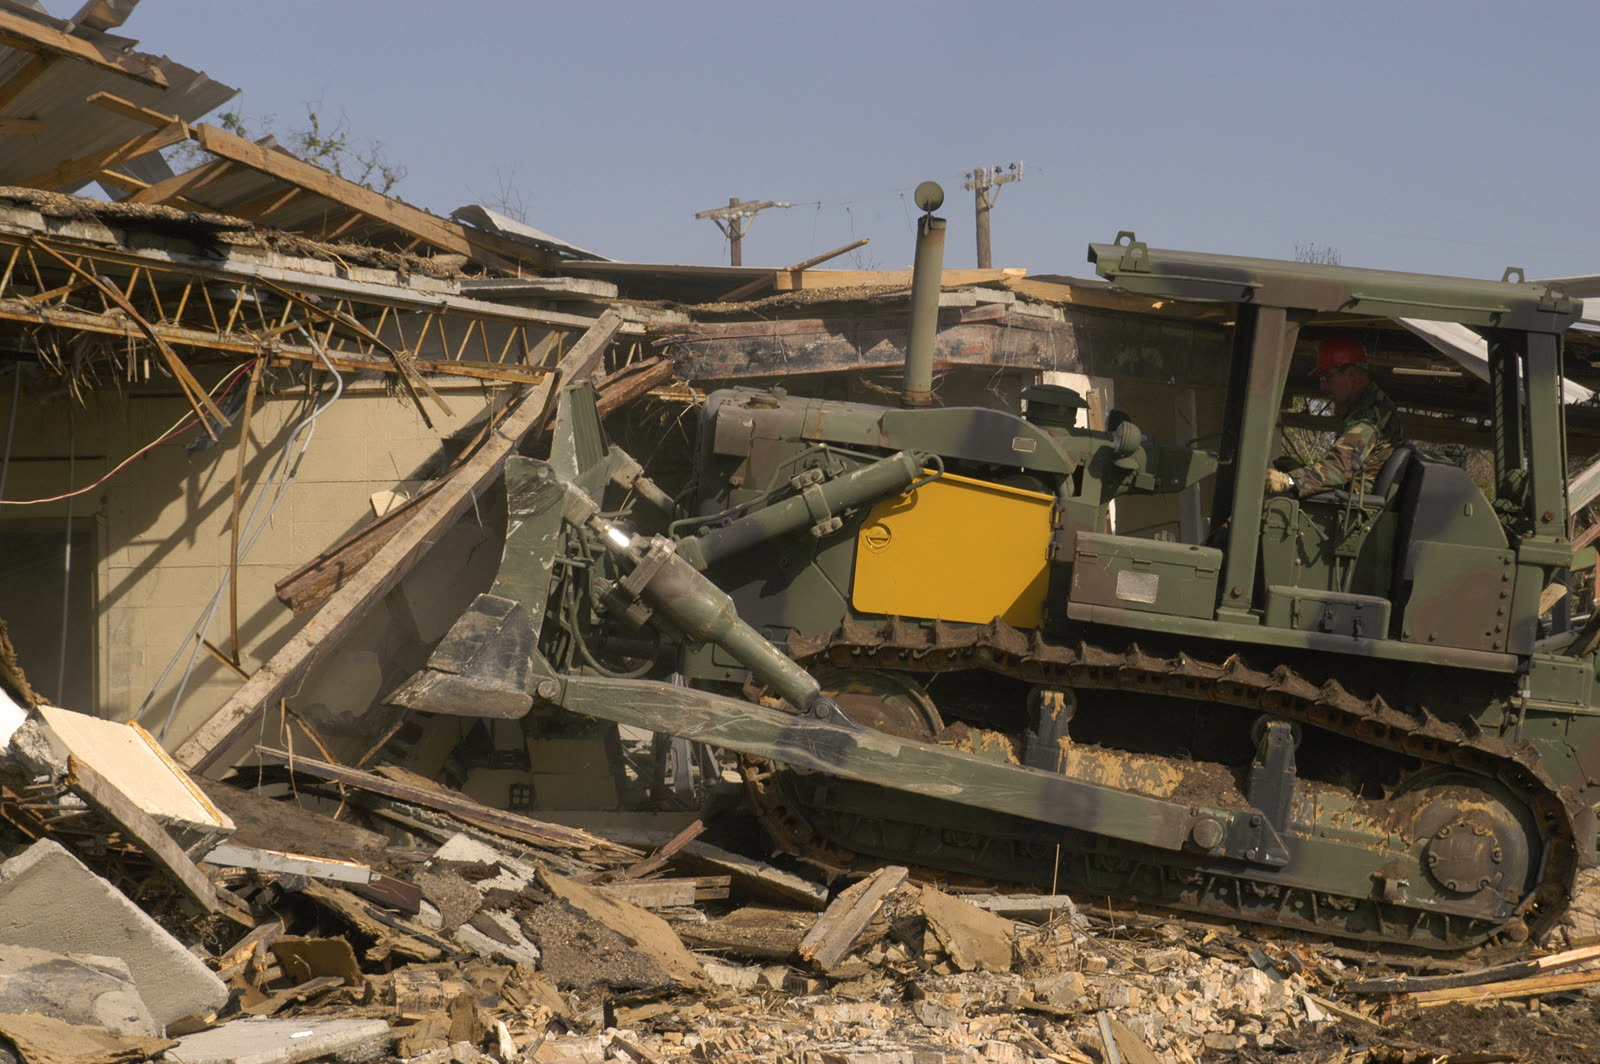
Cameron High School, severely damaged by Rita's tidal surge and slated for demolition, November 2005
Cameron High School, severely damaged by Rita's tidal surge and slated for demolition, November 2005 FEMA

The insurance aftermath

Rita produced $18.5 billion in total damage but only about $5.6 billion in insured onshore property losses, a gap driven by geography and the flood exclusion. The hardest-hit parishes were rural, and the worst destruction was storm surge, which homeowners policies exclude as flood. In lower Cameron Parish, NFIP take-up was thin; many families whose homes were slabbed had no policy responding at all.

The wind-versus-water fight that defined Katrina litigation ran on the same track in southwest Louisiana. Where a home vanished from its slab, carriers attributed the loss to excluded surge; policyholders argued wind destroyed the structure before water arrived, and that carriers bore the burden of proving how much damage the excluded peril caused. Anti-concurrent-causation clauses, barring coverage when wind and water act together, were litigated across Louisiana and Mississippi dockets for years.

Rita claims also landed on an industry already consumed by Katrina. Adjusters were scarce, inspections slow, and southwest Louisiana policyholders reported waits of months while national attention and resources stayed 200 miles east, the origin of Rita's "forgotten storm" label.

The federal-state response merged the two storms. Louisiana's Road Home program, funded by Congress for Katrina and Rita, paid rebuilding grants that were reduced dollar-for-dollar by insurance recoveries, so underpaid insurance claims fed directly into smaller grants. Grant conditions requiring elevation later produced thousands of state clawback lawsuits against homeowners who used the money for repairs instead; Louisiana dropped the remaining suits when the program closed in 2023.
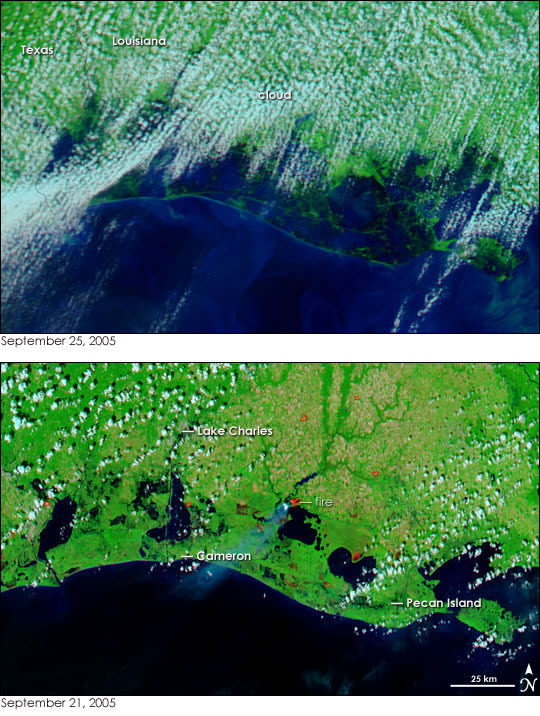
Satellite view of southwest Louisiana coastal flooding the day after landfall, September 25, 2005
Satellite view of southwest Louisiana coastal flooding the day after landfall, September 25, 2005 NASA

What policyholders learned

  • The flood exclusion decided more outcomes than the storm did. Surge-destroyed homes without NFIP coverage recovered little; wind-damaged homes with intact documentation recovered far more.
  • Slab cases turned on proof of wind-first damage. Policyholders with pre-storm photos, neighbor testimony, and debris-pattern evidence preserved wind claims; those without were defaulted into the surge exclusion.
  • A second-place disaster gets second-place adjusting. Rita claimants waited behind Katrina's queue; written demands, claim diaries, and state complaint filings were the tools that moved stalled files.
  • Grant programs count insurance money. Road Home reduced awards by amounts insurers paid, accepting a lowball settlement lowered total recovery twice.
  • Deadlines did not pause for the chaos. Louisiana's contractual and statutory limitation periods kept running for Rita claims even while the region was displaced.

Not legal advice; consult an attorney about your specific claim. Damage figures are nominal (not inflation-adjusted) unless noted.

AT LANDFALL · HURRICANE RITA · 2005
up to 15 ft
OF STORM SURGE · CAMERON PARISH
REPRESENTATIVE FOOTAGE
03 THE FULL RECORD

Every official record of Rita

Reports, imagery archives, flood data, and claims records, straight from the agencies.

FREE CASE REVIEW · NO FEE UNLESS YOU RECOVER
Rita claim denied?
CALL SC · 843-542-0454CALL FL · 813-588-0164FREE CLAIM REVIEW
RELATED GUIDES
HurricaneLaw.Pro, Florida and South Carolina property insurance claim resource HURRICANELAW.PRO

A comprehensive property-insurance claim resource for policyholders: denied and underpaid claims, coverage and bad-faith law, storm dossiers, carrier profiles, city guides, and the complete claims playbook. Florida and South Carolina.

▸ SEE THE FULL SITE MAP →
STORM ALERTS SOURCED FROM NOAA / NHC
SOUTH CAROLINA
496 Bramson Court, Suite 100
Mount Pleasant, SC 29464
CALL OR TEXT
FLORIDA
CALL OR TEXT
CLAIMS 9
BAD FAITH 7
DENIAL FILINGS
HOW CLAIMS GET DENIED
DENIAL DOCUMENTS
DENIALS, ANSWERED 9
COVERAGE 13
COMMERCIAL 8
ROOFS 8
TREES 5
DIRECTORIES
STORMS 51
WEATHER
NEWS & SITE 22
STORM ARCHIVE, CITIES & NEWS
Most recent below. Every storm dossier, city resource, and article is on its hub (linked at each heading) or the grouped site map →. All 73 carriers and 95 public-adjuster firms are in the Directories column above.
STORM ARCHIVE · 51 →
Hurricane Debby 2024Hurricane Helene 2024Hurricane Milton 2024Hurricane Idalia 2023Hurricane Ian 2022Hurricane Nicole 2022Hurricane Ida 2021Hurricane Laura 2020 View all 51 →
FLORIDA CITY RESOURCES · 37 →
Boca RatonBradentonCape CoralClearwaterCrestviewDaytona BeachDestinDunedin View all 37 →
SOUTH CAROLINA CITY RESOURCES · 8 →
BeaufortCharlestonColumbiaFlorenceGreenvilleHilton Head IslandMount PleasantMyrtle Beach
NEWS & UPDATES · 22 →

Coverage summaries, policy-language quotations, dollar figures, deadlines, and chart examples throughout this site are general information based on typical or standard policy forms and are illustrative only: they are not a quote, a guarantee of coverage, or a promise of any outcome. Every insurance policy is different: your own policy, endorsements, and state law control, so read your policy and confirm current statutes. Weather imagery courtesy of NOAA, the National Hurricane Center, and the National Weather Service. Legal services are provided by Halversen Law. Nothing on this site is legal advice; consult an attorney about your specific claim.

PrivacyTermsDisclaimerAboutContact
This site is not legal advice, and it is not a substitute for an attorney. Anything legal needs a licensed lawyer reading your policy and your facts. We recommend Halversen Law: the free claim review is the fastest way to get real eyes on your claim.
© 2026 HURRICANELAW.PRO · ALL RIGHTS RESERVED 27.9°N 82.5°W · ATLANTIC BASIN MONITOR
LAW FIRM
Halversen Law LICENSED · FLORIDA & SOUTH CAROLINA

Legal matters are handled by Halversen Law, a law firm licensed in Florida and South Carolina.

FREE CASE REVIEW