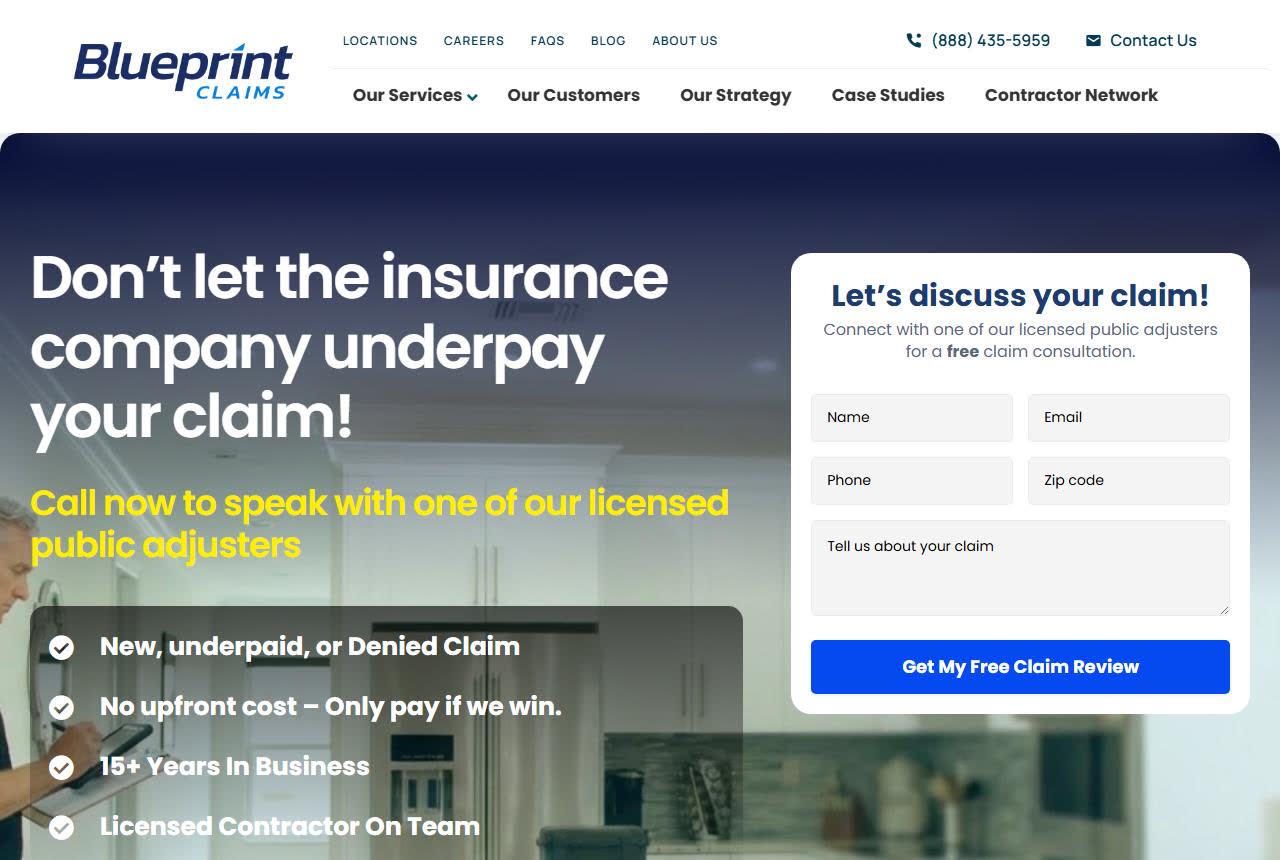
Why policyholders call Floridian Public Adjusters
Floridian Public Adjusters, operating as Blueprint Claims, was built to change how public adjusting gets done. Michael Zebold founded the firm in early 2011 with a specific vision: create an organization where solo adjusters could hang their license and receive real formal training along with claim assignments, instead of going it alone. The result is a firm with serious depth and a rallying cry that says it all: Don't let the insurance company UNDERPAY your claim.
The leadership brings a rare mix of construction fluency and claims firepower. Firm Partner and Senior Public Adjuster Michael Zebold, SPPA (License #P168773) came up through web design and marketing before adjusting. Managing Partner and Senior Public Adjuster Arthur Camayd, SPPA (License #P177780) has been involved in thousands of claims since 2009 and holds dual architecture degrees from Florida International University and Florida Atlantic University, along with CPPA and SPPA designations from The Institutes and a stack of technical certifications including IICRC Water and Fire and Smoke Restoration, HAAG Commercial Roof Inspector, OSHA-10, and IAUA Umpire and Appraiser. Both partners also serve as neutral umpires in appraisal disputes, a credential that speaks to how the industry itself rates them.
The reach is genuinely national. Blueprint fields licensed adjusters across Florida, Georgia, South Carolina, North Carolina, Virginia, Pennsylvania, Ohio, Illinois, Minnesota, Louisiana, Texas, Tennessee, Colorado, Arizona, and California, plus the Virgin Islands and Puerto Rico, and continues to expand. The firm is a member of NAPIA, FAPIA, GAPIA, and TAPIA, has handled thousands of property insurance claims, and recovered many millions for policyholders. Free property inspection, complimentary consultation, and one guarantee: We Only Get Paid If You Win.
What a public adjuster does
A public adjuster is the only kind of adjuster licensed to work for you, the policyholder, not the insurance company. They document the loss, build a detailed scope and estimate, read the policy for coverage you may have missed, and negotiate the payout with the carrier, working on a percentage of what you recover.
A public adjuster is not a contractor and not an attorney: they cannot make repairs, file suit, or give legal advice. See what a public adjuster actually does and when to hire one.
The fee, in Florida
Florida caps a public adjuster's fee at 20% of the claim payment, dropping to 10% for claims from a declared state of emergency (Fla. Stat. § 626.854). The fee applies only to what the insurer pays; it may not be charged on your deductible.
Full fee guide → · Read your contract and the current statute.
Get the exact legal name and license (or NPN) number, then confirm an active public adjuster license in the state where your property sits. Do it on the official roster, never take the number on a business card at face value.
Florida Department of Financial Services licensee search →A public adjuster, or an attorney?
A public adjuster is the right call when the carrier agrees the loss is covered but the check is too low. When the carrier denies coverage outright, alleges misrepresentation, sits on the claim past the statutory deadlines, or acts in bad faith, that is legal territory a public adjuster cannot enter.
If your claim was denied rather than merely underpaid, start with a free attorney review; see public adjuster vs. attorney, why claims get denied, and the deadlines that protect your rights.
HurricaneLaw.Pro lists Floridian Public Adjusters from the state public-adjuster license roster. The profile is compiled from the firm's own public website and materials. We are not affiliated with Floridian Public Adjusters, and the listing is not a ranking or an endorsement. Confirm current licensing on the state roster above before you hire anyone. A firm that would like its listing updated or removed can reach us through the contact page. Not legal advice; consult an attorney about your specific claim.
Denied, not just underpaid? Talk to an attorney first.
Send the denial letter and your declarations page. You'll get a straight read on whether this is a valuation fight for an adjuster or a coverage fight that needs a lawyer.
 HURRICANELAW.PRO
A comprehensive property-insurance claim resource for policyholders: denied and underpaid claims, coverage and bad-faith law, storm dossiers, carrier profiles, city guides, and the complete claims playbook. Florida and South Carolina.
▸ SEE THE FULL SITE MAP → ▸ KNOWLEDGE MAP: EVERY ENTITY AND SOURCE →Mount Pleasant, SC 29464
Coverage summaries, policy-language quotations, dollar figures, deadlines, and chart examples throughout this site are general information based on typical or standard policy forms and are illustrative only: they are not a quote, a guarantee of coverage, or a promise of any outcome. Every insurance policy is different: your own policy, endorsements, and state law control, so read your policy and confirm current statutes. Weather imagery courtesy of NOAA, the National Hurricane Center, and the National Weather Service. Nothing on this site is legal advice; consult an attorney about your specific claim.
HurricaneLaw.Pro is attorney advertising paid for by Halversen Law, LLC. Responsible attorney: Brent Halversen, 496 Bramson Court, Suite 100, Mount Pleasant, SC 29464. Operated by LARGE LLC, which is not a law firm. Nothing on this site is legal advice.
Halversen Law pays for this advertisement. It is a property-insurance law firm licensed in South Carolina and Florida and reviews every case-review submission.