- • A public adjuster is a state-licensed professional who represents the policyholder, not the carrier, in documenting, valuing, and negotiating a property-insurance claim.
- • There are three adjuster types: a company (staff) adjuster and an independent adjuster both work for the insurer; only the public adjuster works for you.
- • A public adjuster is paid on contingency, a percentage of what you recover. Florida caps that fee by statute (20%, or 10% for claims from a declared emergency in the first year, Fla. Stat. § 626.854); South Carolina sets no statutory cap.
- • A public adjuster is not a contractor (they do not repair anything) and not a lawyer (they cannot sue the carrier, pursue bad faith, or give legal advice).
- • Listed by license, not vetted. Always confirm an active public-adjuster license on the state roster before you sign anything.
The three kinds of adjuster
The word "adjuster" hides an important fact: most adjusters who touch your claim are paid by the insurance company. Sorting out who works for whom is the first thing to understand before you decide whether you want your own.
Only the third row works for you. That single fact, a duty that runs to the policyholder instead of the carrier, is what a public adjuster is.
What a public adjuster does, step by step
The job is documentation and negotiation. A public adjuster does not fix your roof and does not file a lawsuit. The work sits in between, turning a loss into a fully-supported, fully-priced claim the carrier has to answer.
What they can, and cannot, do
- Read and interpret your policy to identify coverage that applies.
- Inspect, photograph, and measure the damage.
- Prepare a line-item scope and estimate of the loss.
- File the claim and communicate with the carrier’s adjuster on your behalf.
- Negotiate scope, pricing, and depreciation to reach a settlement.
- Prepare and file supplemental claims for hidden damage.
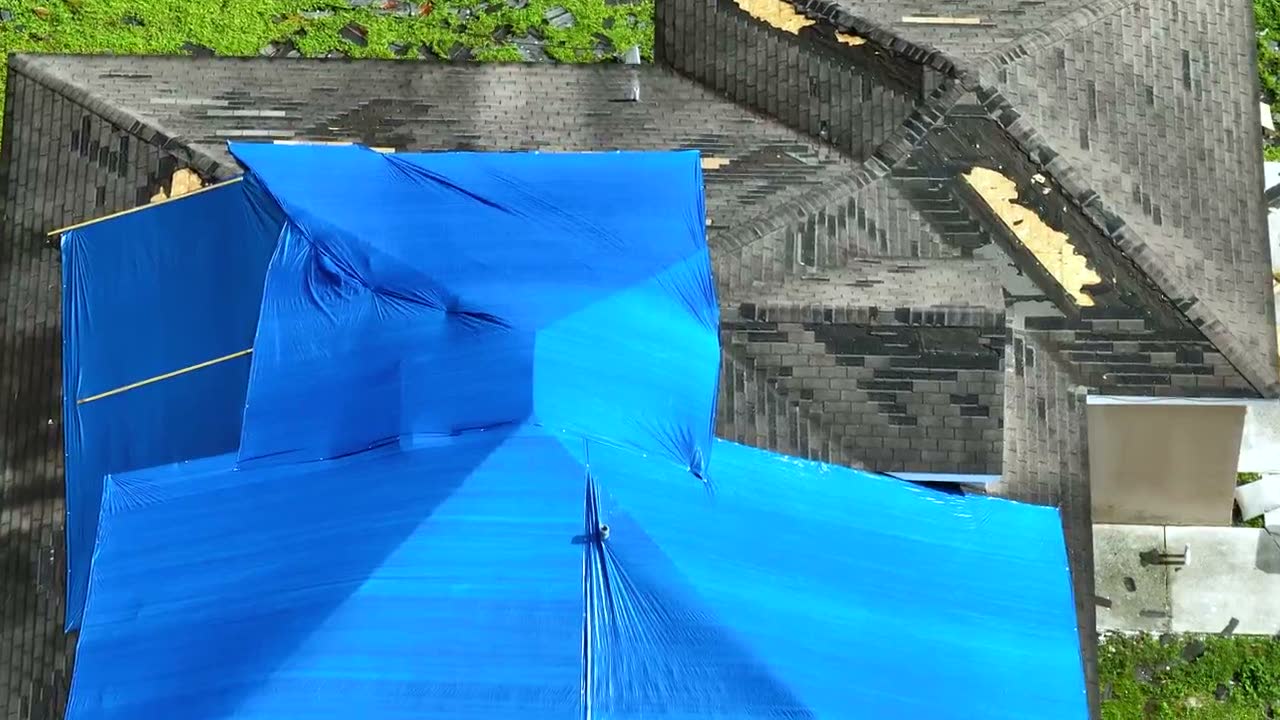
- Repair, tarp, or rebuild the property (that is a contractor’s job).
- File a lawsuit or represent you in court.
- Pursue a statutory bad-faith or civil-remedy action.
- Give you legal advice or interpret the law for you.
- Guarantee a specific payout or a turnaround time.
- Require an up-front fee before any recovery (fee is contingent).
The line between "can" and "cannot" is set by state licensing law and varies. When a dispute crosses from the value of a covered loss into a coverage denial, bad faith, or litigation, that is an attorney’s territory, see public adjuster vs. attorney.
How a public adjuster gets paid
A public adjuster works on contingency, a percentage of what you recover, so there is usually no fee unless the claim pays. That percentage is the single most important number in the contract, and it is where the two states differ sharply.
Capped at 20% of the claim payment, and 10% for claims arising from an event that is the subject of a declared state of emergency, in the first year after the declaration (Fla. Stat. § 626.854). The fee applies to what the insurer pays and may not be charged on your deductible.
No statutory percentage cap. The compensation is whatever the written contract states, which must carry the disclosures required under S.C. Code Title 38, Chapter 48. Read the percentage and what it applies to before signing.
The full breakdown, how the percentage is calculated, what the emergency cap covers, and how it interacts with your deductible, is in the dedicated public-adjuster fees guide.
Public adjuster vs. contractor vs. attorney
These three roles get confused constantly, and the confusion costs homeowners money. Each does a different job at a different stage of the claim:
- Contractor: repairs the property. May write a repair estimate, but adjusting the claim for a fee generally requires a public-adjuster license.
- Public adjuster: documents, values, and negotiates the claim the carrier agrees is covered. Cannot litigate.
- Attorney: steps in when coverage is denied, the carrier acts in bad faith, or the dispute becomes legal. Only an attorney can file suit or pursue a statutory bad-faith claim.
Many claims use them in sequence: a contractor tarps the roof, a public adjuster documents and negotiates, and an attorney takes over if the carrier refuses to deal fairly.
When a public adjuster helps most
A public adjuster earns their percentage on larger, more complex, or contested valuation claims, where the documentation burden is heavy and the gap between the carrier’s number and the policy’s obligation is wide. On a small, clean claim under or near the deductible, the fee can outweigh the benefit.
The decision framework, loss size, complexity, whether the carrier disputes the value or the coverage, is laid out in when to hire a public adjuster. Before you hire anyone, run them through the red-flags checklist and verify the license yourself.
Public adjuster FAQ
What is the difference between a public adjuster and the insurance company’s adjuster?
The company (staff) adjuster and the independent adjuster both work for and are paid by the insurance company. A public adjuster is licensed to represent you, the policyholder, and is paid a percentage of what you recover. The public adjuster is the only one of the three whose duty runs to the insured.
Is a public adjuster the same as a contractor?
No. A public adjuster documents and negotiates the claim; a contractor repairs the property. In Florida it is generally unlawful for an unlicensed person, including many contractors, to adjust a claim for a fee. A contractor may prepare a repair estimate, but negotiating the claim value for compensation requires a public-adjuster license.
Does a public adjuster guarantee a bigger payout?
No one can guarantee an outcome, and any promise of a specific result is a red flag. A public adjuster documents and argues the claim; whether that changes the number depends on the policy, the facts, and the loss.
How much does a public adjuster charge?
A percentage of what you recover, set by contract. Florida caps the fee at 20% of the claim payment, and 10% for claims arising from a declared state of emergency (Fla. Stat. § 626.854). South Carolina has no statutory percentage cap; the fee is whatever the written contract states. Confirm the current statute and read your contract before signing.
Can a public adjuster help if my claim was already denied?
Sometimes, but a flat denial of coverage is often a legal dispute rather than a valuation dispute. A public adjuster negotiates amounts the carrier agrees are covered; when coverage itself is denied, a free attorney review is usually the better first step.
- Fla. Stat. § 626.854, “Public adjuster” defined; conduct and fees ↗, Florida’s public-adjuster statute: definition, conduct rules, and the fee cap (20%, 10% for declared-emergency claims).
- S.C. Code Title 38, Chapter 48, Public Insurance Adjusters ↗, South Carolina’s licensing and conduct framework for public insurance adjusters.
- Florida DFS, Licensee Search ↗, The state’s free, public roster of licensed adjusters. Verify any adjuster before hiring.
- South Carolina DOI, licensing ↗, South Carolina Department of Insurance, licensing and consumer resources.
Not legal advice. HurricaneLaw.Pro lists public adjusters by license and does not vet, rank, endorse, or recommend any adjuster. Confirm the current statute and your specific facts with a licensed attorney. Fee-cap figures per Fla. Stat. § 626.854; South Carolina public-adjuster licensing per S.C. Code Title 38, Chapter 48.
Denied, not just underpaid? Talk to an attorney first.
A public adjuster negotiates the value of a covered loss. If the carrier denied coverage outright or is acting in bad faith, that is a legal fight, send the denial letter and your declarations page for a straight read.

 HURRICANELAW.PRO
A comprehensive property-insurance claim resource for policyholders: denied and underpaid claims, coverage and bad-faith law, storm dossiers, carrier profiles, city guides, and the complete claims playbook. Florida and South Carolina.
▸ SEE THE FULL SITE MAP →Coverage summaries, policy-language quotations, dollar figures, deadlines, and chart examples throughout this site are general information based on typical or standard policy forms and are illustrative only: they are not a quote, a guarantee of coverage, or a promise of any outcome. Every insurance policy is different: your own policy, endorsements, and state law control, so read your policy and confirm current statutes. Weather imagery courtesy of NOAA, the National Hurricane Center, and the National Weather Service. Legal services are provided by Halversen Law. Nothing on this site is legal advice; consult an attorney about your specific claim.
Legal matters are handled by Halversen Law, a law firm licensed in Florida and South Carolina.