- • A public adjuster tends to pay off on larger, more complex, or contested claims where documentation and negotiation move the number.
- • On a small, clean claim near or below the deductible, the fee can outweigh the benefit.
- • They handle valuation disputes: the carrier agrees the loss is covered but the check is low. A coverage denial is a legal question for an attorney.
- • Timing helps: bringing one in early, before a lowball is locked in, is usually better than after months of back-and-forth.
- • Whatever you decide, verify the license and get the fee agreement in writing first. Listed by license, not vetted.
The core question
A public adjuster is worth hiring when the value they can add to the claim, after their percentage, is greater than what you would recover on your own. That is the whole decision. Everything else is a way of estimating both sides of it.
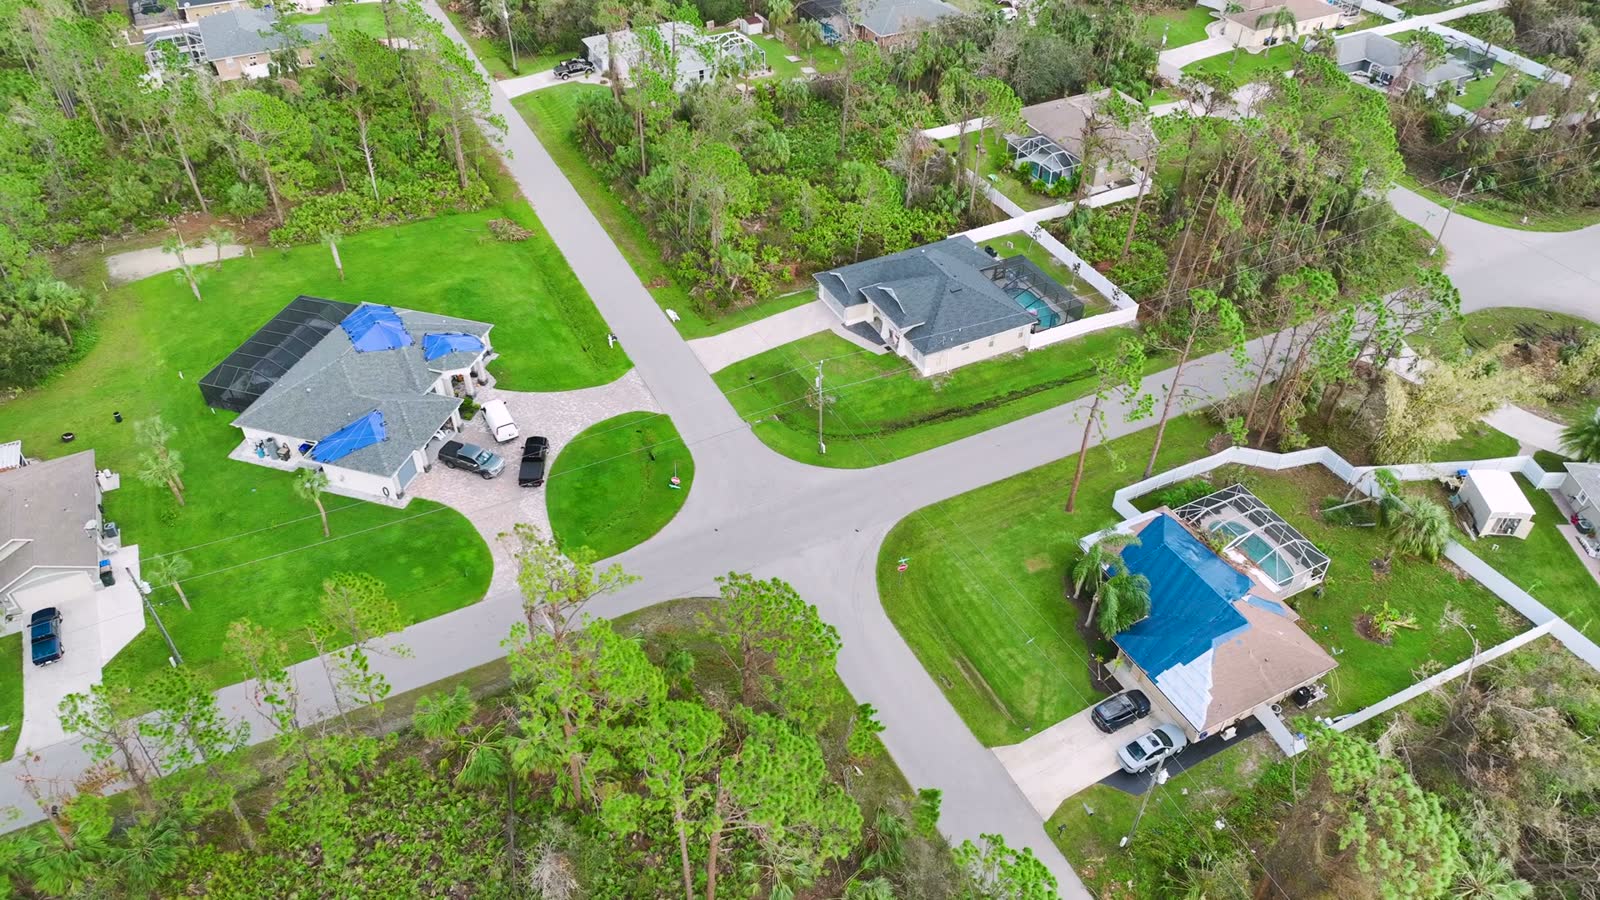
Because the fee is a percentage of recovery, the arithmetic favors larger and more contested claims. A wide gap between the carrier’s number and a fair number leaves room for a professional to work; a fair, straightforward estimate does not.
Five factors that decide it
Put a number on the cost side with the deductible calculator and the fee math in the fees guide.
Good-fit vs. poor-fit claims
- Large hurricane or wind loss with a wide gap between your number and the carrier’s.
- Complex claim, multiple coverages, code upgrades, contents, or business interruption.
- Hidden or structural damage that needs professional documentation.
- You lack the time, records, or capacity to document and negotiate it yourself.
- Small claim near or below the deductible, where the fee eats the benefit.
- The carrier’s estimate is already close to fair.
- A straightforward, well-documented loss you can handle yourself.
- The real problem is a coverage denial or bad faith. That is an attorney’s job, not an adjuster’s.
Timing: when in the claim to bring one in
Earlier usually beats later. Brought in near the start of a large or complex claim, a public adjuster can shape the documentation before the carrier’s estimate hardens. Brought in after months of back-and-forth, they inherit a record they did not build and a number that may already be entrenched.
Deadlines run the whole time. In Florida, notice of a new claim is generally due within one year of the loss and supplemental claims within 18 months (Fla. Stat. § 627.70132); South Carolina policies require prompt notice and carry a contractual suit limitation. For past storms whose one-year windows have already closed, the question is usually about an already-filed, denied, or underpaid claim, not a fresh filing. Confirm your dates on the deadline countdown and in claim timelines.
When an attorney fits better
A public adjuster cannot file suit, cannot pursue bad faith, and cannot give legal advice. So when the problem is not "how much" but "covered or not," "on time or not," or "handled fairly or not," an attorney is the right call, often before a public adjuster, sometimes alongside one.
Denied outright? Accused of misrepresentation? Stonewalled past the deadlines? Start with the public adjuster vs. attorney breakdown, then a free attorney review. A denied claim is a legal question first.
Before you sign
- Verify the license on the free state roster, active, public-adjuster line, right state.
- Get the fee percentage and everything it applies to in writing; confirm it is within the state cap (Florida) or clearly stated (South Carolina).
- Run them through the red-flags checklist, especially door-knockers and sign-on-the-spot pressure.
- Never sign under pressure. A legitimate adjuster will give you time to verify and read.
When-to-hire FAQ
Is it worth hiring a public adjuster for a small claim?
Often not. A public adjuster charges a percentage of recovery, so on a small claim near or below the deductible the fee can eat most of the benefit. Public adjusters generally add the most value on larger, complex, or contested valuation claims. Run your deductible first, then weigh the likely recovery against the fee.
When is the best time to hire a public adjuster?
Generally earlier is better, before a low estimate is locked in and while the damage is still well documented. Bringing one in at the start of a large or complex claim lets them shape the documentation; bringing one in after months of dispute is still possible but leaves less room to work. Deadlines run either way, so do not wait indefinitely.
Can I hire a public adjuster after the insurer already paid?
Sometimes, for a supplemental claim or a reopened claim if new or hidden damage surfaces, within the statutory window. Check whether the fee applies to money already paid or only to new recovery, and confirm the deadline for supplemental claims in your state before proceeding.
Should I hire a public adjuster or an attorney?
A public adjuster handles the value of a covered claim; an attorney handles coverage denials, delay, and bad faith. If your claim was denied outright, or the carrier is acting unreasonably, that points to an attorney. If it is covered but underpaid, an adjuster or appraisal may resolve it. A free case review can tell you which you are in.
Do I have to hire anyone at all?
No. Many homeowners document and negotiate their own claims successfully, especially straightforward ones. Our claims guides walk through the photo protocol, the paperwork, and the appraisal process. Hire help when the size, complexity, or dispute justifies it.
- Fla. Stat. § 626.854, Public adjuster fees ↗, Florida’s fee cap (20%, 10% for declared-emergency claims), the cost side of the decision.
- Fla. Stat. § 627.70132, Notice of property insurance claim ↗, Florida notice deadlines (1 year new claim, 18 months supplemental), why timing matters.
- S.C. Code Title 38, Chapter 48, Public Insurance Adjusters ↗, South Carolina public-adjuster licensing and contract framework.
- Florida DFS, Licensee Search ↗, Verify any adjuster’s license before hiring.
Not legal, insurance, or financial advice, and not a recommendation to hire or not hire anyone. HurricaneLaw.Pro lists public adjusters by license and does not vet, rank, or recommend them. Confirm current law and your dates with a licensed attorney. Deadlines per Fla. Stat. § 627.70132; fees per § 626.854; South Carolina per S.C. Code Title 38, Chapter 48.
Not sure it’s a valuation fight? Find out first.
Send the estimate or the denial and your declarations page. A property-insurance attorney will tell you whether an adjuster can help, or whether this is a coverage fight that needs a lawyer.

 HURRICANELAW.PRO
A comprehensive property-insurance claim resource for policyholders: denied and underpaid claims, coverage and bad-faith law, storm dossiers, carrier profiles, city guides, and the complete claims playbook. Florida and South Carolina.
▸ SEE THE FULL SITE MAP →Coverage summaries, policy-language quotations, dollar figures, deadlines, and chart examples throughout this site are general information based on typical or standard policy forms and are illustrative only: they are not a quote, a guarantee of coverage, or a promise of any outcome. Every insurance policy is different: your own policy, endorsements, and state law control, so read your policy and confirm current statutes. Weather imagery courtesy of NOAA, the National Hurricane Center, and the National Weather Service. Legal services are provided by Halversen Law. Nothing on this site is legal advice; consult an attorney about your specific claim.
Legal matters are handled by Halversen Law, a law firm licensed in Florida and South Carolina.