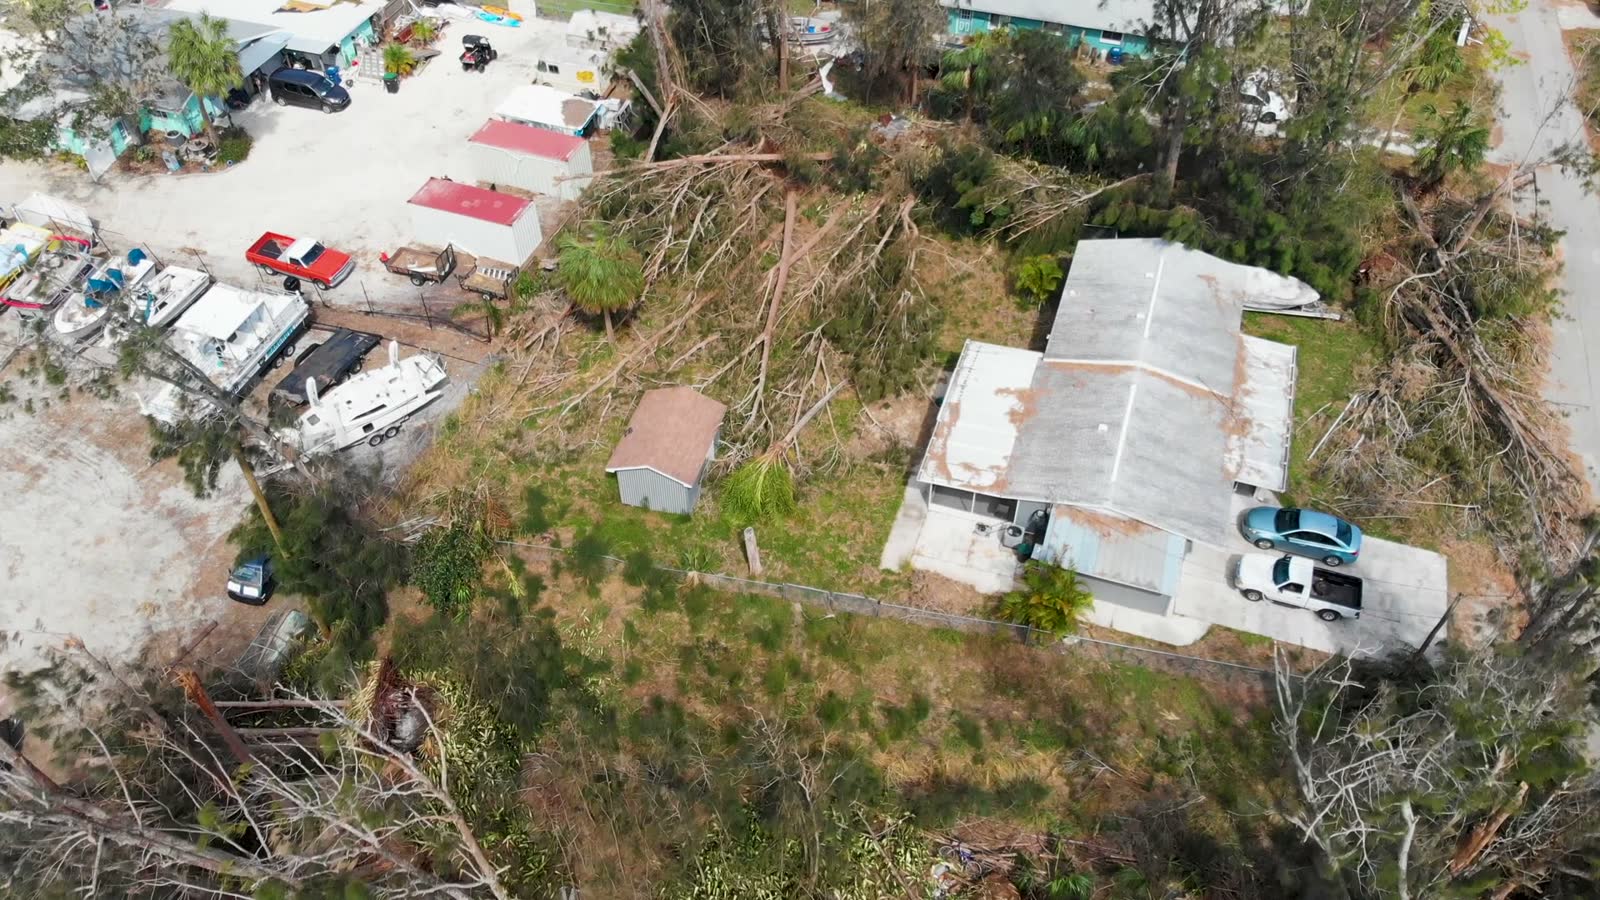
Gainesville is an inland university city on karst terrain under a thick tree canopy, and its hurricanes come as wind, rain, and falling trees rather than surge. Dora crossed North Florida near here in 1964; Irma drove tropical-storm-to-hurricane-force winds across the county in 2017; and Idalia in 2023 and Helene in 2024 sent major-hurricane winds up from Big Bend landfalls, dropping trees onto homes and knocking out power for days. The resulting claims raise the hardest question in Florida property insurance: which storm, and which peril, owes for the damage?
What Gainesville claims turn on
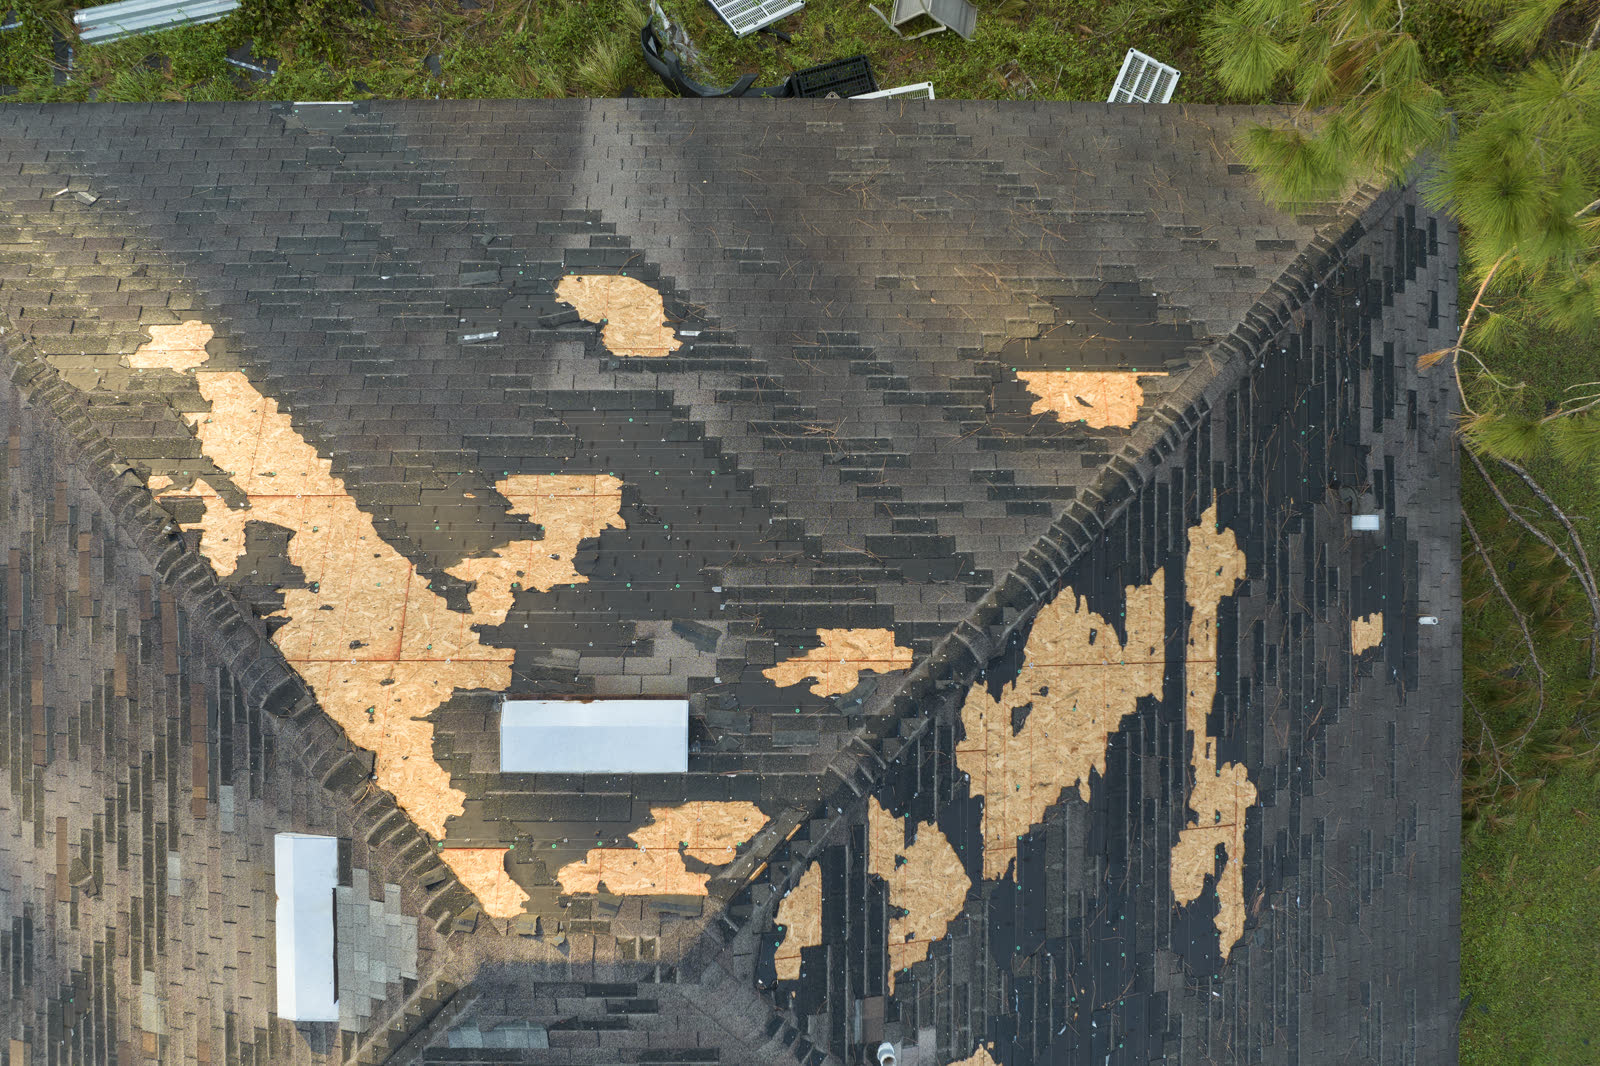
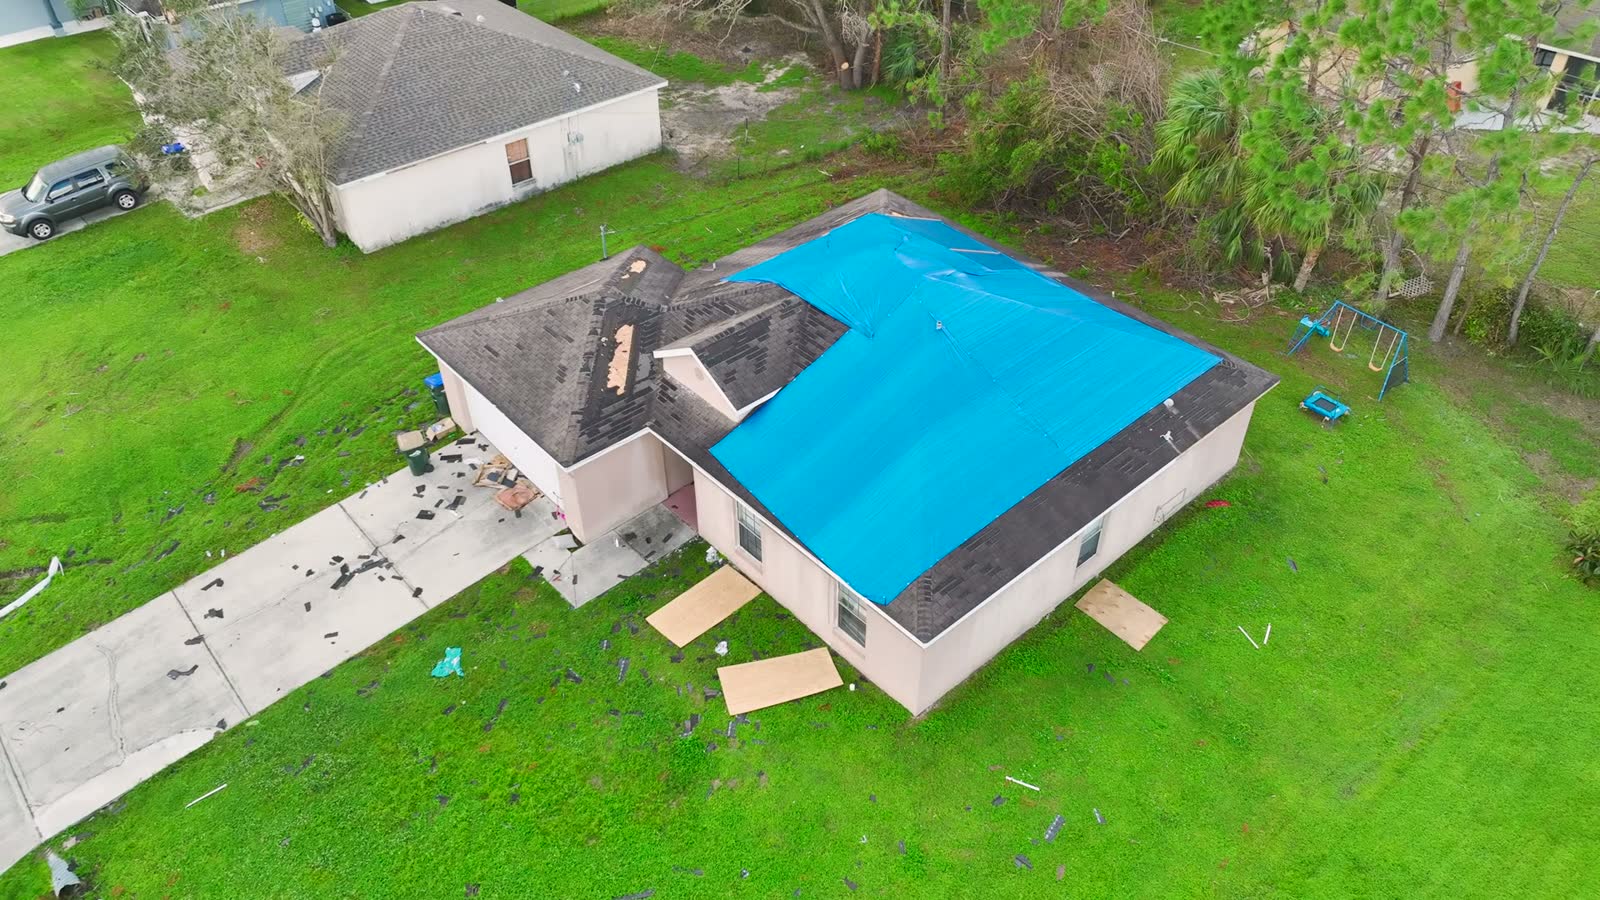
Wind is covered, behind a hurricane deductible that is a percentage of the home’s insured value, not the loss. Here the fight is usually about trees and roofs: a fallen tree that punctures the roof is a covered wind loss, but insurers argue the interior water that follows was long-term leakage or wear, and they discount roof claims to repair rather than replace. Where creeks like Hogtown and Sweetwater and the Paynes Prairie basin overtop, that rising water is excluded flood needing NFIP coverage, separate from the wind claim. Extended outages also trigger food-spoilage and additional-living-expense provisions that carriers routinely underpay.
The law here
Florida gives you one year from the date of loss to give notice of a hurricane claim and 18 months for a supplemental claim (§ 627.70132, as amended in December 2022, ch. 2022-271), and the carrier must pay or deny within 60 days of a complete proof of loss (§ 627.70131). For storms that are already years past, those notice windows have generally closed, but a claim you already filed that was denied or underpaid can still have options, and the deadline to sue on a filed claim is longer. These are general figures; confirm the current statutes and your own dates with counsel before relying on them.